


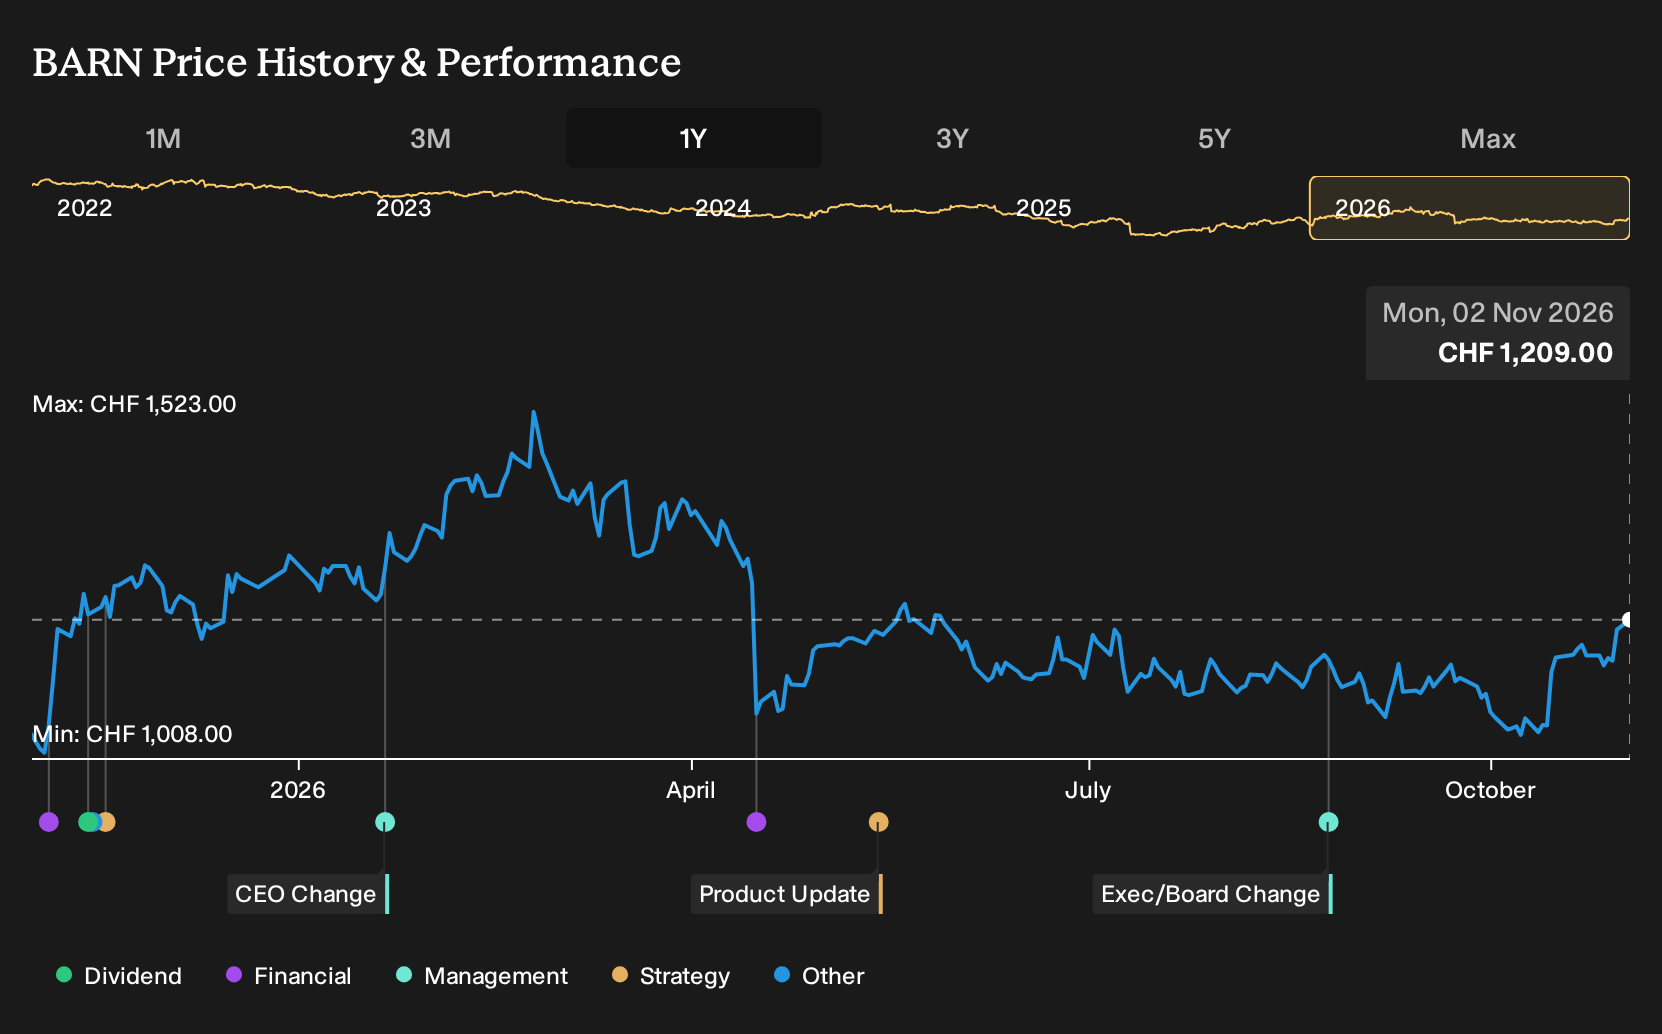
Barry Callebaut’s new chief executive chose to start with pain, issuing a profit warning as part of a plan to speed up sales growth and watching the share price slump on the announcement. Investors who held Barry Callebaut over the past year are up 22.0%, including dividends. If you had been deciding on 2 November 2025, what beliefs about that turnaround plan would have made this outcome feel reasonable?
If the move has made Barry Callebaut harder to judge, start where the gap is still open and scan 193 high quality undervalued stocks.
The Two Barry Callebaut Stories Investors Had To Weigh
The shares cost CHF1,046 at the start of the period, and investors in Barry Callebaut had to choose which story about cocoa, costs and demand felt more convincing.
The bull narrative pointed to a Fair Value of CHF1,228, a notional price implied by its assumptions, built on the Next Level program, 3.2% revenue growth and a 3.6% profit margin within three years.
The bear narrative anchored on a Fair Value of CHF790 and focused on surging cocoa prices, supply risk and the possibility that health trends would pressure chocolate volumes.
What The Results Changed For The Barry Callebaut Debate
The clearest new fact was Barry Callebaut’s profit warning and 16% share price drop, which challenged the easy version of the bull case. At the same time, H1 2026 results showed revenue lower at CHF6,752.2m while net income and net margin rose to CHF89.4m and 1.3%. Taken together, the evidence cut both ways.
The episode centered on whether a turnaround could lift profitability even as sales pressure and cocoa volatility persisted. For any similar stock, track whether margin targets show up in reported net margin, even when revenue is flat or falling.
What Barry Callebaut's Price Already Assumes
Barry Callebaut now trades at CHF1,209, after a 22.0% gain over the past year. The selected Narrative’s Fair Value estimate sits below this level, which implies a more cautious stance on what the current quote already bakes in.
The Narrative leans on weak chocolate consumption, tight operating leverage and a heavier reliance on higher margin gourmet and specialties. To pay today’s price, you would need to assume that mix shift, service recovery and volume repair are strong enough to offset muted outsourcing and soft demand.
"The main requirement for improvement is that Barry Callebaut successfully shifts its mix toward higher margin gourmet, specialties and solutions, while restoring service and quality to regain volumes and share. The current numbers and narrative imply that Barry Callebaut’s share price already reflects a fairly valued, bullish case that assumes execution on mix improvement, cocoa market normalization and lower financing costs."
One Narrative disagrees with today's price. → See where this Narrative says Barry Callebaut should trade
Looking One Shelf Beyond Barry Callebaut
Barry Callebaut lives where indulgence meets habit. Chocolate is a ritual. Snacks and drinks are another.
If you care about cocoa exposure, you might also care about the wider treats in a shopper’s basket.
Another large food and beverage group has built its story around that mix of refreshment and convenience.
It focuses on steady product demand, dependable cash generation and a long record of returning money to shareholders.
The interesting question is how a business like that behaves in your portfolio when chocolate sentiment swings as sharply as cocoa prices.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 46% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com