


- Fifth Third Bancorp reported third quarter 2026 results with net interest income of US$2,271 million and net income of US$866 million, alongside net charge offs of US$139 million that were lower than the prior year period.
- The combination of higher net interest income, higher net income and reduced net losses charged off indicates a period of improved profitability and credit outcomes for Fifth Third Bancorp.
- The focus now turns to how Fifth Third Bancorp's stronger earnings and lower charge offs could influence its longer term investment narrative.
Compare Fifth Third Bancorp's earnings and lower charge-offs with those of other banks by reviewing our hand picked list of list of solid balance sheet and fundamentals (24 results)
Fifth Third Bancorp Investment Narrative Recap
For a shareholder, the core belief around Fifth Third Bancorp is that a deposit led model, technology heavy payments platforms and Comerica integration benefits can translate into steadier earnings over time. The latest quarter, with higher net interest income and net income plus lower net charge offs, supports that credit costs are currently manageable rather than a major swing factor.
The near term swing issue still sits in deposit pricing and integration execution. Competition for funding and any repeat of online or access issues after system changes could quickly eat into the margin benefit investors are watching. Recent numbers help, but they do not remove that execution risk.
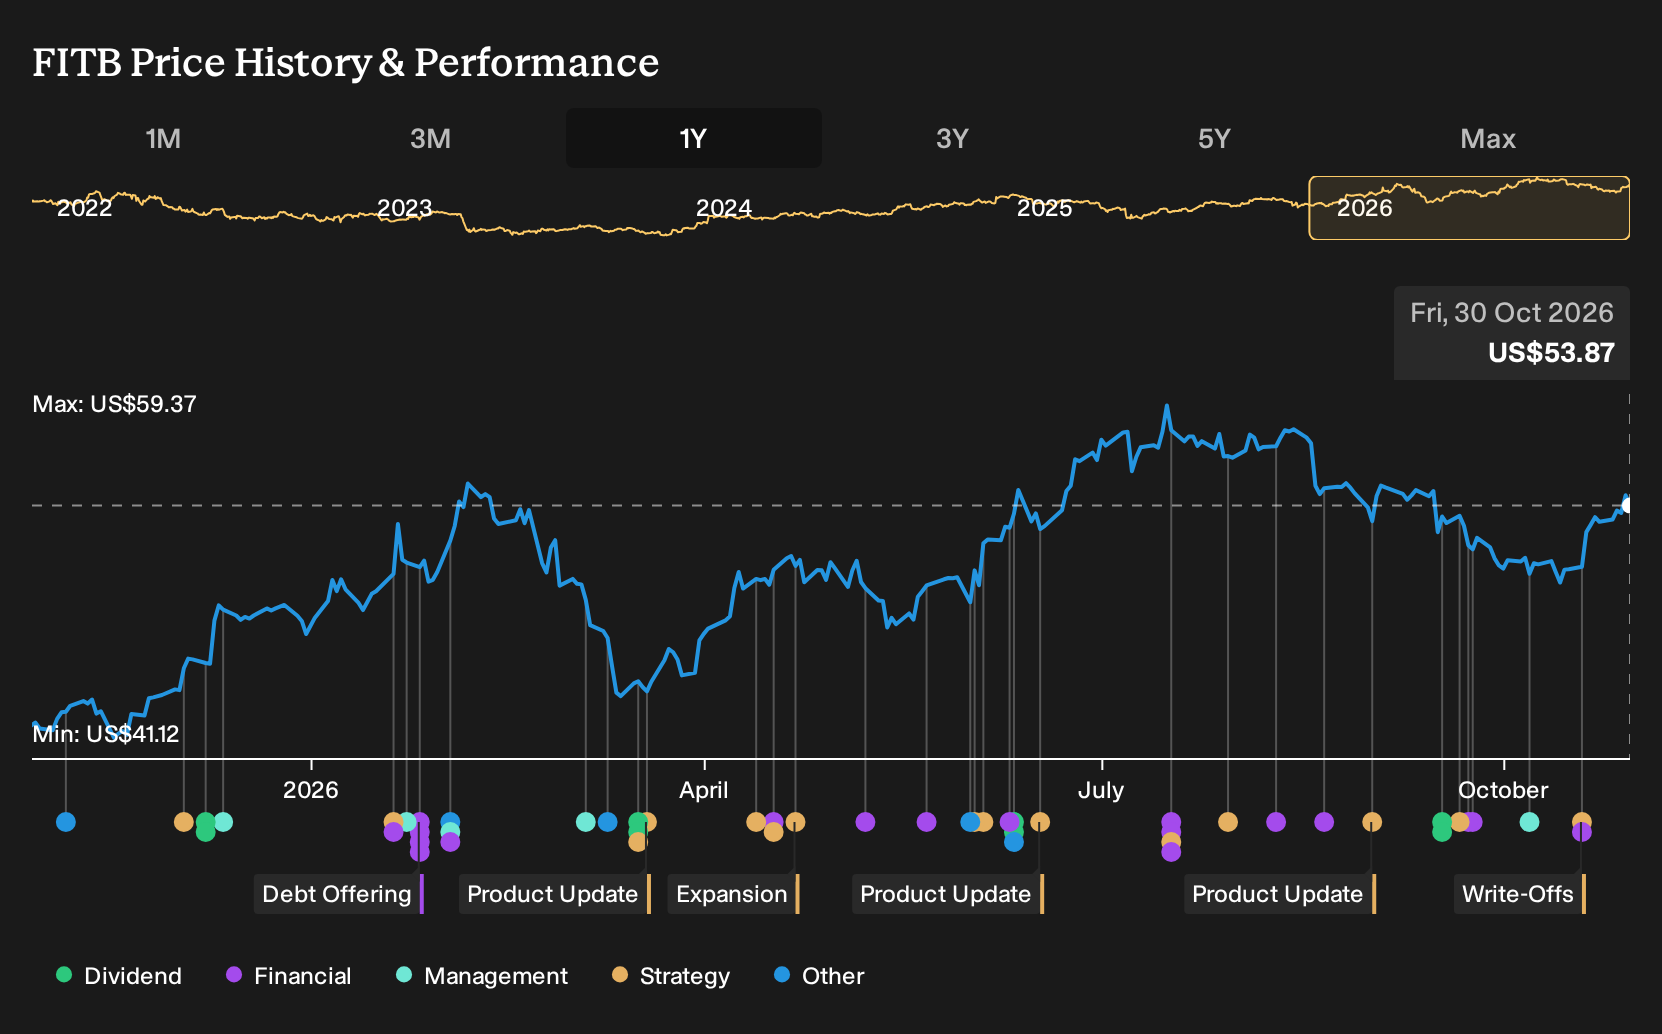
The most relevant update here is the third quarter 2026 earnings report. Net interest income of US$2,271 million and net income of US$866 million, alongside US$139 million of net losses charged off, provide a clearer read on how Fifth Third Bancorp is handling growth versus credit quality as integration and market expansion progress.
These figures matter because they frame the main catalysts investors often focus on. Payments and deposit platforms, technology investments and the Comerica synergy targets all need a stable credit backdrop to translate into durable earnings. Lower charge offs this quarter support that picture for now, while leaving open questions on deposit costs and digital reliability.
Fifth Third Bancorp's current analyst narrative points to revenue of US$16.4b and earnings of US$4.3b by 2029, which lines up with an assumed 17.7% yearly revenue growth rate and an earnings increase of about US$2.1b from US$2.2b today.
Discover how Fifth Third Bancorp's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community has only three fair value estimates for Fifth Third Bancorp, yet they already stretch from about US$61.49 to US$97.54 per share. That spread shows how sharply opinions can diverge. When you consider risks around deposit competition and Comerica integration glitches, you have real reasons to compare several viewpoints before deciding how these earnings shape the story.
Explore 2 other Fifth Third Bancorp fair value estimates, including one that suggests it could be worth just $61.49.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fifth Third Bancorp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fifth Third Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fifth Third Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond Fifth Third Bancorp?
If the Fifth Third Bancorp story has sharpened your thinking, you can broaden your watchlist by scanning other companies that fit different risk, income and valuation profiles using the Simply Wall St Screener.
- For investors who want financial strength to do the heavy lifting, review a list of solid balance sheet and fundamentals (24 results) that pairs robust balance sheets with resilient fundamentals.
- If value is your starting point, scan through 36 high quality undervalued stocks that blends quality financials with prices that may sit below intrinsic worth.
- Income-focused investors can focus on reliable cash returns by filtering for 5 dividend fortresses that aim to combine yield with business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com