


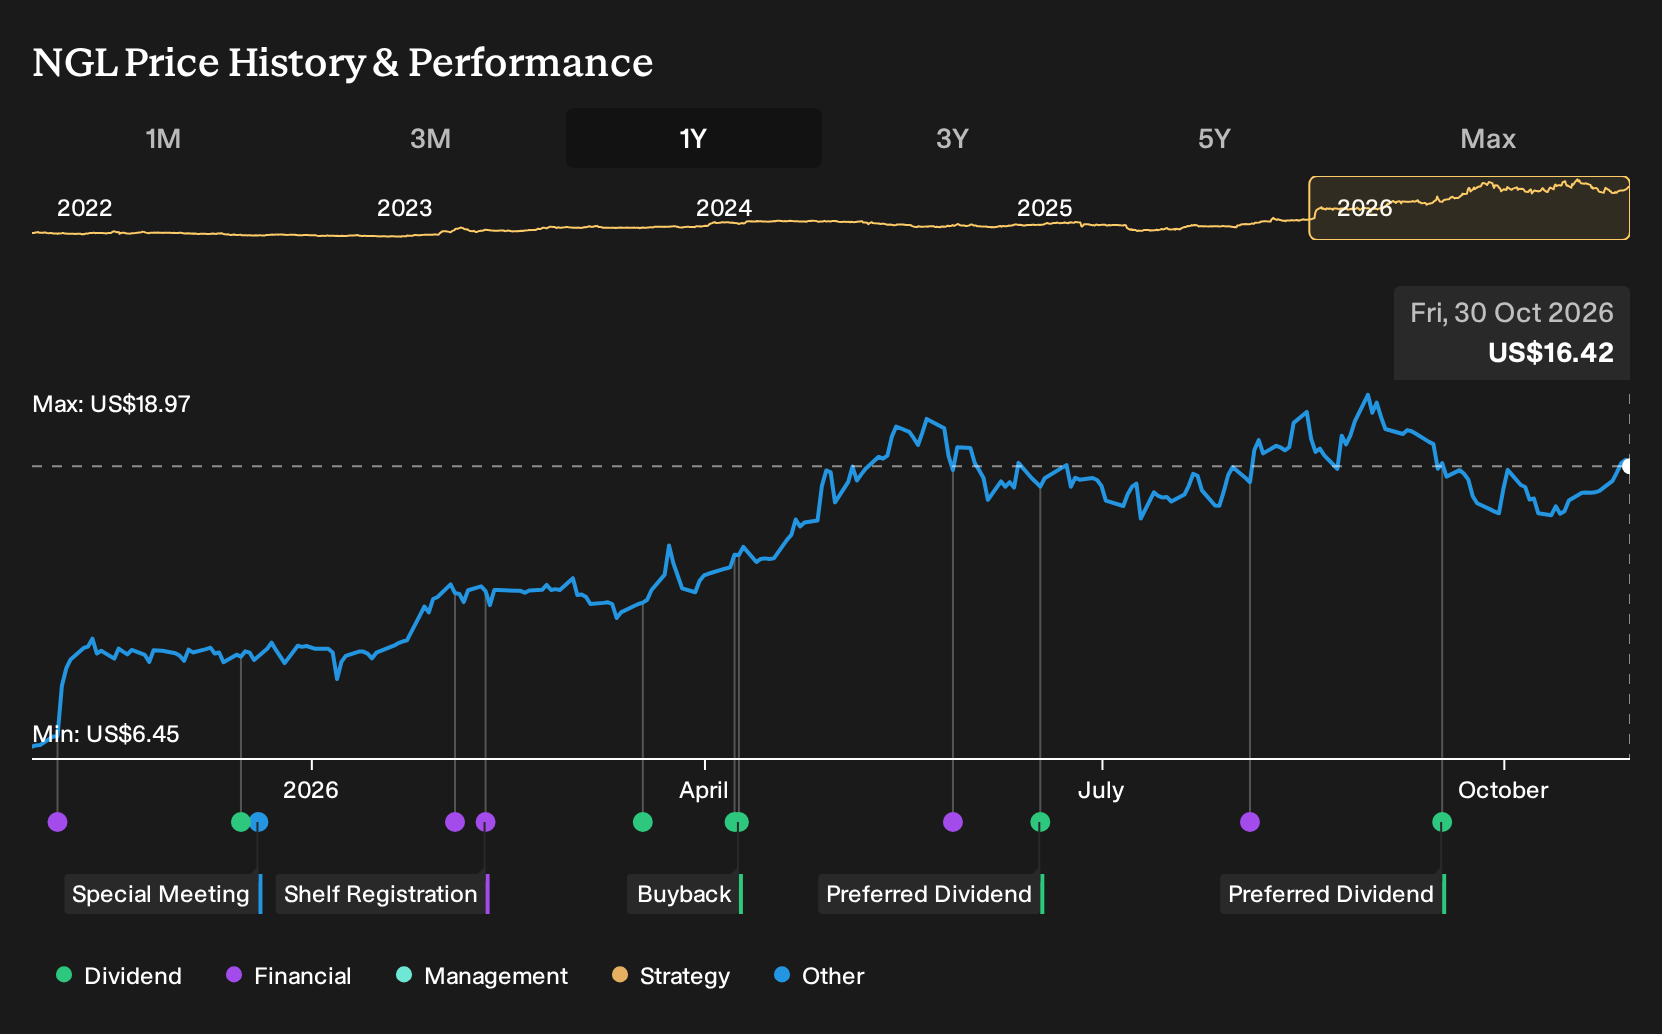
- NGL Energy Partners LP recently highlighted expectations for its second quarter fiscal 2027 results, with produced water disposal volumes and butane sales under focus alongside higher capital spending and borrowing costs.
- The partnership’s mix of growing contracted water and liquids activity, together with heavier investment and interest expense, gives investors a clearer view of the operating trade offs management is handling.
- This article will examine how NGL Energy Partners' investment narrative is being shaped by rising water disposal volumes in the context of increasing capital spending and borrowing costs.
Scan how NGL Energy Partners' mix of water infrastructure and liquids logistics compares with other income and infrastructure focused plays in the 5 dividend fortresses
What Is NGL Energy Partners' Investment Narrative?
To own NGL Energy Partners, you have to buy into a fairly simple premise. The partnership is trying to turn a mix of produced water infrastructure and liquids logistics into steadier earnings while still carrying the weight of capital intensive assets and higher interest expense. The upcoming second quarter fiscal 2027 report, with its focus on produced water disposal volumes and butane activity, goes straight to the question of whether operations are scaling efficiently enough to justify that burden.
In the short term, the key swing factors are execution in Water Solutions, pricing and volumes in Liquids Logistics, and how comfortably the business services its borrowing. The recent earnings preview ties those threads together by flagging both higher contracted activity and heavier spending. That combination can support the investment story or strain it, depending on how much cash flow actually shows up against those higher costs.
Yet the real tension in the NGL Energy Partners story only shows up once you look closely at ...
There's only one way to know the right time to buy, sell or hold NGL Energy Partners. Head to Simply Wall St's company report for the latest analysis of NGL Energy Partners's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NGL Energy Partners research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for NGL Energy Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NGL Energy Partners' overall financial health at a glance.
Looking for more investment ideas beyond NGL Energy Partners?
Once you have a view on NGL Energy Partners, it can help to compare that thesis with a few different types of opportunities filtered by quality, balance sheet strength, or potential mispricing.
- If you want to focus on lower priced shares but still care about underlying fundamentals, use the 8 elite penny stocks with strong financials to see which companies combine a modest share price with stronger financial profiles.
- For investors who care most about paying a reasonable price for quality, the 36 high quality undervalued stocks can highlight businesses that the current market price values more conservatively than their fundamentals.
- If balance sheet resilience is your starting point, filter for financially sturdier candidates through the list of solid balance sheet and fundamentals (24 results) and compare how their metrics stack up against your existing holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com