


TriCo Bancshares (TCBK) just released third quarter results, reporting higher net interest income and net income than a year earlier, and reaffirmed its quarterly dividend alongside modest net charge offs.
The earnings release and dividend affirmation landed after a softer stretch for the share price, with TriCo Bancshares down 10.42% on a 90 day share price basis, even as the year to date share price return is up 11.39% and the 1 year total shareholder return sits at 20.38%.
Scan TriCo Bancshares alongside other regional banks showing resilient earnings and dividend profiles using our hand picked 29 resilient stocks with low risk scores
Bulls point to TriCo Bancshares’ rising net interest income, steady profitability and ongoing dividend, while bears focus on the recent 10% share price slide and charge offs. Which side does the valuation currently support?
Most Popular Narrative: 10% Undervalued
TriCo Bancshares last closed at $52.52, compared with a widely followed fair value estimate of $58.67 that points to a modest discount. The key swing factor in that gap is the planned merger with First Hawaiian.
The all stock merger that combines TriCo Bancshares with First Hawaiian into a roughly $34b asset bank with 117 branches creates a larger Pacific regional platform that can support a broader customer base and product mix. This structure can feed into higher revenue and earnings over time.
See why 1 investors see TriCo Bancshares as 10% undervalued.
Result: Fair Value of $58.67 (UNDERVALUED)
Still, if TriCo Bancshares falls short on the planned 25% cost savings or if merger execution stumbles, the expected earnings uplift behind that 10% discount could fade.
Find out about the key risks to this TriCo Bancshares narrative.
Another View: TriCo Bancshares On Earnings Multiples
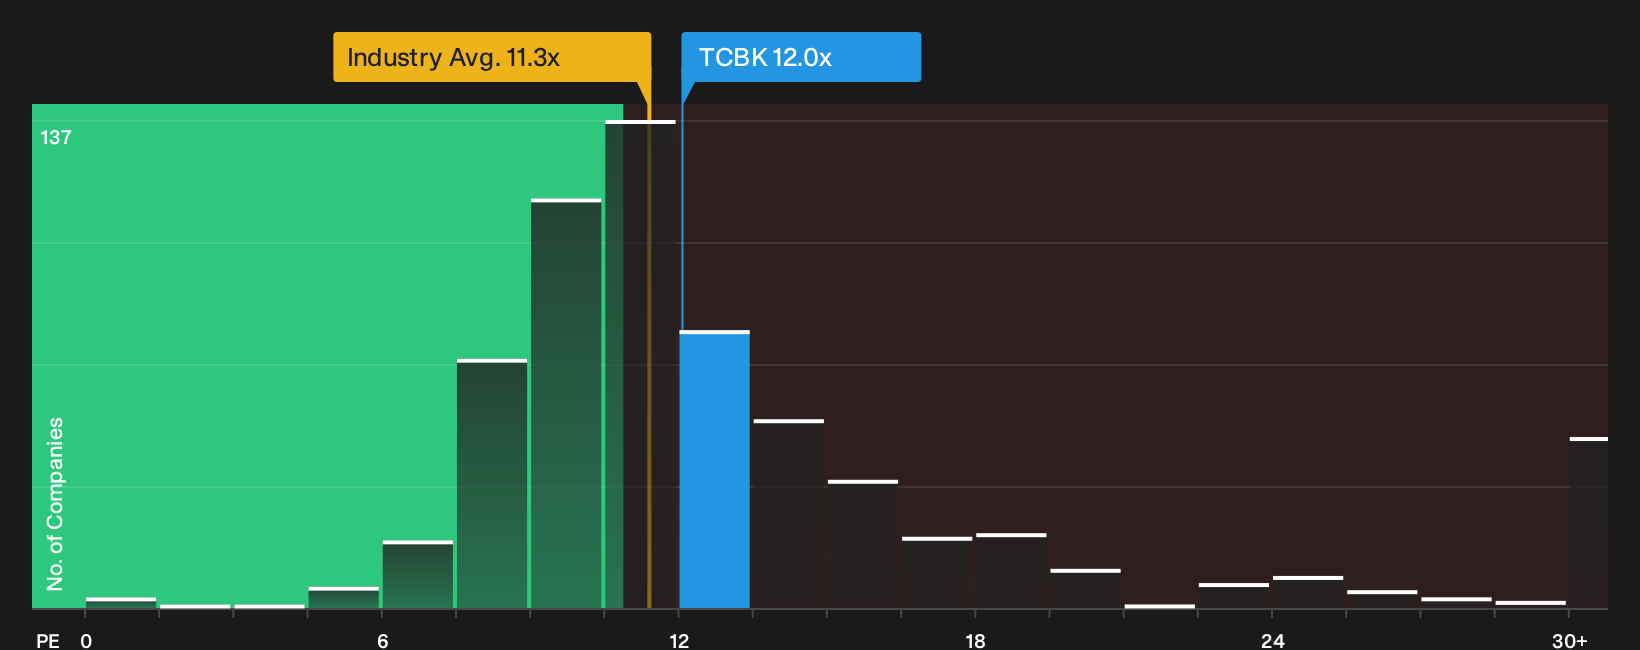
There is a different read on TriCo Bancshares when you look at the simple P/E lens. The stock trades around 12x earnings, slightly higher than the US Banks industry on 11.3x and above a fair ratio of 10.7x that the market could move toward over time.
This small premium suggests less of a clear bargain on current profits and more of a bet that merger execution or future profitability supports that extra multiple. The question for you is whether that higher P/E feels like a margin of safety or a valuation risk if expectations reset.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
After weighing both the upside narrative and the concerns, the real question is where you land on TriCo Bancshares now and how quickly you act on that view. Take a closer look at the upside factors analysts are watching by reviewing the 3 key rewards.
Looking for more investment ideas beyond TriCo Bancshares?
If TriCo Bancshares has your attention, broaden your watchlist with a few targeted sets of companies that match different goals, risk levels, and income needs.
- Spot potential bargains early by scanning a 8 elite penny stocks with strong financials that already show stronger fundamentals than many investors expect at this size.
- Prioritise value and quality together by reviewing a 36 high quality undervalued stocks that combine robust cash flows with balance sheets built to handle tougher conditions.
- Build a cash flow focused portfolio by zeroing in on 5 dividend fortresses that aim to pair higher yields with more resilient payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com