


Experian in focus after healthcare software sector report
Experian (LSE:EXPN) has come into focus after a new global report identified the business as a key player in healthcare contract management software, highlighting rising interest in AI-driven, cloud-based tools across the sector.
The healthcare software spotlight has arrived at a time when Experian’s share price momentum is picking up, with a 23.0% 1 month share price return and a 4.2% 7 day gain, even though the year to date share price return is still down 9.3% and the 1 year total shareholder return has declined 13.1%.
Scan beyond Experian and see which peers are also riding the healthcare software and AI trend with our curated list of 9 healthcare AI stocks
Experian now combines strong data and software credentials with a sharp short-term rebound in the share price. The key issue for investors lies in the numbers: is this quality already fully reflected in today’s valuation?
Most Popular Narrative: 18% Undervalued
On the most followed narrative, Experian’s fair value sits at £36.77 against a last close of £30.23. This puts the current rebound in context and frames the healthcare software exposure as part of a bigger data and AI story.
Experian is scaling AI and agentic products such as the Ascend Agent Operating System, RiskOS, Patient Access Curator, Agent Trust and Model Risk Manager across credit, fraud, governance and healthcare, which management estimates could add over US$15b of addressable market and support future revenue and earnings growth.
Further monetisation of Experian’s large proprietary data assets, including more than 250m U.S. consumers with 3.1b trade lines and AtData’s 10b email addresses with 125b monthly activity signals, gives the company scope to deepen client usage of cloud-native platforms like Ascend and lift revenue per customer while supporting margins through scalable analytics.
See why 31 investors see Experian as 18% undervalued.
Result: Fair Value of £36.77 (UNDERVALUED)
Still, this Experian narrative only holds if U.S. mortgage rule changes and the roll off of North America data breach contracts do not have a greater impact than expected.
Find out about the key risks to this Experian narrative.
Another view on Experian valuation
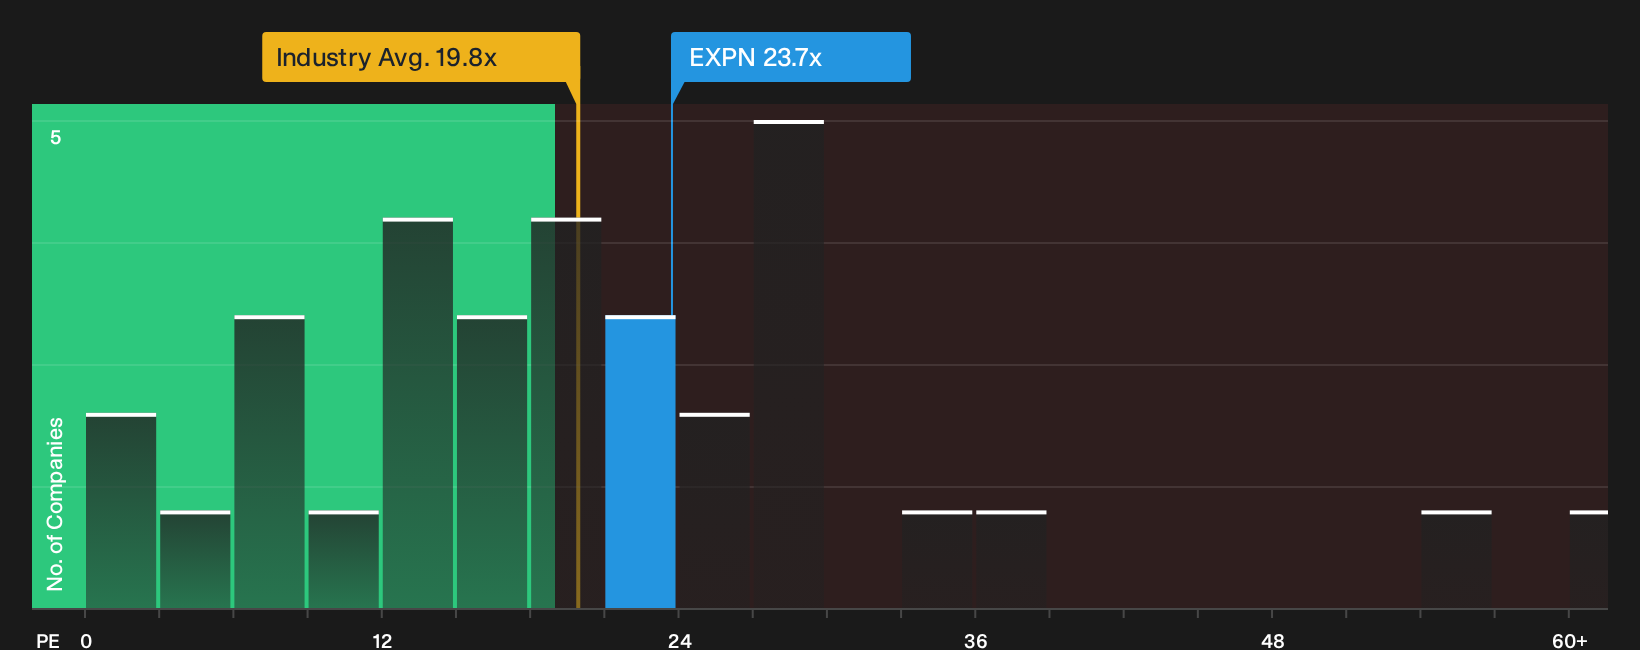
On simple earnings multiples, Experian looks expensive. The shares trade on a P/E of 23.7x, above both UK Professional Services at 19.8x and direct peers at 20.9x. This points to less margin for error if growth or margins come in softer than expected.
Yet the estimated fair ratio for Experian is 32.7x, meaning the current P/E sits well below where the market could move if confidence in its AI and healthcare earnings profile builds. Which lens do you trust more when the multiple already prices in a quality premium, but not the full fair ratio?
For a cleaner read on what the current P/E gap might mean in practice, and how that compares across sectors and competitors, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Experian so far. Momentum, AI exposure and valuation debates are all live. This is exactly why you should pull up the numbers yourself, sanity check the bullish and cautious angles, then weigh the 3 key rewards and 1 important warning sign.
Looking for more Experian sized ideas?
If Experian has sharpened your appetite for high conviction opportunities, do not stop here. Broaden your watchlist now or risk missing the next move.
- Target potential value plays early by reviewing the 13 high quality undervalued stocks that combine solid fundamentals with pricing that the market may not fully recognise yet.
- Prioritise resilience by scanning a list of solid balance sheet and fundamentals (10 results) so you can focus on businesses with financial footing that can better handle shocks.
- Unearth overlooked opportunities by checking out 5 high quality undiscovered gems that pair quality metrics with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com