


- Universal Technical Institute has been expanding campuses and updating hands-on programs in transportation, skilled trades and healthcare to align training capacity with employer demand for workers who can operate alongside AI and automation.
- The push into more locations and programs suggests UTI is prioritizing long-run operating scale, even though higher upfront campus and program launch costs can weigh on near term financial metrics.
- The focus now is on how Universal Technical Institute's expansion of campuses and programs might reshape the broader investment narrative.
Scan beyond Universal Technical Institute and compare its expansion story with hand-picked training and automation plays using the 19 high quality undiscovered gems.
Universal Technical Institute Investment Narrative Recap
To own Universal Technical Institute, you need to believe the expansion in trades and healthcare education can support stronger enrollment and better campus utilization over time. The most important near term swing factor is still execution on converting inquiries into starts, especially in the high school auto and diesel funnel where conversion issues have already shown up.
The biggest immediate risk is that heavy growth spending, including high capex and shorter, slightly less profitable programs, continues to pressure margins and free cash flow without clear payback. The latest campus and program expansion news reinforces this risk profile rather than changing it in a material way.
The most relevant backdrop for this update is the lifted growth restrictions at Concorde Career Colleges. This opened the door for new campuses in Houston, Atlanta and the Phoenix area. Those sites are planned to serve roughly 600 students each, which ties directly into the broader story of Universal Technical Institute scaling physical capacity.
For you as an investor, the operational question is whether these Concorde additions move quickly enough toward mature enrollment to offset mix pressure from shorter programs and rising capital needs. Execution on ramping these locations, while integrating them into a unified operating model, sits right beside high school channel conversion as a key near term catalyst and risk checkpoint.
What The Current Universal Technical Institute Forecasts Assume
Universal Technical Institute's narrative projects 2029 revenue of US$1.2b and earnings of US$91.1 million by that same year. Analysts are building this on an assumed 9.5% yearly increase in revenue and an earnings step up of about US$56.8 million from current earnings of US$34.3 million.
Uncover why Universal Technical Institute's fair value indicates a 72% potential upside to its current price, which could narrow quickly.
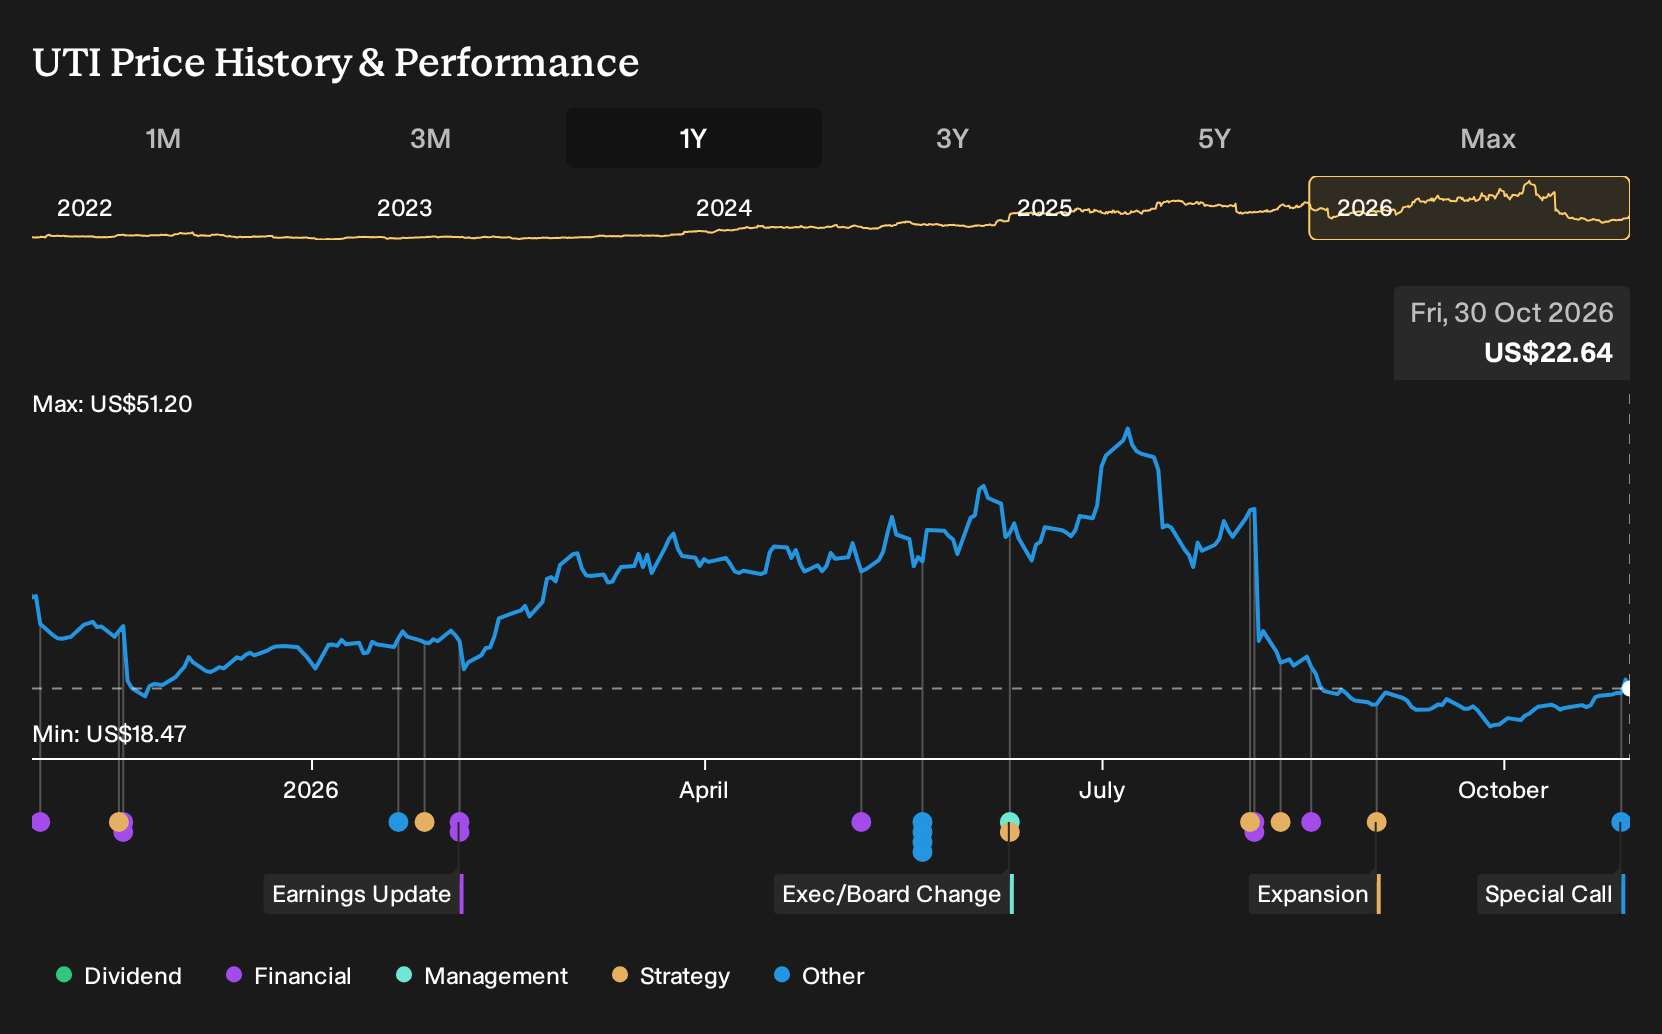
Exploring Other Perspectives
One alternate view on Universal Technical Institute focuses on margin pressure. The lowest analysts were working off 2029 earnings of about US$97.4 million on roughly US$1.2b of revenue, yet still landed on a US$30.0 target. That more cautious story could shift after this expansion news. Compare both sets of assumptions yourself.
Explore another Universal Technical Institute fair value estimate, including one that suggests as much as 7% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Technical Institute research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Technical Institute. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Technical Institute's overall financial health at a glance.
Looking For More Investment Ideas Beyond Universal Technical Institute?
If Universal Technical Institute has put education and automation on your radar, it can be useful to scan a wider field of opportunities using the Simply Wall St Screener so you can compare different risk and reward profiles side by side.
- For investors who want potential upside but still care about fundamentals, you could start with a curated set of 19 high quality undiscovered gems that pair quality with less crowded coverage.
- If resilience matters more than excitement right now, narrow your search to a 29 resilient stocks with low risk scores that focuses on businesses with more measured risk scores.
- When balance sheet strength is non negotiable, filter for companies through a list of solid balance sheet and fundamentals (24 results) so you are only comparing stocks backed by sturdier finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com