


Rivian (RIVN) stock has been a big disappointment for shareholders in 2026, but patient investors should treat its year-to-date weakness as a buying opportunity, according to UBS analyst Joseph Spak. He upgraded the electric vehicle (EV) specialist this morning to “Buy” and announced a $17 price target, indicating potential upside of nearly 28% from current levels.
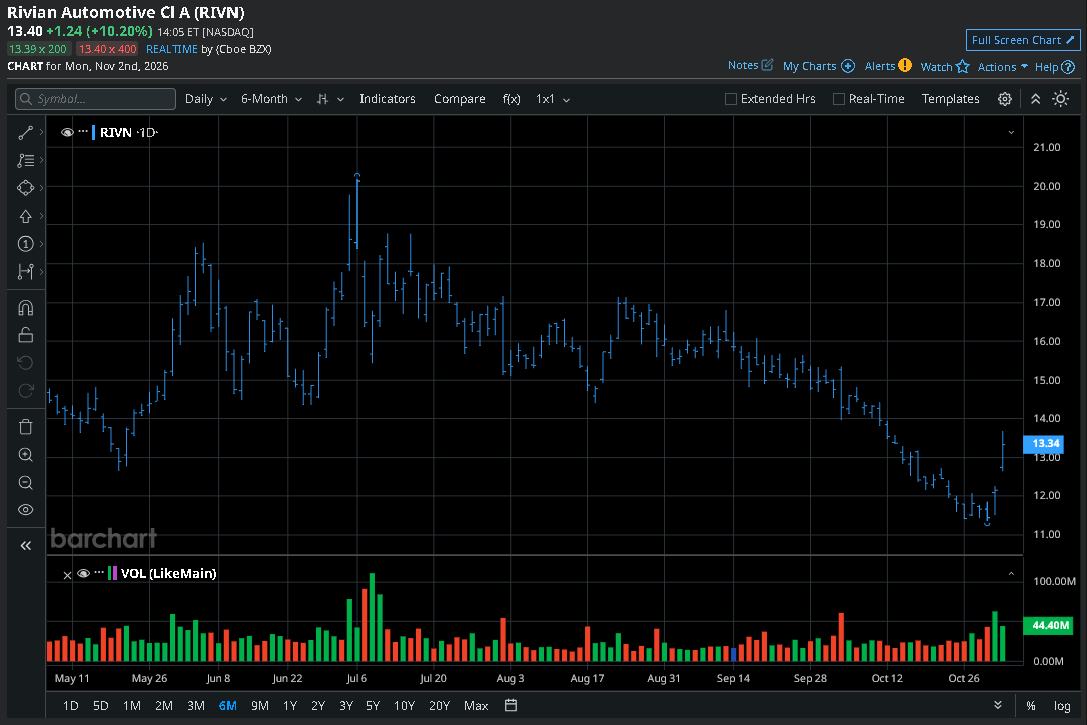
Rivian shares are currently hovering around $13, down about 33% versus the start of this year.
What Made UBS Upgrade Rivian Stock?
Spak recommends owning RIVN shares primarily because “initial R2 demand looks solid, which bodes well for when more trim levels come out.”
According to the UBS analyst, the affordable mass-market SUV will improve Rivian’s auto gross margins, which he believes will be positive by the end of this year.
Part of his bullish view is also due to the company's valuation. At a price-to-sales (P/S) multiple of about 3x, the EV stock is trading at a notable discount compared not only to peers but also to its own historical averages, Spak told clients.
Q3 Earnings Warrant Buying RIVN Shares
In his research note, Spak attributed his positive stance on Rivian stock to the company’s software and services division as well. These verticals offer higher margins and are poised to accelerate growth moving forward. That segment generated about $256 million in gross profit in Q3 at a remarkable 42% margin.
Last week, RIVN came in ahead of Street estimates for its third fiscal quarter and raised its full-year vehicle deliveries guidance to between 67,000 and 70,000.
Even from a technical perspective, the EV stock ripped through its 20-day moving average (MA) on Nov. 2, indicating bulls have taken back control of the near term.
Wall Street Remains Bullish on Rivian Automotive
Interestingly, UBS is still among the more conservative Wall Street firms on Rivian Automotive.
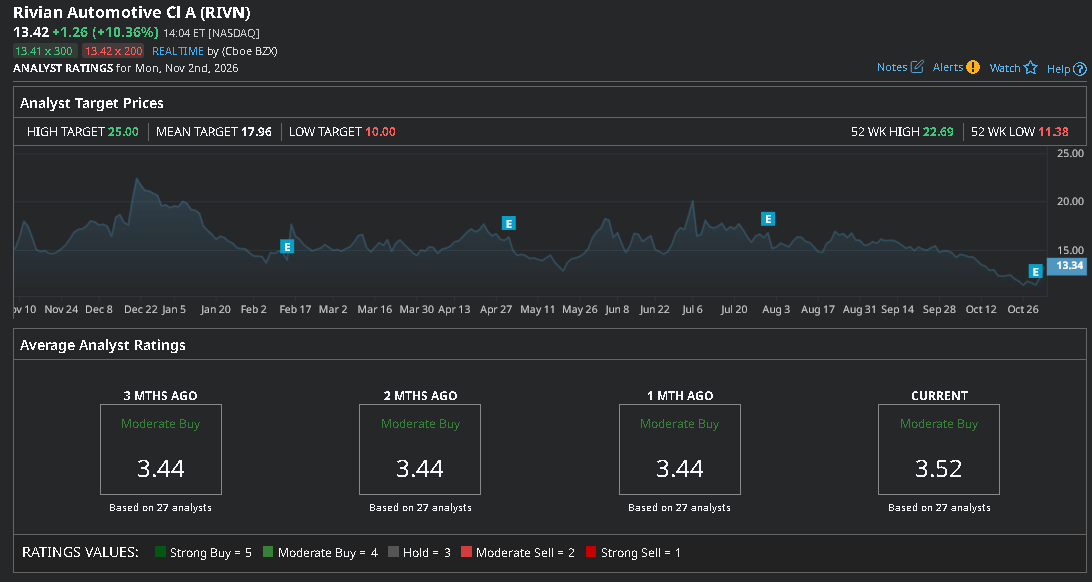
The consensus rating on RIVN stock sits at “Moderate Buy,” with the mean price target of roughly $18 indicating massive upside potential from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.