


Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
So should PRISM BioLabLTD (TSE:206A) shareholders be worried about its cash burn? For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). Let's start with an examination of the business' cash, relative to its cash burn.
When Might PRISM BioLabLTD Run Out Of Money?
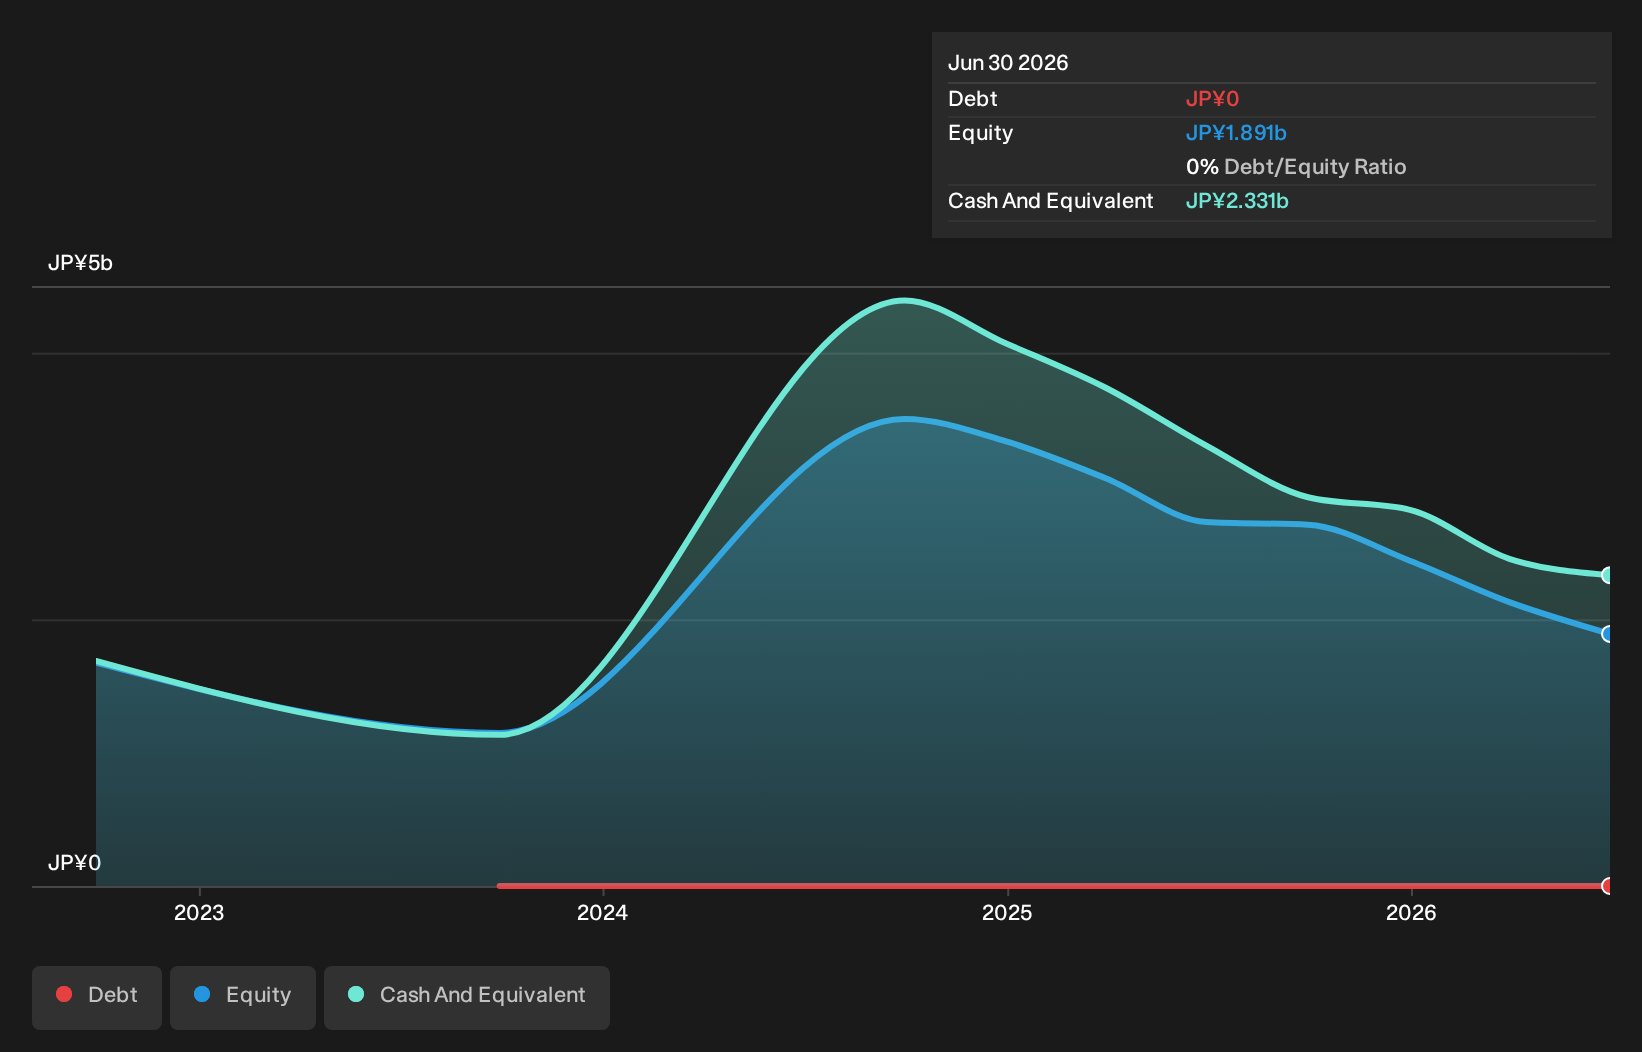
A company's cash runway is calculated by dividing its cash hoard by its cash burn. As at June 2026, PRISM BioLabLTD had cash of JP¥2.3b and no debt. In the last year, its cash burn was JP¥1.3b. Therefore, from June 2026 it had roughly 21 months of cash runway. That's not too bad, but it's fair to say the end of the cash runway is in sight, unless cash burn reduces drastically. The image below shows how its cash balance has been changing over the last few years.
Check out our latest analysis for PRISM BioLabLTD
How Well Is PRISM BioLabLTD Growing?
Over the last year, PRISM BioLabLTD maintained its cash burn at a fairly steady level. But its operating revenue was anything but flat over the year, gaining a full 85%. We think it is growing rather well, upon reflection. Of course, we've only taken a quick look at the stock's growth metrics, here. This graph of historic revenue growth shows how PRISM BioLabLTD is building its business over time.
Can PRISM BioLabLTD Raise More Cash Easily?
Even though it seems like PRISM BioLabLTD is developing its business nicely, we still like to consider how easily it could raise more money to accelerate growth. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
PRISM BioLabLTD's cash burn of JP¥1.3b is about 30% of its JP¥4.4b market capitalisation. That's fairly notable cash burn, so if the company had to sell shares to cover the cost of another year's operations, shareholders would suffer some costly dilution.
How Risky Is PRISM BioLabLTD's Cash Burn Situation?
On this analysis of PRISM BioLabLTD's cash burn, we think its revenue growth was reassuring, while its cash burn relative to its market cap has us a bit worried. While we're the kind of investors who are always a bit concerned about the risks involved with cash burning companies, the metrics we have discussed in this article leave us relatively comfortable about PRISM BioLabLTD's situation. On another note, we conducted an in-depth investigation of the company, and identified 4 warning signs for PRISM BioLabLTD (1 makes us a bit uncomfortable!) that you should be aware of before investing here.
Of course PRISM BioLabLTD may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.