


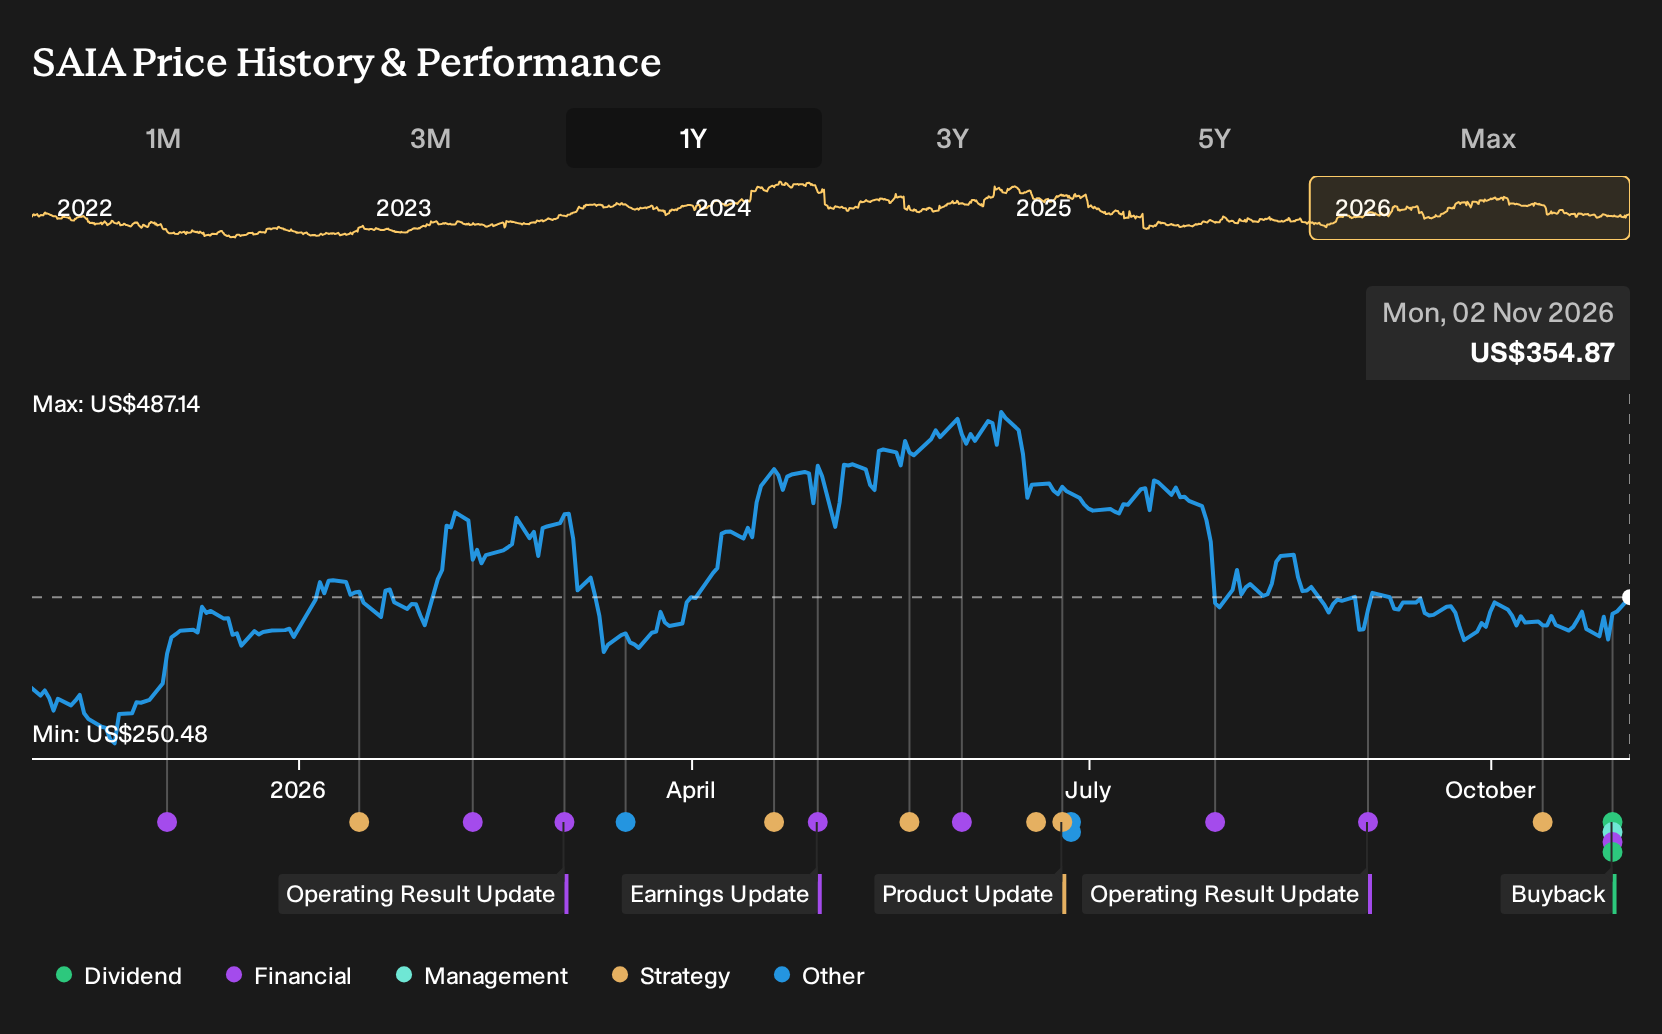
- Saia reported third quarter 2026 sales of US$982.45 million and net income of US$91.45 million, alongside Board approval of a US$250 million open ended share repurchase program and the appointment of Todd C. Fowler to the Board and Audit Committee.
- The combination of higher sales and earnings over the quarter and nine month period and a flexible buyback plan indicates that Saia is committing capital to its own equity while reinforcing board level expertise in transportation technology and capital markets.
- We will now look at how Saia's stronger earnings and new buyback authorization could influence the existing investment narrative.
Saia Investment Narrative Recap
To own Saia, you need to be comfortable with a freight carrier that is leaning on network expansion, technology and service quality to keep pricing and efficiency aligned with a higher cost base. The latest quarter showed higher sales and net income, which helps support that story. The near term swing factor still looks like whether operating ratio progress can offset wage, insurance and fuel pressure.
The biggest risk remains that salaries, benefits, claims costs and fuel stay structurally high while pricing or density gains slow, which would squeeze margins. The fresh results and governance moves do not remove that risk. They mostly give management a bit more financial and operational flexibility if cost pressure persists.
The US$250 million open ended buyback authorization matters most for this news cluster. It intersects directly with the earnings print and the broader question of how Saia balances spending on terminals, technology and safety with returns to shareholders. Because the program has no expiry, execution speed becomes a live variable for investors tracking share count and capital allocation discipline.
For catalysts, this repurchase plan now sits alongside network densification and Saia REV as a key thread to watch. Actual buyback activity relative to free cash generation will signal how confident management is in the current earnings power while still funding wage inflation, higher insurance and fuel costs. If cost lines stay elevated, underutilization of the authorization would be one early warning flag to watch.
What The Saia Forecasts Are Asking You To Underwrite
Analysts looking at Saia are effectively asking you to underwrite a bigger, more profitable freight platform by the late 2020s, with the new buyback authorization sitting on top of that earnings path. The model they are working from assumes revenue grows by 8.8% a year for the next three years while profit margins climb from 8.2% today to 11.7% by year three. That mix of higher sales and fatter margins is what underpins the recent price targets and frames how much room Saia has to keep funding terminals, technology and now repurchases at the same time.
The earnings bridge in those projections is not small. Consensus expects earnings to move from US$278.0 million today to US$510.4 million by 2029, an increase of about US$232 million, with some analysts modeling as much as US$638.2 million. That path leaves Saia on a P/E of 27.9x those 2029 earnings, compared with 32.7x today and roughly 32.8x for the wider US Transportation group based on the report. Anyone using these assumptions is effectively saying Saia grows into its valuation while its earnings multiple drifts lower and the network, including Saia REV, does more of the heavy lifting.
Those same forecasts also build in very modest share count creep, with shares outstanding expected to rise by 0.12% a year over the next three years. The new US$250 million open ended buyback authority pulls in the opposite direction. Actual repurchase activity relative to that small dilutive effect will influence how quickly any future earnings translate into per share figures. If Saia leans into the authorization while delivering on the projected earnings curve, the combination of higher profits and a flatter share count could materially shape the long term per share earnings profile.
Saia's narrative projects US$4.4b revenue and US$510.4 million earnings by 2029. This assumes 8.8% yearly revenue growth and an earnings increase of about US$232 million from US$278.0 million today.
Uncover why Saia's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle puts less weight on Saia’s new buyback and more on margin pressure. The most cautious analysts were only penciling in 7.8% annual revenue growth and about US$472.0 million of earnings by 2029 before this news. That is a tighter, more skeptical story. Use this board appointment and repurchase plan as a prompt to compare those views and decide which narrative you find more convincing.
Explore 4 other Saia fair value estimates, including one that suggests as much as 54% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Saia research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Saia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Saia's overall financial health at a glance.
Looking for more investment ideas beyond Saia?
If Saia has sharpened your thinking on capital allocation, margin pressure and board oversight, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- If capital preservation and steadier ride quality matter most, start with companies that score well on resilience by checking out 29 resilient stocks with low risk scores.
- For investors who care about balance sheet strength and underlying fundamentals before anything else, filter the market using the list of solid balance sheet and fundamentals (24 results).
- If you like the idea of finding lesser known operators before they attract wider attention, run a screen through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com