


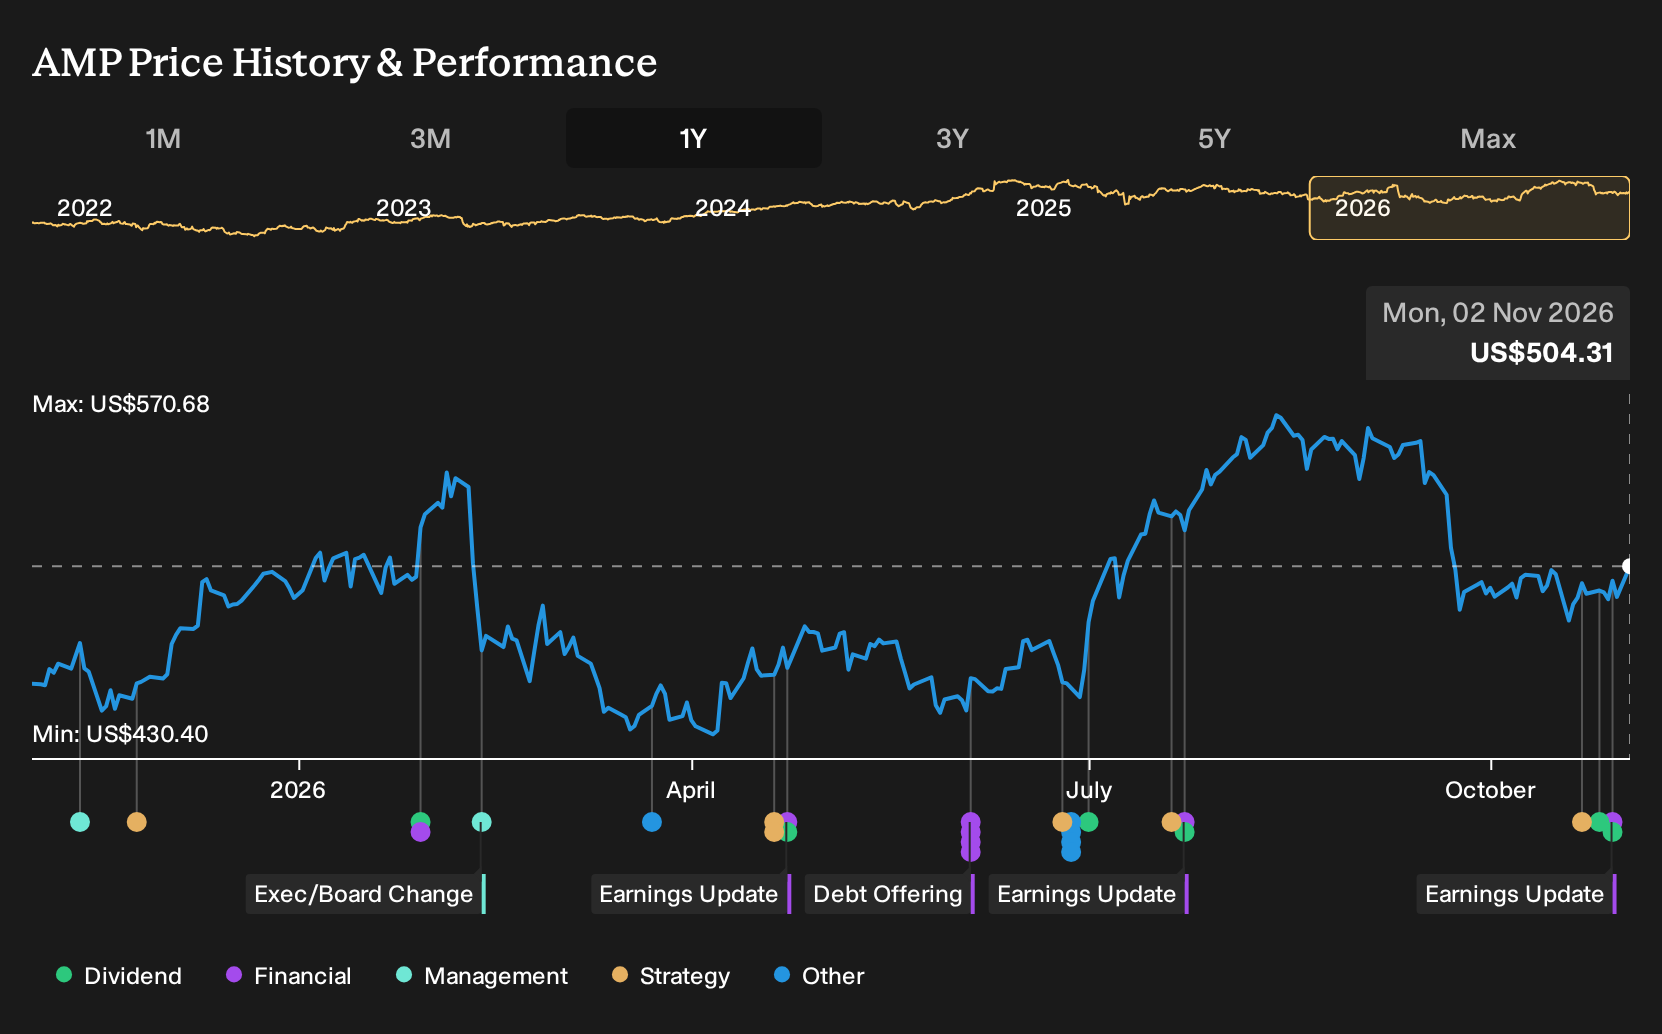
- Ameriprise Financial reported third quarter 2026 results with US$5,191 million in revenue, US$1,126 million in net income and US$12.32 in diluted EPS from continuing operations, alongside a new US$5.5 billion share repurchase authorization running through September 30, 2028.
- The business also continued to focus on advice-led growth, rolling out AI tools, expanding bank partnerships such as AmeriServ, and updating on adviser productivity and flows that sit at the center of its fee-based model.
- Next, attention will be on how Ameriprise Financial's Q3 earnings performance could influence the investment narrative that investors use.
Scan how Ameriprise Financial’s mix of fee-based advice, capital returns and bank partnerships compares by sizing up other wealth and asset managers in our hand-picked list of list of solid balance sheet and fundamentals (24 results).
Ameriprise Financial Investment Narrative Recap
To own Ameriprise Financial, you need to be comfortable with a fee driven advice and asset management model that leans on adviser productivity, client asset retention and disciplined cost control. The Q3 2026 report showed higher revenue and net income alongside strong earnings per share, which keeps the focus on execution in Advice & Wealth Management as the key short term catalyst.
The biggest near term risk remains adviser turnover and any pressure on flows, especially after past asset losses tied to partner relationships and institutional redemptions. Recent margin strength and AI tools help, but they do not fully offset the exposure to a competitive recruiting and retention market if departures accelerate.
The freshly announced US$5.5b share repurchase authorization running through September 30, 2028 is the headline move that ties most clearly to the current story. It extends Ameriprise Financial’s pattern of high capital return, on top of US$4.32b of completed buybacks under the prior program and a regular dividend of US$1.70 per share.
For you as a shareholder, the catalyst is management’s ability to sustain strong earnings and cash generation that support this pace of buybacks while still investing in adviser tools, institutional partnerships such as Huntington and AmeriServ, and asset management capabilities. The risk is that softer flows or higher retention costs eat into the cash pool that funds both reinvestment and repurchases.
Ameriprise Financial’s current analyst script points to revenues of US$22.6b and earnings of US$4.8b by 2029. These figures are built on assumed yearly revenue growth of 4.5% and an earnings increase of about US$0.9b from US$3.9b today.
Uncover why Ameriprise Financial's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts base their thesis on Ameriprise Financial’s adviser productivity story rather than on buybacks alone. Before this Q3 print, they were penciling in about US$23.2b of revenue and US$5.0b of earnings by 2029. You can treat this earnings beat and fresh US$5.5b repurchase plan as a live test of that more upbeat script and explore how your own expectations line up.
Explore 2 other Ameriprise Financial fair value estimates, including one that suggests as much as 109% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ameriprise Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ameriprise Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ameriprise Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ameriprise Financial?
Once you have a view on Ameriprise Financial, it can help to stress test that thesis by lining it up against other opportunities that share similar qualities or offer something very different. The Simply Wall St Screener gives you a way to quickly filter for traits that matter to you, from balance sheet strength to income potential or lower risk profiles.
- If capital preservation and lower volatility are high on your list, you may want to review 29 resilient stocks with low risk scores that combine resilient fundamentals with more measured risk profiles.
- If income is a priority, you could focus on companies in 4 dividend fortresses that pair yields of 5% or more with an emphasis on sustaining payouts.
- If you prefer to hunt for less crowded opportunities, it can be useful to study 19 high quality undiscovered gems where strong financials are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com