


BlackLine’s new French cloud partnership
BlackLine (BL) is in focus after announcing a partnership with S3NS to offer its Agentic Financial Operations Platform on trusted cloud infrastructure in France, with Thales as the first customer.
Recent trading tells a mixed story. BlackLine’s 30-day share price return of 24.37% suggests momentum has picked up in the short term, even though the year-to-date share price return has fallen 36.61% and the 1-year total shareholder return has declined 40.46%.
Scan how BlackLine’s French cloud move compares with other finance and AI-focused platforms by screening for 40 profitable AI stocks that aren't just burning cash that pair real earnings with automation tailwinds.
The recent rebound in BlackLine after steep 1-year and year-to-date declines leaves a wide gap between the current price, analyst targets and intrinsic estimates. Where does a reasonable fair value anchor now sit for this stock?
Most Popular Narrative: 10.5% Undervalued
On the most followed narrative, BlackLine’s fair value sits at $38.10, above the last close of $34.09, which puts the recent rebound in a different light for anyone focused on long term cash flows.
Growing adoption of the Studio360 cloud platform, Verity agents, and the Finance Control Console positions BlackLine as a control and governance layer for AI driven financial operations. This can influence long term revenue growth and support margins as usage deepens across complex customers.
See why 2 investors see BlackLine as 11% undervalued.
Result: Fair Value of $38.10 (UNDERVALUED)
Still, if BlackLine’s longer enterprise sales cycles persist and customer churn in the lower mid market cohort remains elevated, the current undervaluation argument could easily lose traction.
Find out about the key risks to this BlackLine narrative.
Another View: BlackLine looks expensive on earnings
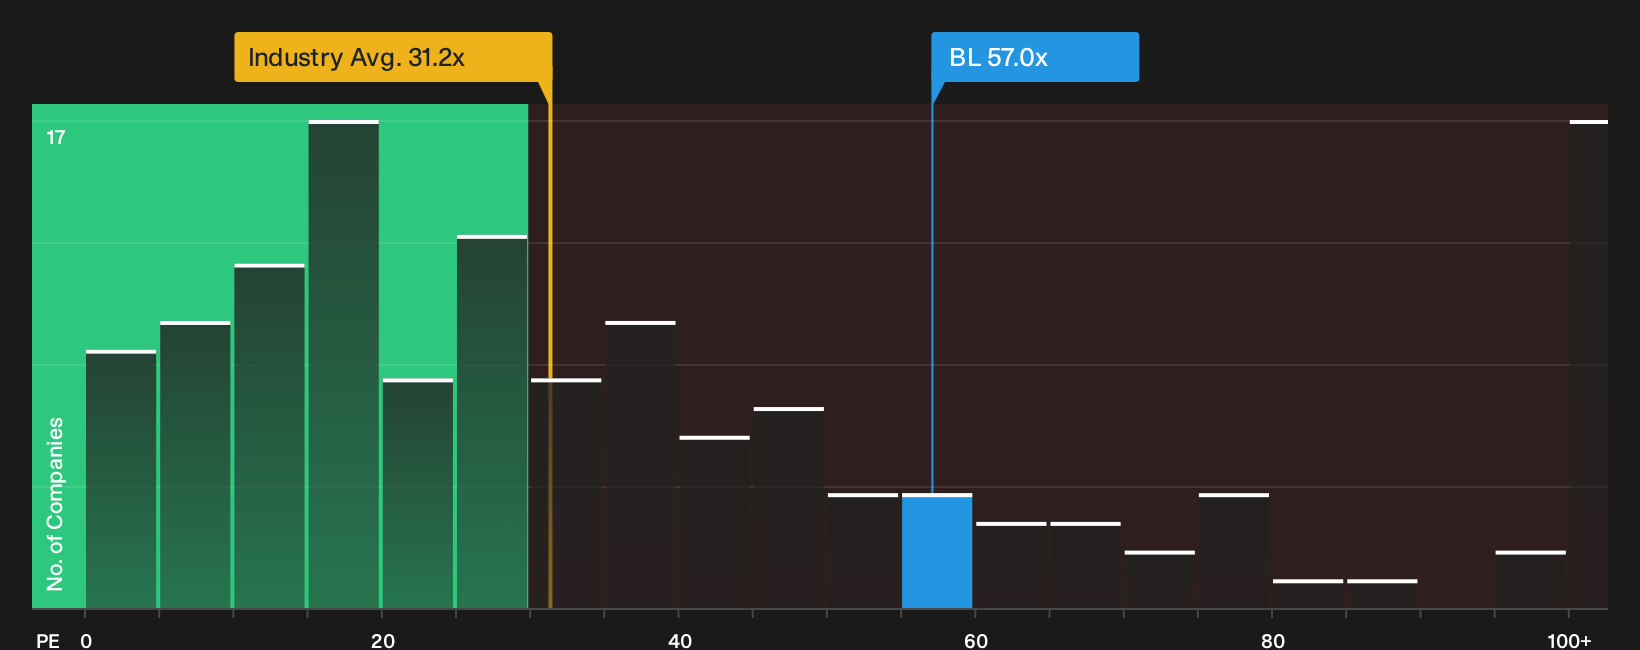
The fair value argument built on long term cash flows clashes with what the P/E multiple is saying. BlackLine trades on about 57x earnings, compared with 31.2x for the US Software group and a fair ratio of 51.2x. That gap points to valuation risk if sentiment cools.
For a closer look at how that earnings multiple stacks up against peers and what it could mean if the market drifts toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on BlackLine’s value story are always interesting, but the real edge comes when you scan the numbers yourself and move fast to frame your own stance. To weigh both the concern around risks and the optimism around potential rewards side by side, start with the 2 key rewards and 2 important warning signs.
Looking for more BlackLine-sized opportunities?
Do not stop with BlackLine. Broaden your watchlist with focused stock ideas so you are not relying on a single story to shape your portfolio.
- Target resilient returns by filtering for companies with sturdy finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for pricing gaps where quality outpaces expectations by scanning the 33 high quality undervalued stocks.
- Lock in potential income streams by zeroing in on dependable high yield payers via the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com