


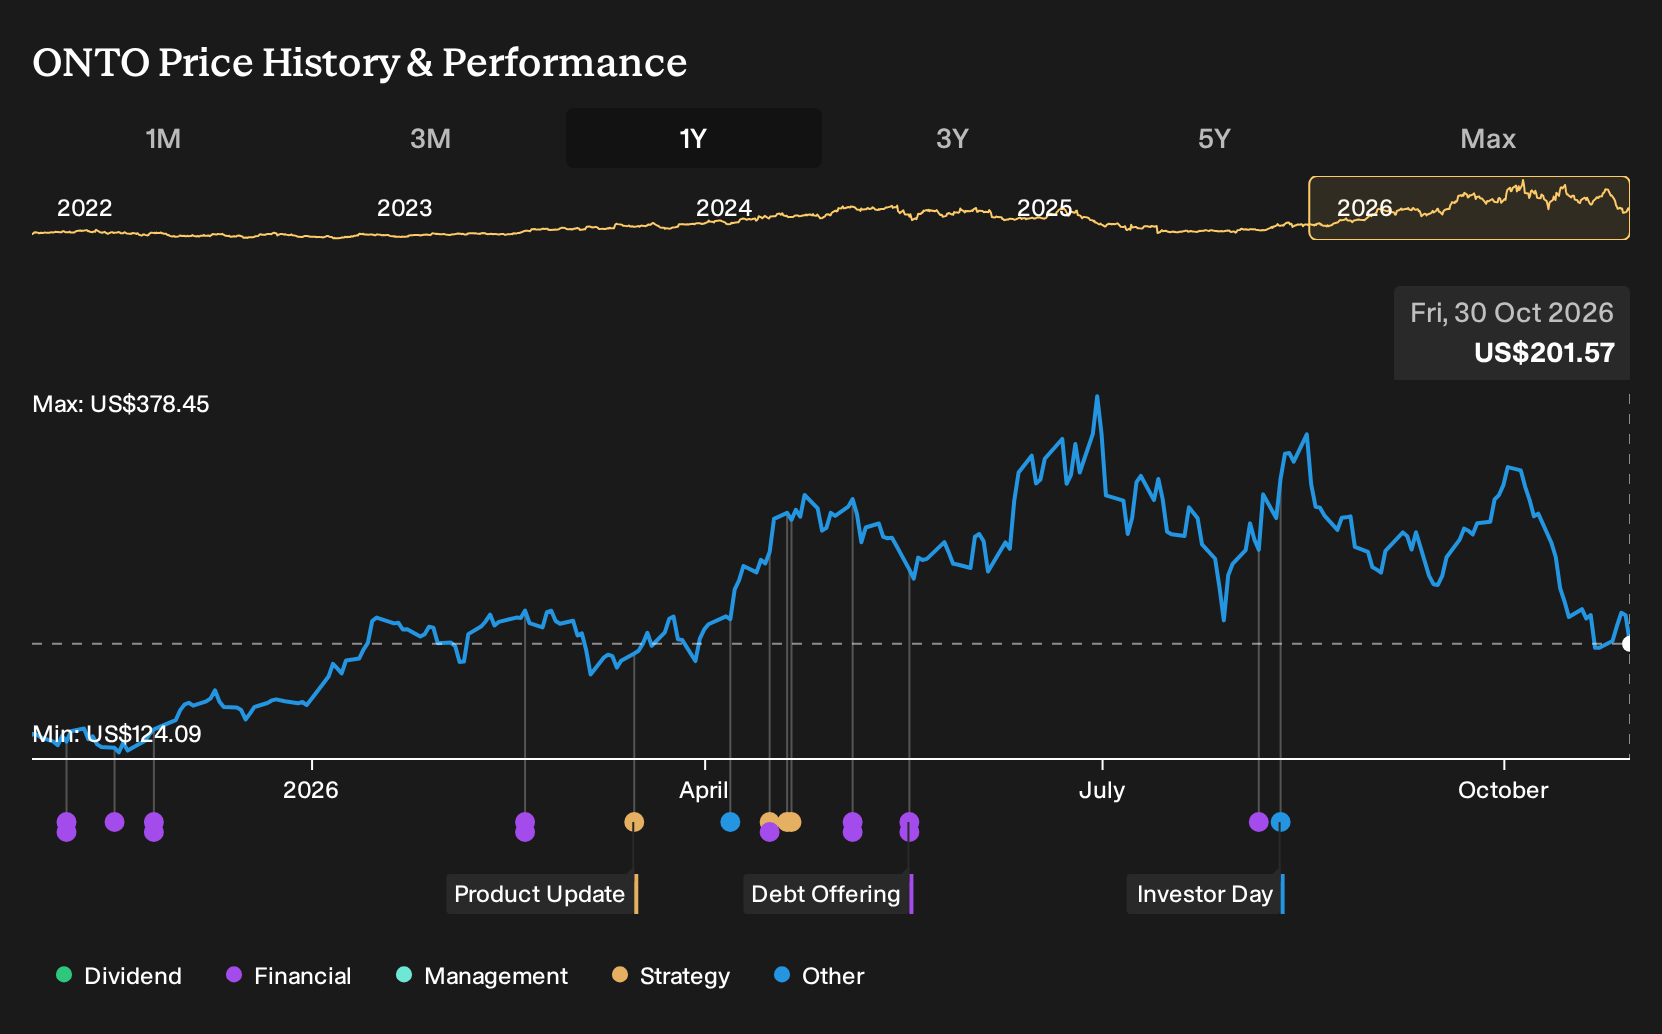
If Onto Innovation sat on your watchlist instead of in your portfolio, the last twelve months may feel like a missed call. For Onto Innovation shareholders, the return over the past year was 45.3%, including dividends. That outcome now looks easy to link to record earnings updates and the Rigaku X-ray partnership headlines, yet the real question is simpler. Back on 2 November 2025, what confidence in AI-driven advanced packaging demand would have justified owning the business rather than observing it?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
This theme extends beyond Onto Innovation. See which of 53 AI infrastructure stocks may still merit a closer look.
The Two Onto Innovation Stories Investors Had To Choose Between
The shares cost US$135 at the start, and Onto Innovation sat between two competing stories about where AI packaging and metrology demand might go next.
The bullish narrative pointed to a Fair Value of US$182, based on analyst expectations of 12.6% annual revenue growth and an increase in profit margins from 19.3% to 23.9%, supported by the Semilab deal and wider adoption of the Dragonfly platform.
The bearish view argued for a Fair Value of US$90, emphasizing rising regulatory and localization costs, sharper competition, and heavy customer concentration that could leave earnings exposed if key buyers reduced their spending.
What The Results Changed For The Onto Innovation Thesis
Onto Innovation’s Q2 2026 report showed revenue of US$343.1 million and net income of US$60.1 million, both above Q2 2025, with net margin rising from 13.4% to 17.5%. That shift in profitability supported the optimistic case that higher-margin tools could matter. At the same time, repeated references to potential overvaluation in later coverage pointed back to the cautious case on pricing. Overall, the evidence cut both ways.
The key question here was whether rising AI packaging demand would appear in sustained margin improvement. For any other chip-equipment stock, track revenue, absolute profit and net margin together across at least a couple of years to see whether the story about higher quality sales is reflected in the numbers.
What Onto Innovation's Price Now Builds In
Onto Innovation now trades at US$191, and the selected Narrative’s Fair Value sits above that level rather than below it. That view rests on Onto Innovation being more tied to an AI infrastructure bottleneck than a typical chip-equipment cycle.
The same Narrative argues today’s price still does not fully credit the role of advanced packaging metrology in AI capacity buildouts.
"Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where Onto Innovation’s Demand Echoes
Onto Innovation points you to packaging and inspection. The same buildout needs something else entirely.
Those AI servers only stay useful if they can access huge pools of fast working memory. Another specialist focuses on supplying that capacity across data centers.
Its job is simple to describe. It turns factories and process expertise into dense memory chips and storage devices that keep accelerators busy.
Onto Innovation helps check and connect advanced packages. This other business leans into the parallel need for bandwidth and capacity, which is now treated far less like a commodity.
That argument has a Narrative and a number behind it. → See the company one Narrative values 50% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com