


Readers hoping to buy Sundram Fasteners Limited (NSE:SUNDRMFAST) for its dividend will need to make their move shortly, as the stock is about to trade ex-dividend. The ex-dividend date is commonly two business days before the record date, which is the cut-off date for shareholders to be present on the company's books to be eligible for a dividend payment. The ex-dividend date is an important date to be aware of as any purchase of the stock made on or after this date might mean a late settlement that doesn't show on the record date. Accordingly, Sundram Fasteners investors that purchase the stock on or after the 6th of November will not receive the dividend, which will be paid on the 23rd of November.
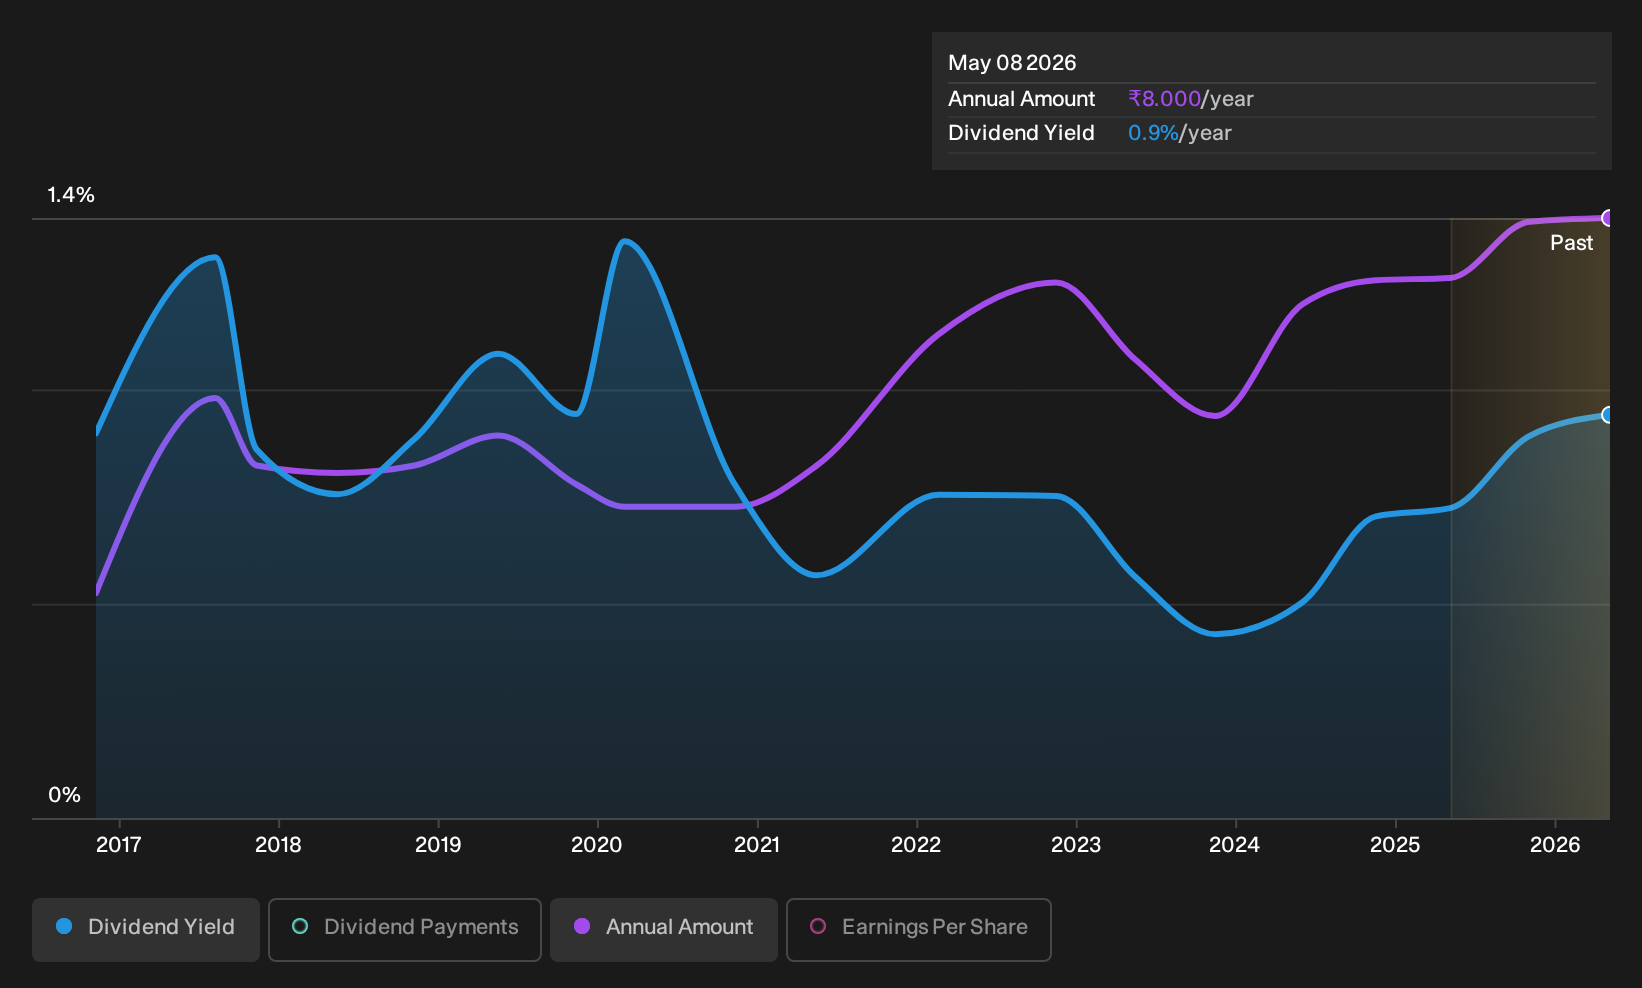
The company's next dividend payment will be ₹4.05 per share, and in the last 12 months, the company paid a total of ₹8.00 per share. Calculating the last year's worth of payments shows that Sundram Fasteners has a trailing yield of 0.7% on the current share price of ₹1078.00. We love seeing companies pay a dividend, but it's also important to be sure that laying the golden eggs isn't going to kill our golden goose! We need to see whether the dividend is covered by earnings and if it's growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. Fortunately Sundram Fasteners's payout ratio is modest, at just 28% of profit. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. Over the past year it paid out 183% of its free cash flow as dividends, which is uncomfortably high. It's hard to consistently pay out more cash than you generate without either borrowing or using company cash, so we'd wonder how the company justifies this payout level.
Sundram Fasteners paid out less in dividends than it reported in profits, but unfortunately it didn't generate enough cash to cover the dividend. Cash is king, as they say, and were Sundram Fasteners to repeatedly pay dividends that aren't well covered by cashflow, we would consider this a warning sign.
View our latest analysis for Sundram Fasteners
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Stocks in companies that generate sustainable earnings growth often make the best dividend prospects, as it is easier to lift the dividend when earnings are rising. Investors love dividends, so if earnings fall and the dividend is reduced, expect a stock to be sold off heavily at the same time. For this reason, we're glad to see Sundram Fasteners's earnings per share have risen 12% per annum over the last five years. Earnings have been growing at a decent rate, but we're concerned dividend payments consumed most of the company's cash flow over the past year.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. In the last 10 years, Sundram Fasteners has lifted its dividend by approximately 14% a year on average. It's great to see earnings per share growing rapidly over several years, and dividends per share growing right along with it.
The Bottom Line
From a dividend perspective, should investors buy or avoid Sundram Fasteners? We're glad to see the company has been improving its earnings per share while also paying out a low percentage of income. However, it's not great to see it paying out what we see as an uncomfortably high percentage of its cash flow. All things considered, we are not particularly enthused about Sundram Fasteners from a dividend perspective.
In light of that, while Sundram Fasteners has an appealing dividend, it's worth knowing the risks involved with this stock. In terms of investment risks, we've identified 1 warning sign with Sundram Fasteners and understanding them should be part of your investment process.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.