


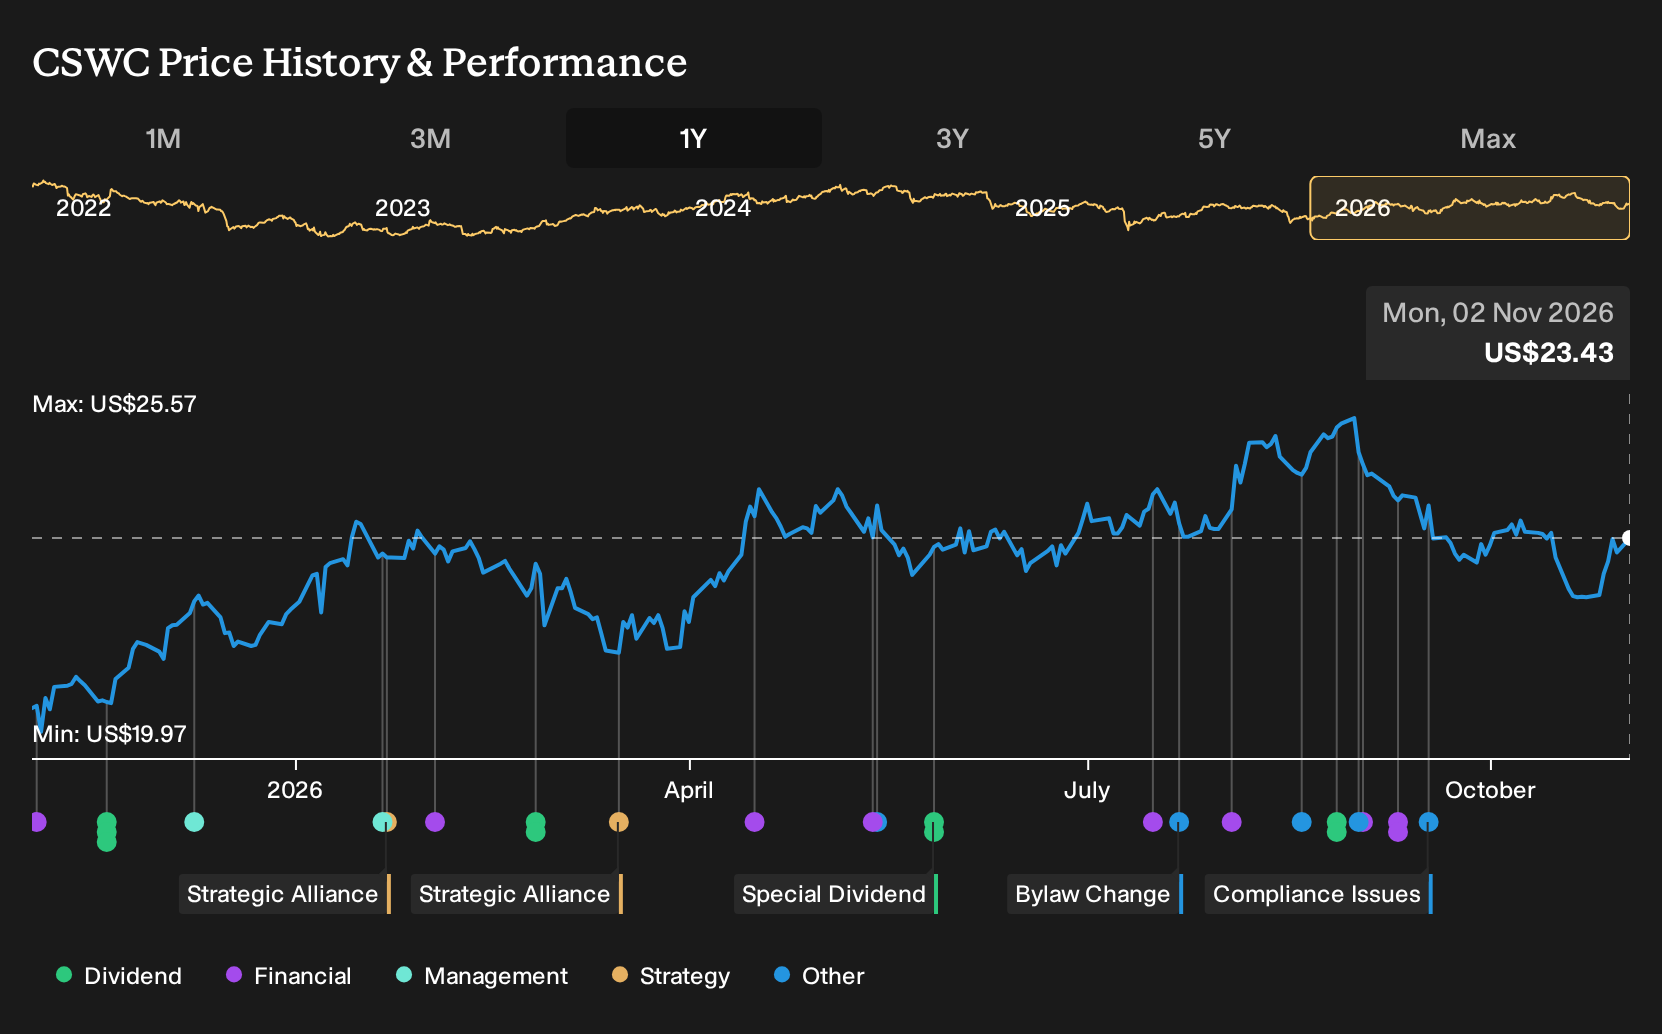
- Capital Southwest reported quarterly revenue of US$67.16 million, ahead of analyst expectations, alongside record originations of roughly US$391 million and declared both regular and supplemental dividends for the coming quarter.
- The business expanded its funding capacity through a US$350 million unsecured bond and increased SBA leverage for its SBIC II vehicle, which supports future deployment without relying solely on equity issuance.
- We will now assess how Capital Southwest’s investment narrative is affected by record quarterly originations and the expanded funding capacity.
Compare Capital Southwest’s record originations and funding firepower with other lenders by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that may benefit from similar demand for credit and disciplined capital structures.
Capital Southwest Investment Narrative Recap
To own Capital Southwest, you need to be comfortable with a lender that focuses on first lien credit to lower middle market borrowers while operating with meaningful leverage and a high dividend load. The key near term swing factor is whether record originations translate into clean credit performance without compressing net interest margins as competition for deals pressures spreads.
The sharpest risk is that interest costs and any credit deterioration reduce earnings coverage of that dividend, especially with net debt around 7x EBITDA and a reliance on higher risk funding. This earnings report, with revenue ahead of expectations but EPS softer, does not significantly change that risk reward balance.
The most notable announcement is the roughly US$391 million of quarterly originations, the largest in Capital Southwest history. That volume is directly tied to the existing catalyst of converting a strong deal pipeline into income producing assets, while relying on conservative first lien underwriting and small average borrower exposure to seek to keep nonaccruals contained.
Record deployment also tests the current strategy. Investors now need to monitor how quickly these new loans season, how they interact with the US$350 million unsecured bond and SBA leverage, and whether portfolio yield and fee income offset higher interest expense. Execution on credit selection and ongoing monitoring remains central to the thesis.
Capital Southwest’s current analyst narrative points to revenues of US$357.6 million and earnings of US$219.3 million by 2029. This aligns with an assumed 14.7% yearly revenue growth rate and implies roughly a doubling of earnings from about US$109.5 million today.
Uncover why Capital Southwest's fair value indicates an 8% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
The Simply Wall St Community currently offers two fair value views on Capital Southwest, ranging from about US$25.30 to just under US$31 a share. Those retail perspectives sit alongside fresh earnings news, including record originations and new unsecured funding. These developments could reshape how you weigh growth potential against credit and dilution risk.
Explore another Capital Southwest fair value estimate, including one that suggests it could be worth just $25.30.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Capital Southwest research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Capital Southwest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital Southwest's overall financial health at a glance.
Looking for more investment ideas beyond Capital Southwest?
Fresh results from Capital Southwest can be a useful anchor, but your next step is to line them up against other opportunities and see which profiles actually fit your portfolio and risk tolerance.
- For investors who want potential upside without ignoring balance sheet strength, start with a 34 high quality undervalued stocks that combine quality fundamentals with pricing that may look appealing.
- If income is your priority instead, focus on consistency and payout sustainability by reviewing a curated 4 dividend fortresses that screen for higher yield with supporting financials.
- When capital preservation sits higher on your checklist, narrow the field to a 29 resilient stocks with low risk scores that emphasize more resilient financial profiles and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com