


- HealthStream reported third quarter 2026 results, with sales of US$83.31 million and net income of US$5.37 million, and nine month revenue of US$248.24 million with net income of US$17.95 million.
- The quarter showed higher revenue than a year earlier but lower quarterly net income, while the nine month period combined higher sales with increased earnings and higher earnings per share.
- We will look at how HealthStream's investment narrative is affected by higher third quarter revenue alongside a softer quarterly profit line.
HealthStream Investment Narrative Recap
To own HealthStream, you need to believe its healthcare workforce software keeps winning budget share as hospitals push for efficiency and compliance. The latest results show higher third quarter and nine month revenue alongside softer quarterly profit. That mix suggests the near term story leans on execution in subscription products rather than margin expansion.
The short term catalyst is whether spending on hStream, CredentialStream, ShiftWizard and career networks translates into steadier earnings without relying on one off items. The main risk is that legacy product declines, higher operating costs and any slower subscription demand combine to pressure margins. The Q3 numbers do not materially change that setup.
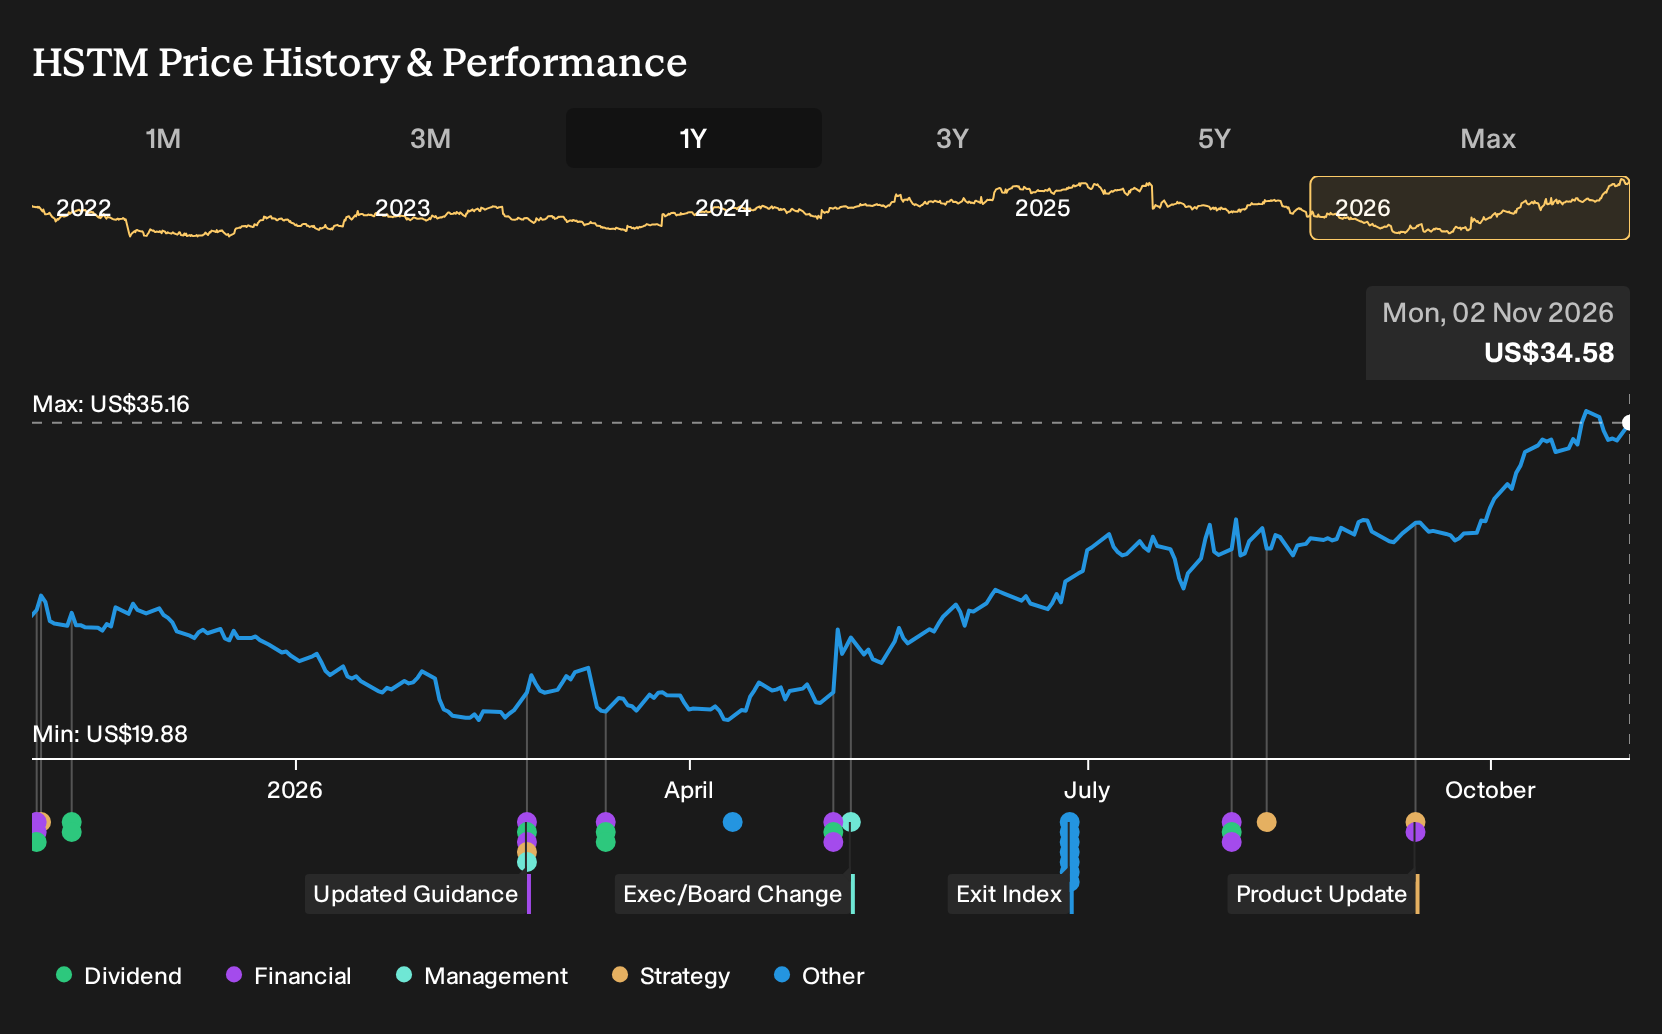
The most relevant announcement is the third quarter and nine month 2026 earnings release on November 2. HealthStream reported Q3 sales of US$83.31 million and net income of US$5.37 million, with basic and diluted EPS from continuing operations at US$0.18, compared with US$0.20 a year earlier.
Across the first nine months, the business reported sales of US$248.24 million and net income of US$17.95 million, with EPS of US$0.61 versus US$0.52 a year ago. For catalysts, those figures help you gauge how growth investments, legacy product runoff and the shift toward newer platforms are flowing through to earnings and where execution risk sits.
What The HealthStream Forecasts Assume
HealthStream's narrative projects US$370.8 million revenue and US$28.7 million earnings by 2029. This implies 4.9% yearly revenue growth and an earnings increase of about US$7.5 million from current earnings of US$21.2 million.
Uncover why HealthStream's fair value is consistent with its current price.
Exploring Other Perspectives
One alternate angle focuses on margin risk rather than revenue growth. The most bearish analysts already plugged in US$374.2 million of 2029 revenue and US$28.4 million of earnings, yet still settled on a lower US$29.0 target. That view treats HealthStream’s higher Q3 sales as fragile and invites you to compare several competing storylines before reacting.
Explore another HealthStream fair value estimate, including one that suggests there may be as much as 8% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your HealthStream research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for HealthStream. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HealthStream's overall financial health at a glance.
Looking for more HealthStream style investment ideas?
If HealthStream's mix of growing revenue and shifting earnings has you thinking about portfolio upgrades, it can help to scan a wider field of opportunities with similar or contrasting profiles.
- For investors who want potential value combined with quality fundamentals, screen for companies that show up in the 34 high quality undervalued stocks and compare how their metrics stack up beside HealthStream.
- If income and resilience matter to you, look at businesses in the 4 dividend fortresses and see which ones pair higher yields with balance sheets you are comfortable holding through different market conditions.
- When capital preservation and steadier risk profiles are the priority, focus on the 29 resilient stocks with low risk scores and check which stocks match your comfort level while still offering exposure to themes you care about.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com