


How the latest earnings and guidance frame SPS Commerce today
SPS Commerce (SPSC) put fresh numbers on the table with third quarter results and new guidance, giving investors updated reference points on sales, profit and expectations for the rest of 2026.
The latest earnings release landed alongside a mixed trading pattern for SPS Commerce. The stock has a 1 day share price return of 2.52% to US$85.08 but is down 6.05% over 7 days, while the 90 day share price return of 14.59% contrasts with a 3.09% gain in 1 year total shareholder return and a 49.43% decline in 3 year total shareholder return. This suggests recent momentum is improving after a difficult multi year stretch as investors reassess both growth potential and risk around the guidance.
Scan other software and data-platform stocks showing similar earnings momentum and guidance trends with the curated 19 high quality undiscovered gems for fresh ideas alongside SPS Commerce.
The recent rebound in SPS Commerce after a steep multi year share price decline divides opinion. Are traders rotating back into software, or does the current valuation now better reflect the earnings profile on show?
Most Popular Narrative: 4% Overvalued
SPS Commerce last closed at $85.08 compared with a widely followed fair value estimate of about $81.55. This frames the current debate around how much earnings execution investors are willing to underwrite.
The current valuation implies investors are paying a premium for SPS Commerce relative to its guided mid single digit consolidated revenue growth and mid 30% EBITDA margins. This is consistent with the narrative that the stock is overvalued.
See why 5 investors see SPS Commerce as 4% overvalued.
Result: Fair Value of $81.55 (OVERVALUED)
Still, two things could upset the overvaluation story: stronger than expected retail program wins and continued heavy free cash flow supporting SPS Commerce buybacks.
Find out about the key risks to this SPS Commerce narrative.
Another View: SWS DCF model paints a very different SPS Commerce picture
The analyst fair value of $81.55 frames SPS Commerce as about 4% overvalued at $85.08. The SWS DCF model points the other way. On that approach, the shares are compared with an estimated future cash flow value of $150.45, which screens as undervalued. When two methods disagree this sharply, which set of assumptions do you trust more: earnings multiples or long term cash flow?
Look into how the SWS DCF model arrives at its fair value.
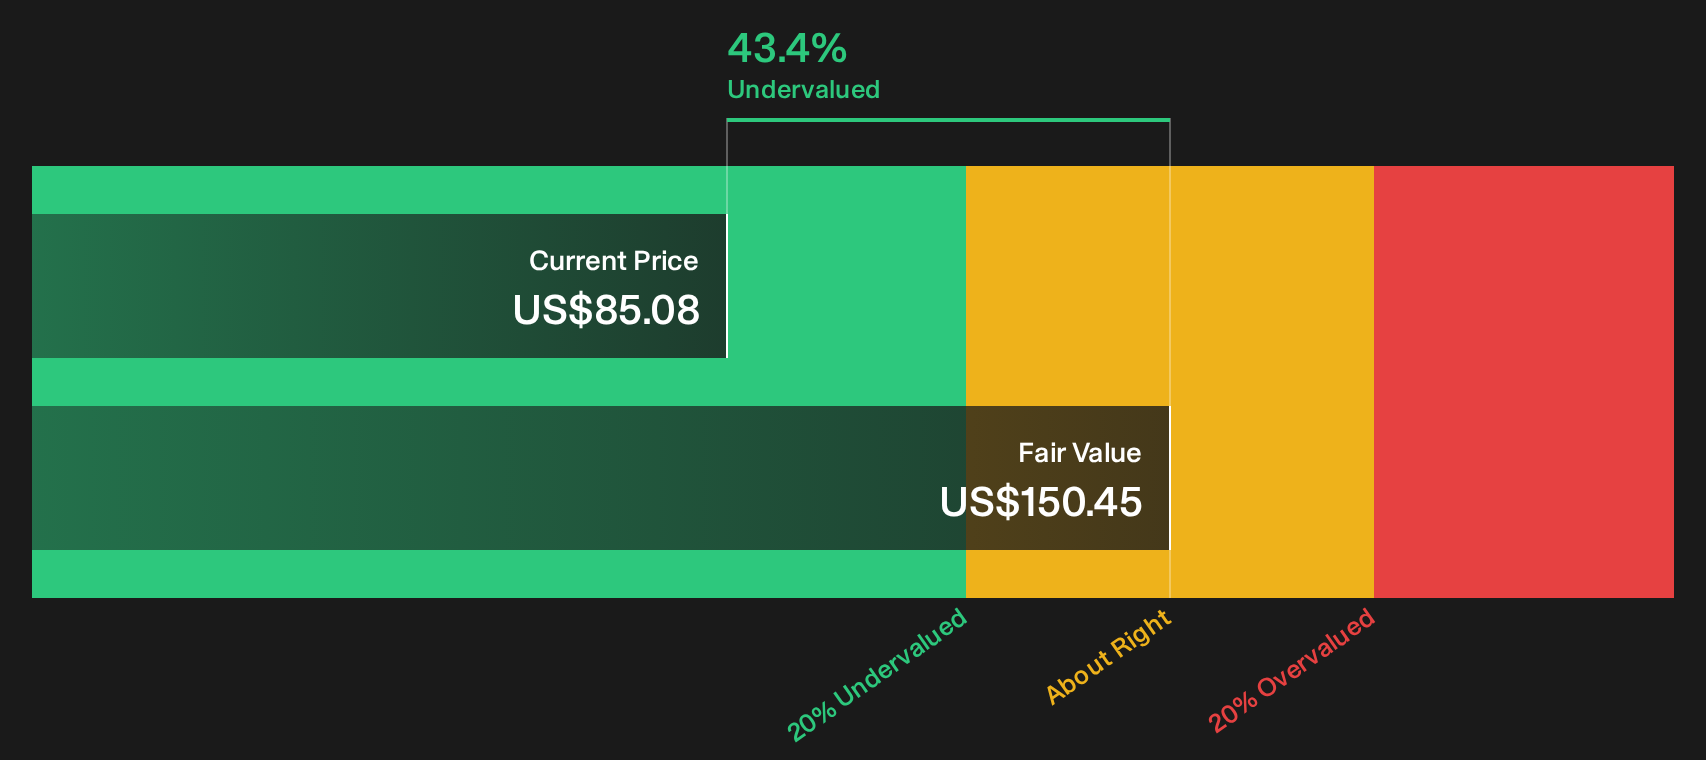
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SPS Commerce for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sceptical after reading through the competing SPS Commerce valuation stories? Act quickly, review the numbers, and weigh the upside that others are pointing to in the 2 key rewards.
Looking for more SPS Commerce sized investment ideas?
Do not stop with SPS Commerce alone. Use the tools available now so you are not looking back in a year wishing you had started sooner.
- Target steadier compounding by scanning a curated pool of resilient companies through the 29 resilient stocks with low risk scores.
- Pursue quality at a discount by filtering for companies that look underpriced relative to their fundamentals using the 34 high quality undervalued stocks.
- Strengthen your core holdings by focusing on balance sheet resilience and underlying business health through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com