


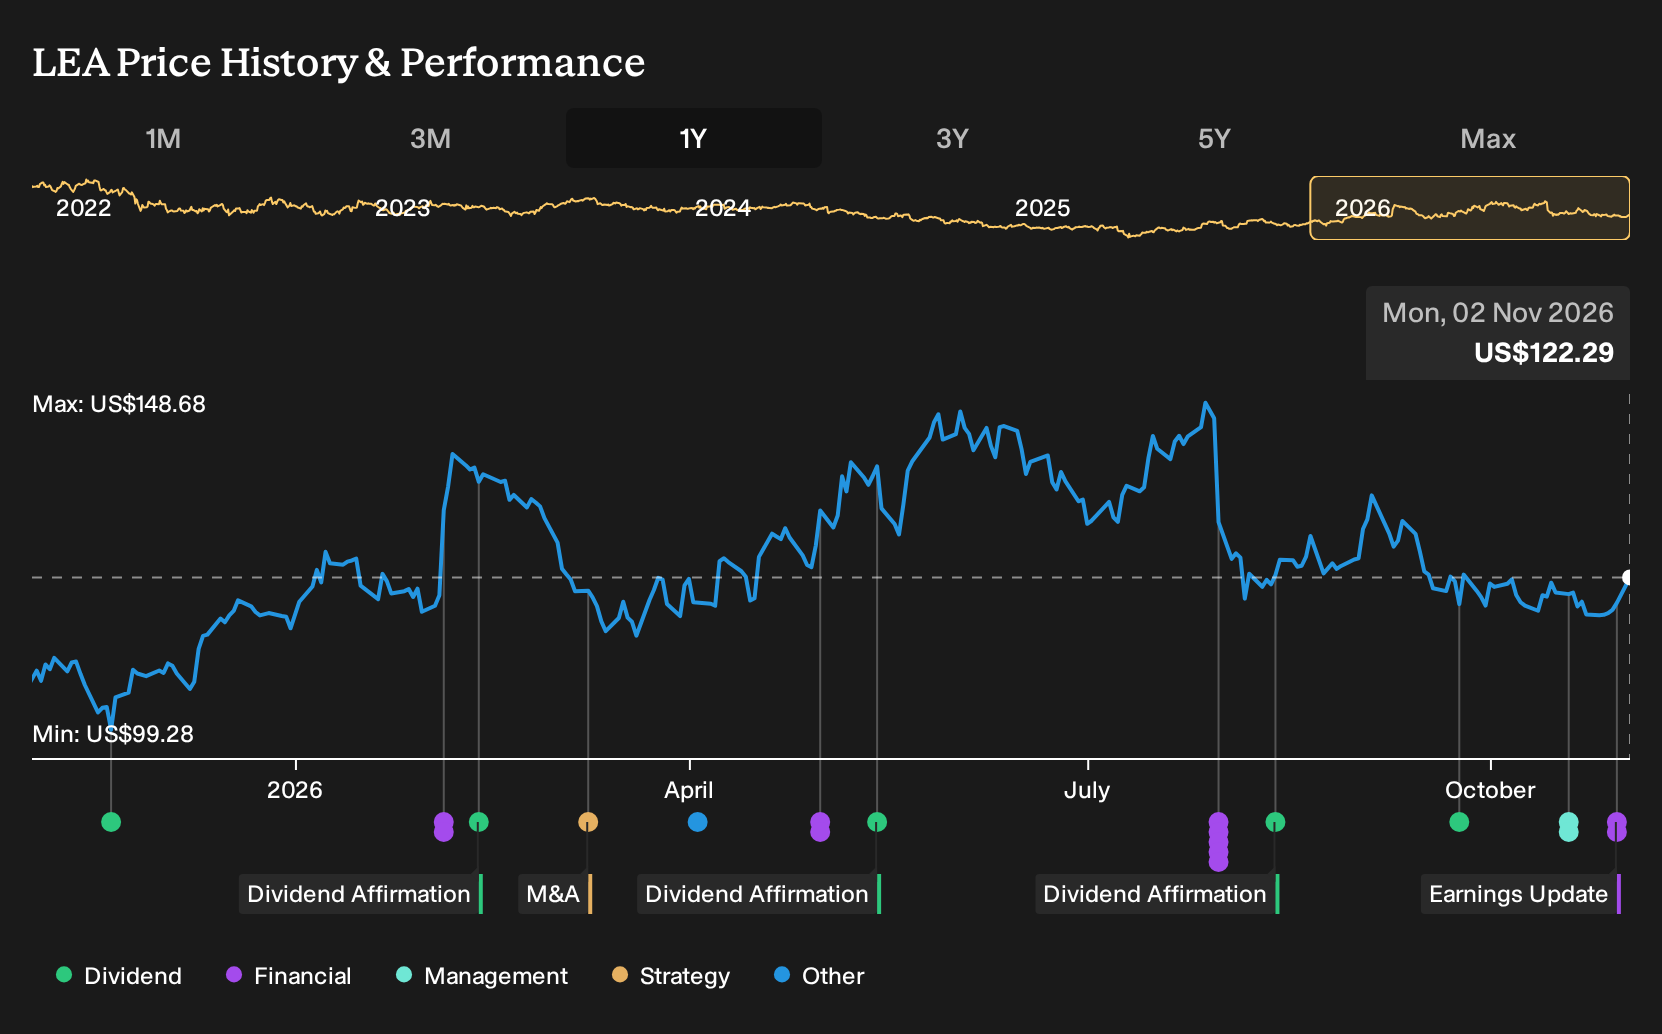
- Lear Corporation reported third quarter 2026 sales of US$5,773 million and net income of US$136.6 million, alongside updated 2026 net sales guidance of US$23,350 million to US$23,750 million, and confirmed stronger basic and diluted earnings per share from continuing operations for both the quarter and year to date.
- The business paired this improved financial picture with a planned CFO transition to Jared Fedele from March 2027, signaling continued focus on global operations and the Asia Pacific region while maintaining continuity through outgoing CFO Jason Cardew in an advisory role.
- The next area of attention is how Lear’s firmer 2026 sales outlook might shape its broader investment narrative and what implications could follow.
Scan how Lear’s latest guidance compares with peers and spot other auto suppliers with similar earnings momentum using the hand-picked 19 high quality undiscovered gems list.
What Is Lear's Investment Narrative?
To own Lear, you need to believe the auto cycle still rewards scale suppliers that can keep big programs on track while holding pricing and capital spending in check. The updated 2026 net sales guidance of US$23,350 million to US$23,750 million supports a view that underlying demand and content per vehicle are holding up for now. Recent EPS strength and earnings growth over the past year point to decent execution, even with a large one off loss in the last 12 months.
The near term story hinges on whether Lear can keep margins steady in a capital intensive, contract heavy business while funding E Systems and seating content without stretching the balance sheet. The upcoming CFO change to Jared Fedele matters here because capital allocation discipline and handling higher risk funding sources sit at the center of the equity case.
Even so, there is a less comfortable angle to Lear’s story that starts with its earnings quality and then runs straight into …
There's only one way to know the right time to buy, sell or hold Lear. Head to Simply Wall St's company report for the latest analysis of Lear's Fair Value.
Exploring Other Perspectives
Some of the lowest ranked analysts frame Lear as a margin risk story. They were assuming roughly flat revenue around US$24.3b by 2029 and earnings of about US$760.6 million. That view looks more cautious than the latest guidance, so you may see those forecasts and opinions shift as new information is absorbed.
Explore 5 other Lear fair value estimates, including one that suggests as much as 10% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lear research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lear. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lear's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lear?
If Lear has sharpened your interest in auto suppliers and you want to keep building out a watchlist, the Simply Wall St Screener is a quick way to surface other companies with traits that fit your style. Use it to test different angles, compare fundamentals, and steadily grow a list of stocks that deserve a closer look, rather than relying on headlines alone.
- For investors who want quality at a discount, start with companies that combine solid fundamentals with attractive pricing through the 34 high quality undervalued stocks.
- If capital preservation matters most to you, focus on businesses with steadier profiles and lower risk scores by checking the 29 resilient stocks with low risk scores.
- When you care about financial resilience and cleaner balance sheets, filter for companies with stronger assets and manageable debt using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com