


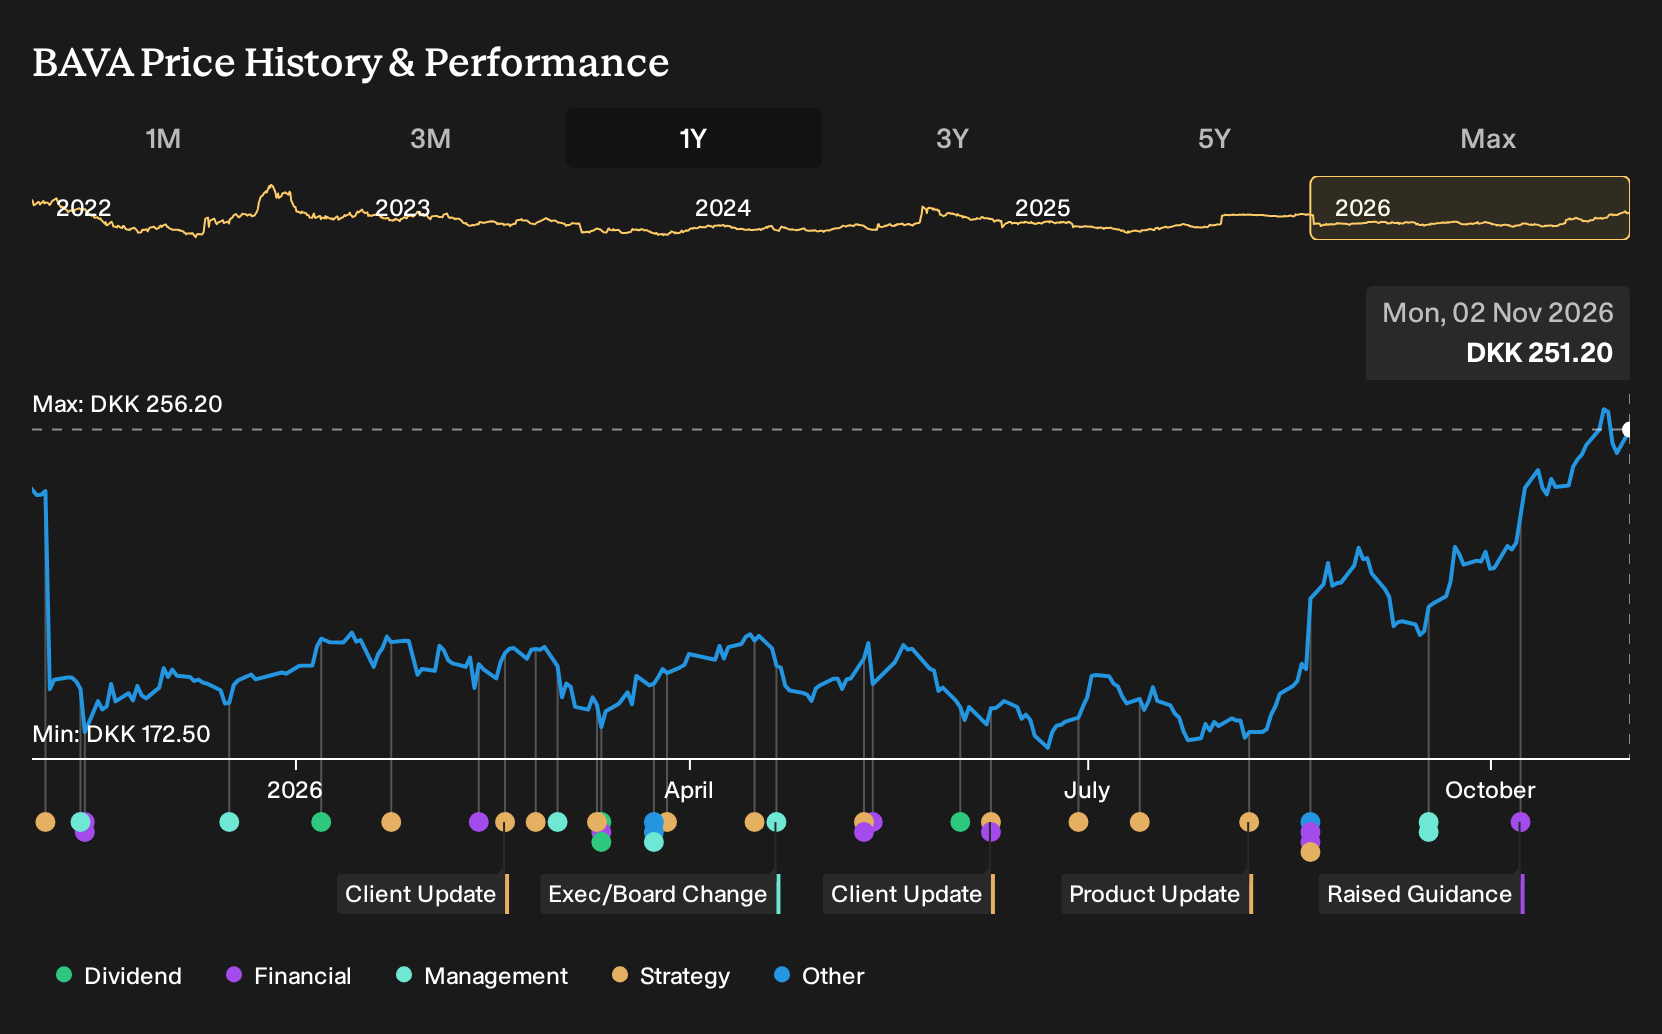
- Bavarian Nordic has completed the first DKK 250 million tranche of its share buy-back program, bringing treasury holdings to 4,664,037 shares, or 5.88% of share capital. Management intends to use these shares for potential future share cancellation.
- The new four year MVA BN vaccine contract with the UK Government adds multi year visibility to Bavarian Nordic's Public Preparedness franchise and may influence how investors think about recurring demand for its smallpox and mpox platform.
- We will now explore how Bavarian Nordic's UK vaccine contract could reshape the investment narrative around recurring public preparedness revenue.
Scan how Bavarian Nordic's latest buy-back and vaccine contract compare with other potential opportunities by reviewing a curated list of 193 high quality undervalued stocks.
Bavarian Nordic Investment Narrative Recap
To own Bavarian Nordic, you need to believe the vaccine portfolio can keep generating solid cash flows while the chikungunya launch, SAP platform programs and MVA cell line work absorb capital and management attention. The short term swing factor still sits in execution across Travel Health and Public Preparedness, not in this single UK announcement or the buy back.
The biggest risk near term remains softer than planned chikungunya demand or further timing slips in Lyme and EBV that keep earnings more dependent on the existing portfolio while consensus already expects earnings to decline. The UK contract and completed DKK 250m repurchase look supportive but do not fundamentally change that risk balance.
The four year MVA BN supply deal with the UK Government is the clearest operational tie in to the current story. It fits the existing catalyst that Public Preparedness could become a recurring DKK about 2.5b business in 2026, backed by multi year orders already above DKK 2.3b. It also adds another data point to that revenue visibility argument.
For catalysts, this matters because recurring vaccine demand and the planned MVA BN cell line transition both depend on long term government partnerships. The UK contract reinforces that Bavarian Nordic remains a key supplier for smallpox and mpox preparedness. At the same time, investors still need to watch chikungunya uptake, SAP timelines and how much pipeline spend is required to maintain at least a 25% EBITDA margin.
Bavarian Nordic's current consensus narrative aligns around revenues of DKK 6.2 billion and earnings of DKK 1.0 billion by 2029, compared with earnings today of DKK 1.5 billion. This implies an earnings decline of DKK 0.5 billion from current levels, while analysts broadly describe revenue as remaining fairly flat over the next 3 years.
Discover how Bavarian Nordic's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view places Bavarian Nordic’s Public Preparedness exposure at the center of the risk story. The most cautious analysts were modeling revenue to decline about 4.7% a year, with earnings moving toward roughly DKK 586.2 million by 2029. That is a far harsher setup than consensus, and it came before this new UK contract and buyback. Use that gap in expectations as a reminder that you are weighing several very different narratives that may shift as fresh contracts and capital moves feed into future forecasts.
Explore 2 other Bavarian Nordic fair value estimates, including one that suggests it could be worth just DKK 276.25.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bavarian Nordic research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bavarian Nordic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bavarian Nordic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bavarian Nordic?
If Bavarian Nordic is only one piece of your watchlist, it can help to line it up against a wider field of contenders and see where the risk, income and quality profiles differ.
- For investors who want income to play a bigger role in returns, review a curated set of higher yielding opportunities through 221 dividend fortresses.
- If capital preservation and steadier fundamentals matter most to you, filter for sturdier balance sheets and resilient businesses using the list of solid balance sheet and fundamentals (197 results).
- When you want potential mispricings that the market may be overlooking, scan across a focused universe of quality stocks that look attractively priced with the 193 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com