


Primaris Real Estate Investment Trust (TSX:PMZ.UN) just released third quarter 2026 results, with sales ahead of last year but net income and diluted earnings per unit from continuing operations moving in the opposite direction.
The mixed third quarter has landed against a share price that has already moved sharply higher, with a year to date share price return of 46.88% and a 1 year total shareholder return of 57.09% that reflects both price gains and distributions. Recent momentum looks steadier than spectacular, with a 30 day share price return of 3.12% and a 90 day move of 0.79% around the latest results. The 3 year total shareholder return of 101.33% signals that long term holders in Primaris Real Estate Investment Trust have so far been rewarded despite the near term earnings pressure.
Compare Primaris Real Estate Investment Trust's momentum and income profile with a hand picked 3 dividend fortresses that also combine meaningful yields with sizeable market capitalizations.
For Primaris Real Estate Investment Trust, a 3 year total shareholder return above 100% sits beside softer recent earnings. This raises a simple question: Is this move tracking fundamentals or just a mood swing in sentiment?
Price-to-Earnings of 25.2x: Is it justified?
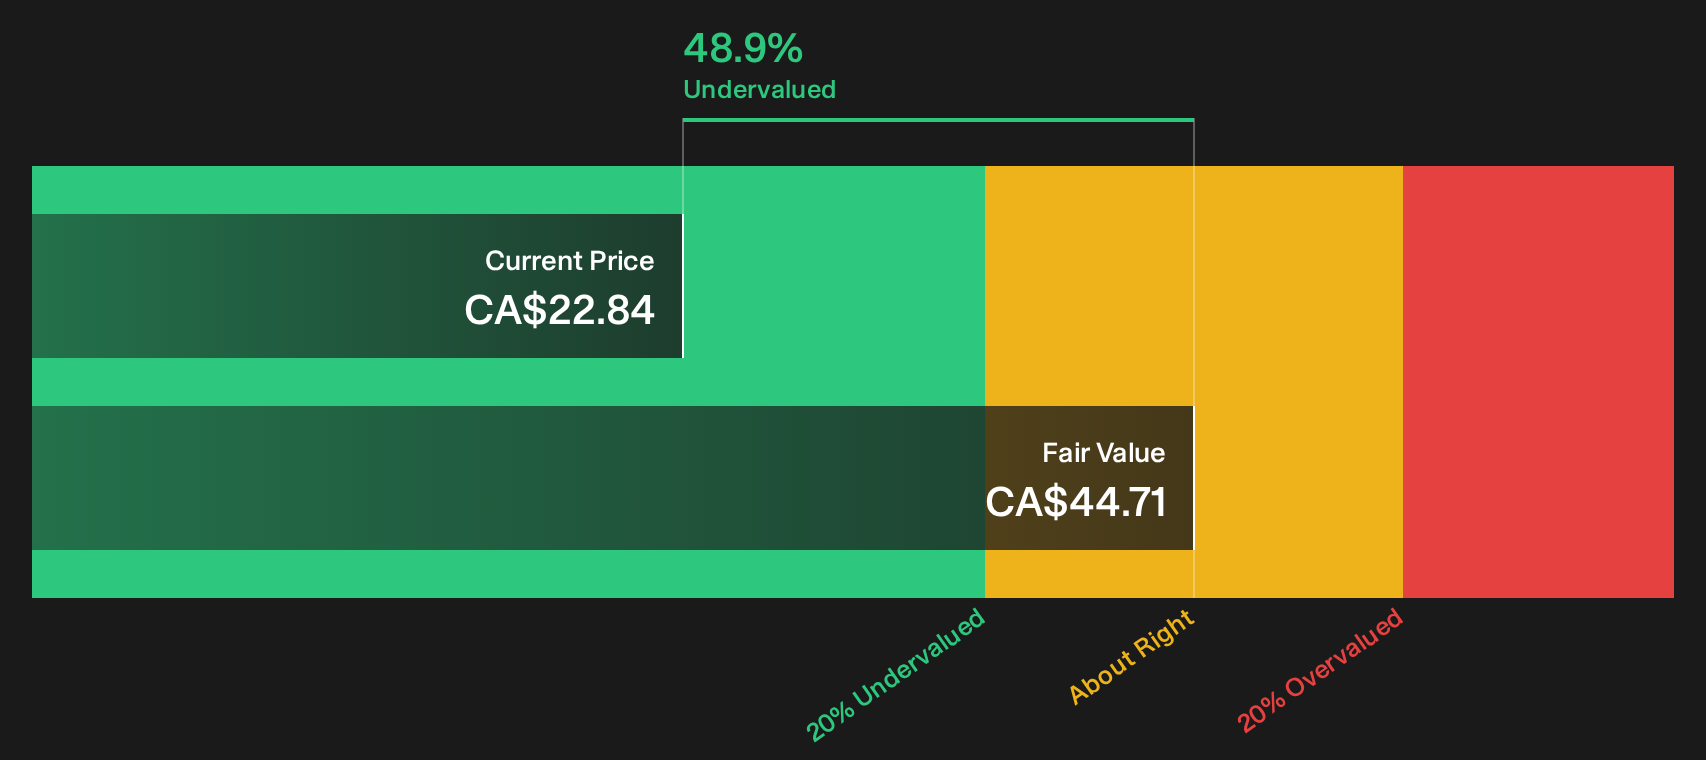
Primaris Real Estate Investment Trust last closed at CA$22.84, and on a P/E of 25.2x it trades at a richer earnings multiple than several reference points, even though the SWS DCF model points to a higher implied value of CA$44.71.
The P/E ratio compares the current unit price with earnings per unit. For a retail focused REIT like Primaris Real Estate Investment Trust, this measure gives a quick sense of how much investors are paying today for each dollar of current profit from its enclosed shopping centre portfolio.
That 25.2x multiple sits above the estimated fair P/E of 18.8x, which suggests the market is paying a premium over the level regression analysis indicates it could move toward over time. It also exceeds both the North American Retail REITs average of 24.1x and the narrower peer group average of 18.3x, which is a clear signal that investors are pricing Primaris Real Estate Investment Trust more highly than comparable retail property trusts on current earnings.
Explore the SWS fair ratio for Primaris Real Estate Investment Trust.
Result: Price-to-Earnings of 25.2x (OVERVALUED)
Still, a rich P/E backed by a 3 year total shareholder return above 100% could unwind quickly if earnings soften further or if enclosed mall valuations reset.
Find out about the key risks to this Primaris Real Estate Investment Trust narrative.
Another View: What the SWS DCF Model Says About Primaris Real Estate Investment Trust
The P/E looks demanding, yet the SWS DCF model tells a very different story. On that cash flow view, Primaris Real Estate Investment Trust at CA$22.84 is assessed against an estimated value of CA$44.71, which implies the units trade at a large discount. If one method flags overpricing while another points to a big gap on the upside, which lens should matter more for you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Primaris Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Primaris Real Estate Investment Trust so far. If you want to move fast and rely on your own judgement, start with the balance of risks and potential upside set out in the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Primaris Real Estate Investment Trust?
Do not stop at Primaris Real Estate Investment Trust if you want a fuller opportunity set, because fresher ideas often appear where fewer people are looking.
- Target potential mispricings by scanning a curated pool of high quality candidates with the 5 high quality undervalued stocks that couple strong fundamentals with appealing valuations.
- Protect your downside by focusing on stability first and performance second through a 9 resilient stocks with low risk scores that emphasizes resilient balance sheets and steadier return profiles.
- Get ahead of the crowd by reviewing a 8 high quality undiscovered gems that highlights underfollowed businesses with solid financial foundations before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com