


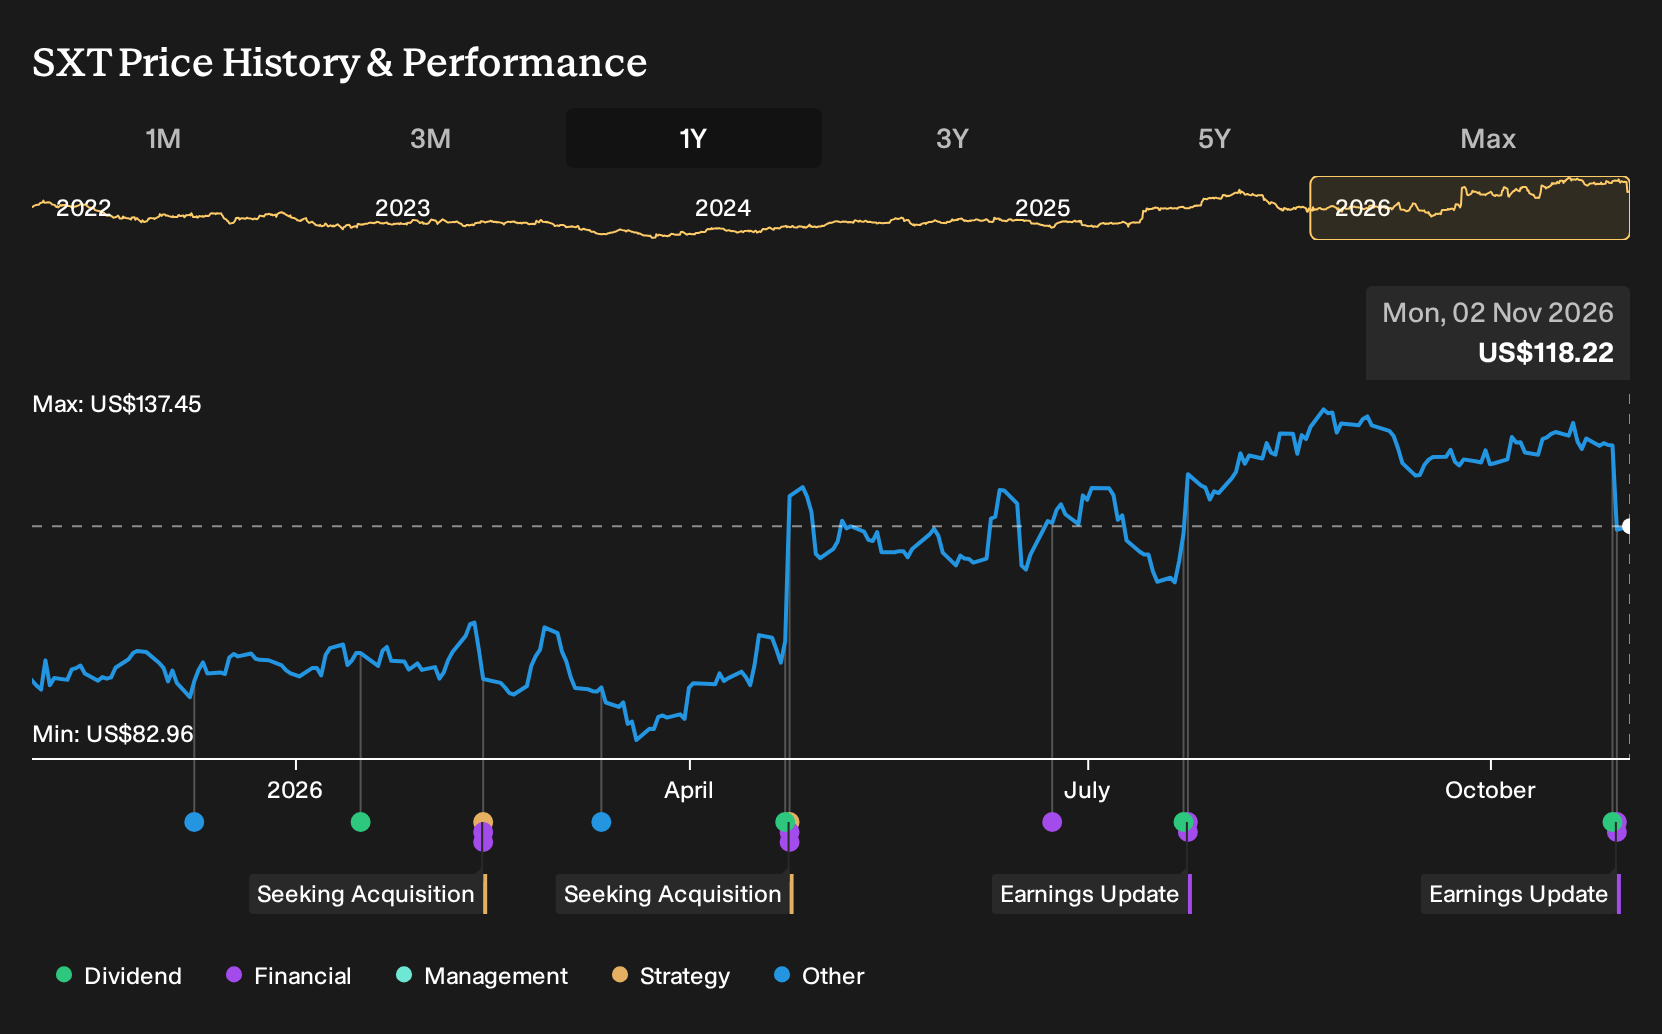
- Sensient Technologies reported third quarter 2026 sales of US$455.84 million and net income of US$48.34 million, with higher basic and diluted EPS from continuing operations than a year earlier, and also reported higher sales and earnings for the first nine months of 2026.
- The company paired these results with a slightly higher full year 2026 diluted EPS guidance range and an affirmed US$0.41 quarterly dividend. This highlights ongoing investment in the business while continuing regular cash returns to shareholders.
- We will now look at how Sensient Technologies' stronger earnings and raised EPS guidance could influence its broader investment narrative.
Sensient Technologies Investment Narrative Recap
To own Sensient Technologies, you need to believe that its push into natural colors and higher value specialty ingredients can keep translating into healthier earnings, without stretching the balance sheet too far. The latest quarterly figures show higher sales and profit versus a year earlier, which supports that narrative but does not remove execution risk around capacity build out or sourcing.
The near term swing factor remains how smoothly Sensient Technologies converts remaining synthetic color revenue ahead of the 2027 to 2028 regulatory deadlines. The biggest operational risk still sits in supply chain and input cost pressure. Any squeeze on agricultural materials or logistics could challenge margins just as capital spending on natural color projects remains heavy.
The raised 2026 diluted EPS guidance to US$4.15 to US$4.20 sits at the center of this earnings story. That revision ties directly to recent momentum in reported sales and net income and gives you a clearer anchor for thinking about near term execution on pricing, mix, and cost control inside Sensient Technologies.
For catalysts, that tighter and slightly higher EPS range matters more than the dividend affirmation, because it links to whether new natural color capacity and specialty ingredients volumes are coming through as planned. If the business tracks toward the top of that guidance band, it would signal that Sensient Technologies is handling raw material costs, logistics complexity, and its heavier capex load in line with current expectations.
Sensient Technologies' current analyst model points to US$2.6b in revenue and US$312.0 million in earnings by 2029, based on an assumed 14.7% yearly revenue growth rate. That implies earnings would need to rise by US$154.0 million from the US$158.0 million reported today to reach the 2029 consensus mark.
Uncover why Sensient Technologies' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on supply chain strain and more on how quickly Sensient Technologies could scale natural color conversions. Before this latest quarter, that bullish group was modelling revenue of about US$2.9b and earnings near US$358.0 million by 2029. Today's stronger earnings and higher 2026 EPS guidance may influence those narratives to shift. This is why it helps to compare several viewpoints before you decide what story you believe.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Sensient Technologies research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sensient Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sensient Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Sensient Technologies?
If you want to stress test your thesis on Sensient Technologies and compare it with other opportunities, the Simply Wall St Screener gives you a way to scan for businesses that match the kind of balance sheet strength, income profile, or risk level you prefer.
- If capital preservation sits high on your list, start with a group of 29 resilient stocks with low risk scores that pair resilience scores with steadier fundamentals.
- If you are hunting for quality that the market may be overlooking, check out a focused 19 high quality undiscovered gems that combines strong financial traits with lower visibility.
- If you care most about financial solidity, filter for companies through a list of solid balance sheet and fundamentals (24 results) to see which businesses carry cleaner leverage and liquidity metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com