


Q3 earnings jump and guidance reset put Twilio in focus
Twilio (TWLO) moved into the spotlight after its 29 October third quarter update, which combined higher reported sales, a sharp increase in net income, and upgraded full year and fourth quarter revenue guidance.
Twilio’s recent earnings beat and guidance reset landed after a choppy stretch for the stock, with a 7 day share price return down 21.3% and a 30 day share price return down 29.5%. However, the year to date share price return is up 50% and the 3 year total shareholder return is around 3x, signalling long term momentum despite near term volatility.
Scan other fast moving AI beneficiaries alongside Twilio using the hand picked 39 AI small caps that are also responding to stronger earnings and guidance upgrades.
After a sharp pullback, and with new guidance and fresh AI enthusiasm now baked into expectations, is the bigger opportunity in Twilio still ahead, or was most of it in the run up to these results?
Most Popular Narrative: 24% Undervalued
At a last close of $207.60 against a most followed fair value estimate of $274.44, Twilio screens as undervalued on that narrative, with the gap hinging on how much earnings power AI use cases can support over time.
Growing adoption of AI-powered communications and automation is fueling incremental demand for Twilio's programmable infrastructure and platform products (e.g., ConversationRelay, conversational intelligence). This is expanding the company's addressable market and driving higher-margin revenue growth, which supports future revenue and net margin expansion.
See why 79 investors see Twilio as 24% undervalued.
Result: Fair Value of $274.44 (UNDERVALUED)
Still, Twilio’s dependence on lower margin messaging and rising competition from large cloud platforms could squeeze profitability and weaken the AI-driven upside case.
Find out about the key risks to this Twilio narrative.
Another View: Twilio on earnings multiples
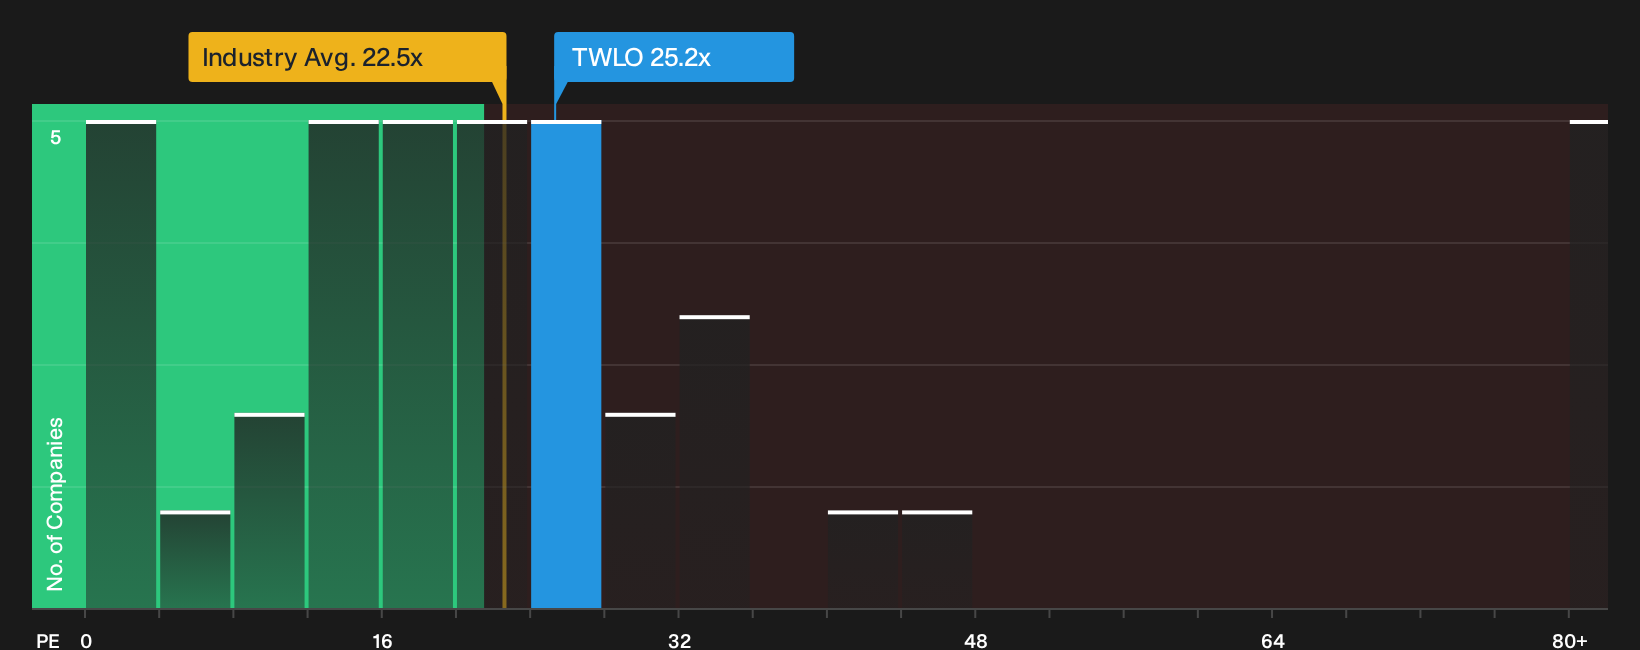
The first narrative leans on a fair value of $274.44 for Twilio, which suggests upside from the current $207.60 share price. On simple earnings multiples though, the picture looks less generous, with TWLO trading on a P/E of 25.2x against a fair ratio of 17.2x and an industry average of 22.5x.
That gap implies investors are already paying a premium for Twilio relative to both the wider US IT sector and the level the fair ratio suggests the market could move towards. The key question is whether the AI and growth story justifies holding that premium, or if the multiple leaves less room for error at this price.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Twilio have you on the fence, move quickly from headlines to hard numbers and pressure test the bullish and bearish angles yourself. To weigh both sides clearly, start with the 3 key rewards and 4 important warning signs.
Looking for more Twilio sized investment ideas?
Do not stop at Twilio. Broaden your watchlist with focused stock ideas chosen to highlight quality, value, and resilience so you keep your edge.
- Target value first and scan for companies trading below what fundamentals suggest they might be worth using the 34 high quality undervalued stocks.
- Prioritise resilience and search for businesses with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential future leaders early by reviewing the 19 high quality undiscovered gems before others start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com