


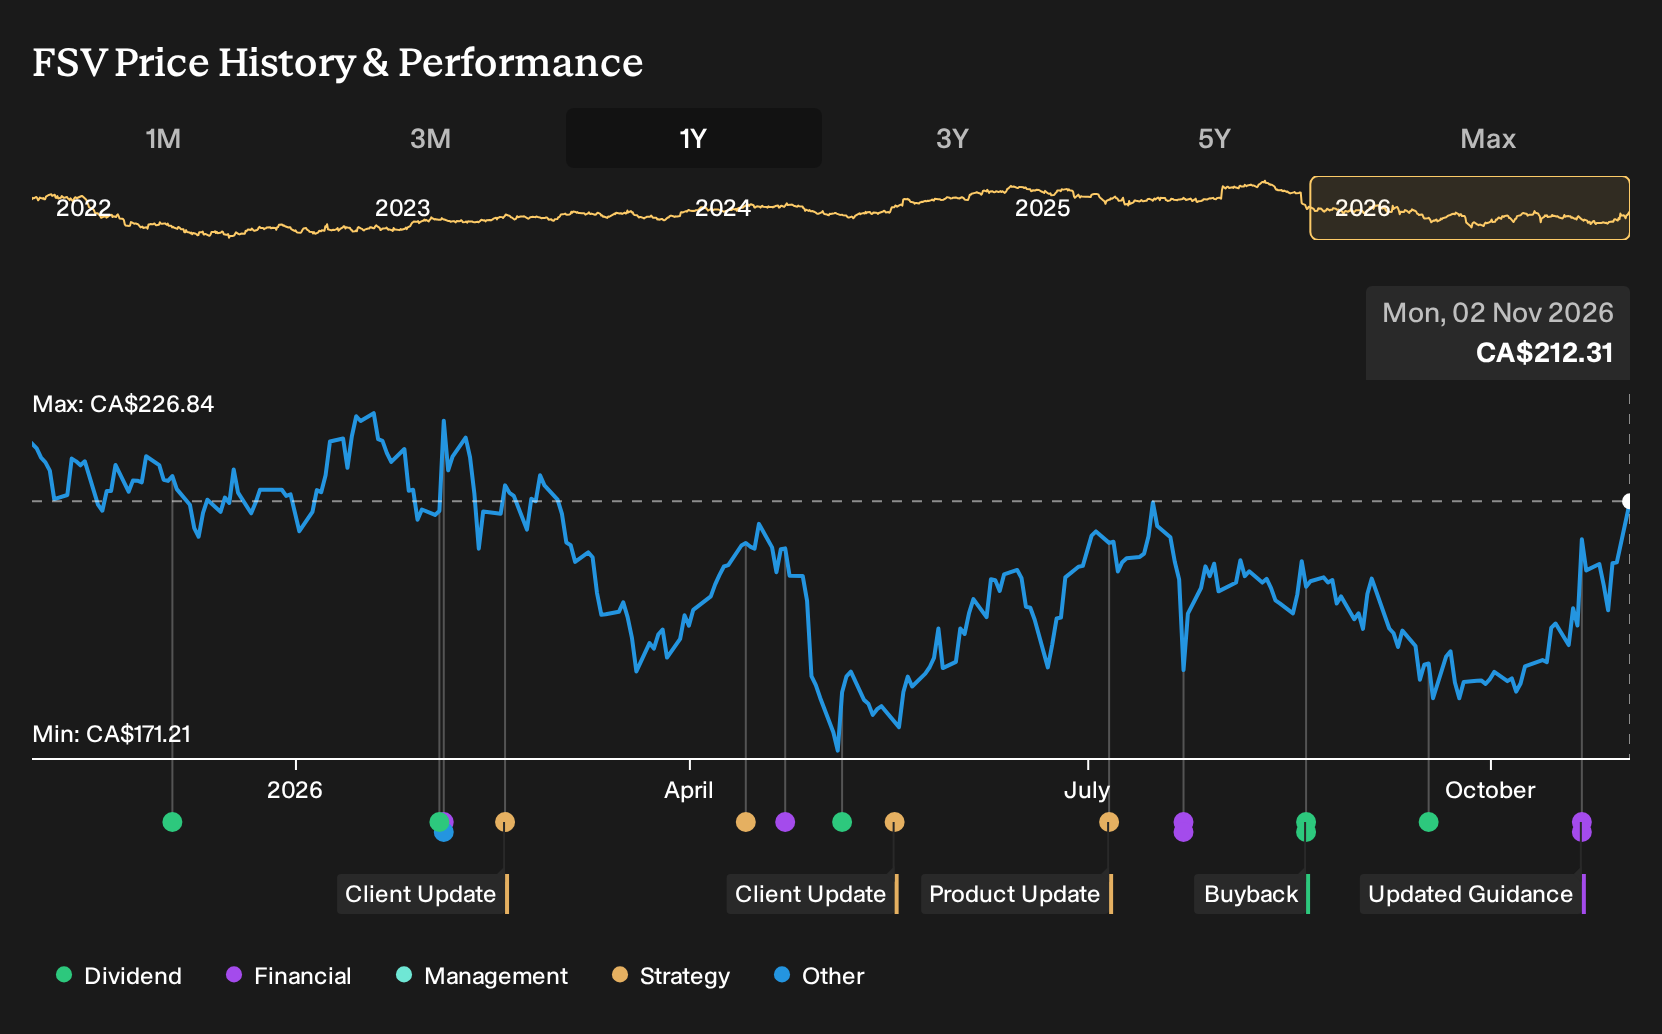
- FirstService reported third quarter 2026 sales of US$1,531.7 million and net income of US$42.91 million, and completed share repurchases totaling 2,742,667 shares, or 6.07%, for US$375.5 million under two buyback authorizations.
- The combination of higher sales, lower quarterly earnings, and sizeable buybacks suggests management is focusing on capital allocation while addressing margin and organic growth pressures.
- We will now examine how this combination of softer quarterly earnings and cautious fourth quarter revenue guidance may influence FirstService's investment narrative.
FirstService Investment Narrative Recap
To own FirstService, you need to be comfortable with a property services group that leans on steady residential management and project based restoration while working through pressure in roofing and home services. The latest quarter showed higher sales but lower earnings, and the flat to slightly weaker organic revenue outlook for the fourth quarter keeps the focus on execution rather than expansion.
Right now the near term swing factor is how quickly large loss restoration work and tuck under deals translate into steadier margins. The biggest operational risk remains a soft roofing market and any prolonged weakness in housing related demand, which could keep organic growth muted even as FirstService adjusts its cost base.
The most relevant update for this story is the completion of US$375.5 million in buybacks covering 2,742,667 shares, or 6.07%, under two authorizations through late September 2026. That is a meaningful reduction in share count alongside mixed quarterly earnings and cautious revenue guidance.
For you as a shareholder, the repurchase program ties directly into the catalyst of converting operational progress into per share metrics. If restoration projects, Century Fire acquisitions and core residential services perform as planned, fewer shares can magnify that effect. If roofing and home services remain under pressure, the financial impact of the buybacks will depend heavily on how well FirstService defends margins and manages debt.
What The Analyst Framework Implies For FirstService
Analysts are effectively sketching out a version of FirstService in 2029 that is bigger, slightly more profitable on each dollar of sales, and supported by a smaller share count. That framework rests on a few simple building blocks that you can pressure test against your own expectations.
FirstService's narrative projects US$6.5b revenue and US$218.2m earnings by 2029. This implies 5.1% yearly revenue growth and an earnings increase of about US$56.8m from US$161.4m today.
The revenue piece assumes that the mix of residential management, restoration, fire protection and home services can collectively support annual top line expansion of 5.1% over the next three years. That is a steady, mid single digit climb rather than a high growth sprint, which means your view on the durability of contract based residential fees and the pace of tuck in deals becomes important.
Earnings expectations build in a move from profit margins of 2.9% today to 3.4% in three years. For you as a shareholder, that margin gap is where a lot of the debate sits. The uplift assumes cleaner execution in restoration projects, better pricing and mix in fire and specialty work, and some relief from the current drag in roofing and home services.
On top of that, the analyst model assumes the share count keeps shrinking by 3.92% a year for the next three years. If FirstService continues to retire stock at anything close to that pace, and the earnings path holds, then earnings per share would grow faster than total profit. If the business hits a softer patch, ongoing buybacks would still reduce the denominator but with less support from the numerator.
Valuation assumptions bring all of these moving parts together. The consensus view points to FirstService trading on a P/E of 38x in 2029, compared with 36.4x today, and well above the 10.5x currently quoted for the Canadian real estate peer group. That gap effectively prices in stronger growth, more resilient cash generation, or a cleaner balance sheet than a typical sector peer.
At a current share price of CA$188.62 against a consensus target of CA$238.65, the sell side is baking in a 21% uplift. For your own work, the more useful detail is the set of conditions attached to that view. You would need to be comfortable that by 2029 FirstService can generate US$6.5b of sales, earn US$218.2m of profit, and still attract a premium multiple north of 35x on those earnings.
Put differently, the story embedded in these numbers is not about a sharp cyclical rebound. It is about FirstService steadily converting backlog in restoration, expanding higher value fire and specialty work, keeping a tight grip on costs in weaker roofing markets, and recycling excess cash into buybacks without stretching the balance sheet. Your own conclusion on the stock will hinge on how realistic that combination feels over the next few years.
Uncover why FirstService's fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly around CA$238.65 to CA$239.57, so you are seeing a very narrow band rather than wild disagreement, at least so far. When you set that beside FirstService’s subdued fourth quarter revenue outlook and heavy recent buybacks, you get very different interpretations of risk and opportunity. Treat this as a starting point and explore more community views before leaning on any single narrative.
Explore another FirstService fair value estimate, including one that suggests it could be worth just CA$238.65.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your FirstService research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FirstService. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FirstService's overall financial health at a glance.
Looking For More Investment Ideas Beyond FirstService?
If the FirstService story has you thinking about portfolio upgrades, it can help to scan for other companies that match the sort of quality or risk profile you prefer. The Simply Wall St Screener lets you filter by balance sheet strength, income potential, or valuation so you are not just reacting to a single stock but building a watchlist that fits your own plan.
- If capital preservation sits high on your list, start with a basket of companies that score well on financial resilience by checking the 9 resilient stocks with low risk scores.
- If cash flow dependability matters more to you, focus on businesses that combine high income with staying power by reviewing the 3 dividend fortresses.
- If you want to widen your opportunity set beyond widely followed tickers, cast the net over potential future leaders with the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com