


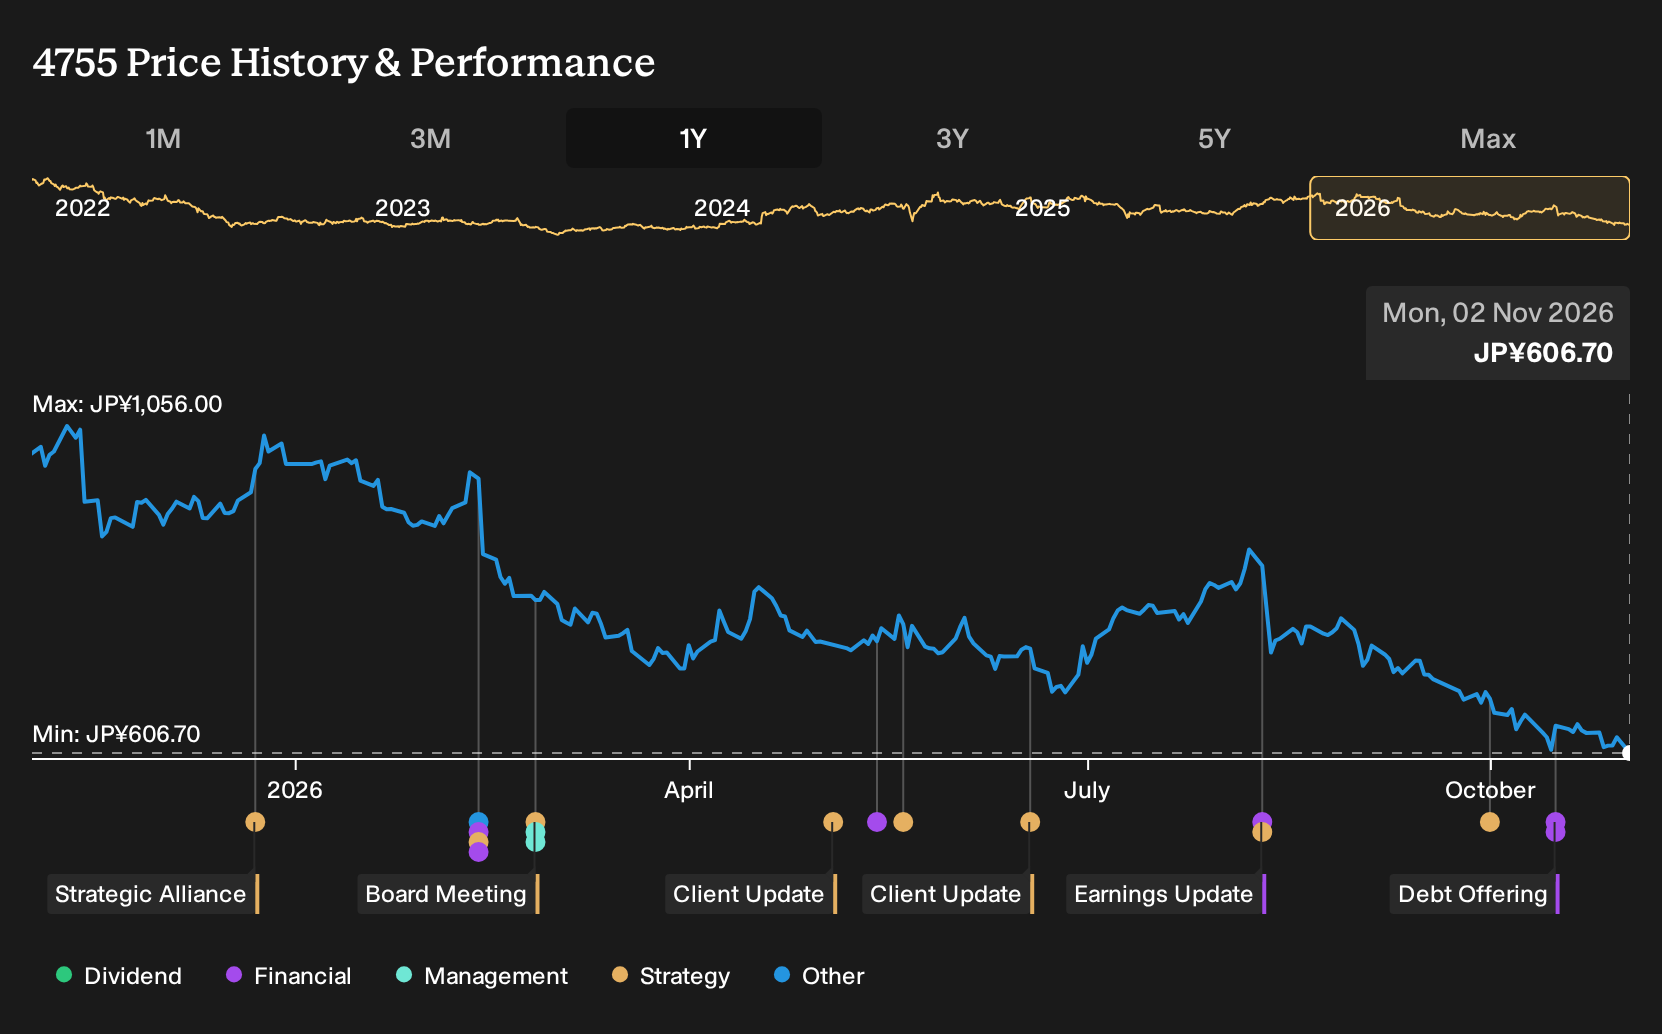
Rakuten Group spent much of the year telling a story of improving operations, new AI driven partnerships and a deeper push into crypto and loyalty. For Rakuten Group shareholders, the loss over the past year was 39.9%, including dividends. If you had bought on 2 November 2025, confident that bullish and bearish analyst camps had already mapped the upside and downside, how did this gap between a stronger business narrative and a weaker return emerge?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond Rakuten Group. See which of 17 cryptocurrency and blockchain stocks may still merit a closer look.
The Two Rakuten Group Stories Investors Had To Weigh
The shares cost ¥1,006 at the start of the period, and anyone looking at Rakuten Group then had to choose between two very different stories on value and execution risk.
The bullish narrative pointed to a fair value of ¥1,200, which is 19% above the start price. Supporters focused on Agentic AI rolling across commerce, advertising and internal workflows, with more than 15,000 employees using it to drive operational leverage.
The bearish view anchored to a fair value of ¥510, which is 49% below the start price. Skeptics focused on heavy telecom spending and rising debt, which could keep interest costs high and leave group earnings under pressure.
What The Results Changed In The Rakuten Group Debate
Reported Q2 2026 numbers gave Rakuten Group bulls some backing. Revenue was ¥665,469m and net income moved from a loss of ¥50,964m in Q2 2025 to a profit of ¥7,707m, with net margin shifting from -8.5% to 1.2%. Profitability was still early in this period, so the case for sustained high-margin gains stayed unproven. Overall, the evidence cut both ways.
The episode turned on one claim. Could AI driven efficiency and ecosystem scale lift net margin, not just sales? When you test another stock, track whether net income and margin move in the direction the upbeat story promised, not only whether revenue grows.
What Rakuten Group's Lower Price Now Asks You To Believe
Rakuten Group trades at ¥607 today, with this selected Narrative arguing that its Fair Value sits above that level. The focus is on AI driven efficiency, FinTech consolidation and a mobile arm that now reports positive EBITDA while still absorbing heavy capex.
The fall over the past year asks buyers to judge whether AI and FinTech synergies can offset ongoing mobile investment so that improving profitability and cash generation eventually validate this Narrative.
"The main factor that has to go right is the FinTech and mobile ecosystem delivering the planned profitability and synergy uplift, while continued capex and remaining mobile operating losses stay manageable. The current valuation implies that the market is discounting Rakuten Group heavily despite evidence of improving profitability and cash generation."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Another AI Retail Play Nearby
Rakuten Group is leaning hard into AI, payments and data rich commerce. One step away, a different giant is pushing even further.
That business is pouring money into cloud AI tools that help clients run complex models. It builds custom chips and software so customers can rent computing power.
The same group uses AI inside a huge online retail and media operation. It applies automation to logistics, forecasting and personalised ads to extract more value.
If Rakuten Group keeps tightening its own ecosystem, this parallel push in AI infrastructure and advertising heavy commerce could stay worth watching.
One Narrative has already put a figure on it. → Uncover the company trading 45% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com