


Why AbraSilver Resource Is Back On Investor Radars
AbraSilver Resource (TSX:ABRA) has drawn fresh attention after reporting new assay results from its Phase VI drilling at the Diablillos project and preparing to present at Red Cloud’s Fall Mining Showcase in Toronto.
On the price side, AbraSilver Resource has seen short term momentum cool, with the 30 day share price return down 14.64% and the 90 day share price return down 28.61%, even as the current share price sits at CA$10.38. That near term softness contrasts with a very strong 1 year total shareholder return of 57.27% and a multi year total shareholder return that is several times the original investment. This suggests recent assay news and the upcoming Red Cloud presentation are landing on a story where long term holders have already experienced substantial gains while short term sentiment has faded.
Spot potential parallels and contrasts to AbraSilver Resource by scanning the 10 top silver producer stocks.AbraSilver Resource now trades well below the average analyst target, even after a strong multi year run. So where does a fair assessment land between a CA$10.38 price and a CA$23.00 target range?
Most Popular Narrative: 71% Undervalued
AbraSilver Resource trades at CA$10.38, while the most followed narrative on the stock pegs fair value at CA$36, creating a wide gap that long term holders and new entrants alike are trying to interpret.
At current assumptions, the DFS outlines an after tax NPV of approximately US$3.0 billion (about C$4.2 billion) with an exceptional 41.9% IRR, only US$722 million of initial capital, and a rapid 1.7-year payback. The project also ranks among the lowest-cost primary silver projects globally, with life-of-mine AISC of approximately US$20/oz AgEq. Perhaps most importantly, the project generates an outstanding 4.2x NPV-to-capex ratio, demonstrating how much value is created for every dollar invested.
See why 10 investors see AbraSilver Resource as 71% undervalued.
According to MineStackr, that narrative fair value of CA$36 implies AbraSilver Resource trades at roughly a 71% discount, with the Diablillos DFS economics and NPV to capex ratio acting as the main pillars behind the thesis.
The same storyline leans heavily on Diablillos being described as one of the largest undeveloped primary silver projects globally, with potential upside from throughput expansion, heap leach processing of lower grade material, and further district exploration that MineStackr believes are not fully reflected in current pricing.
Investors weighing this view against the current CA$1.66b market capitalization and absence of revenue may want to consider how much of the DFS and exploration potential they regard as achievable and how they price the funding, execution, and timeline risks around bringing a project of this scale into production.
Result: Fair Value of CA$36 (UNDERVALUED)
Still, the AbraSilver Resource story depends heavily on advancing Diablillos from study stage to construction, with financing terms and permitting progress both capable of sharply reframing this undervaluation narrative.
Find out about the key risks to this AbraSilver Resource narrative.
Another View: How Multiples Challenge The AbraSilver Resource Story
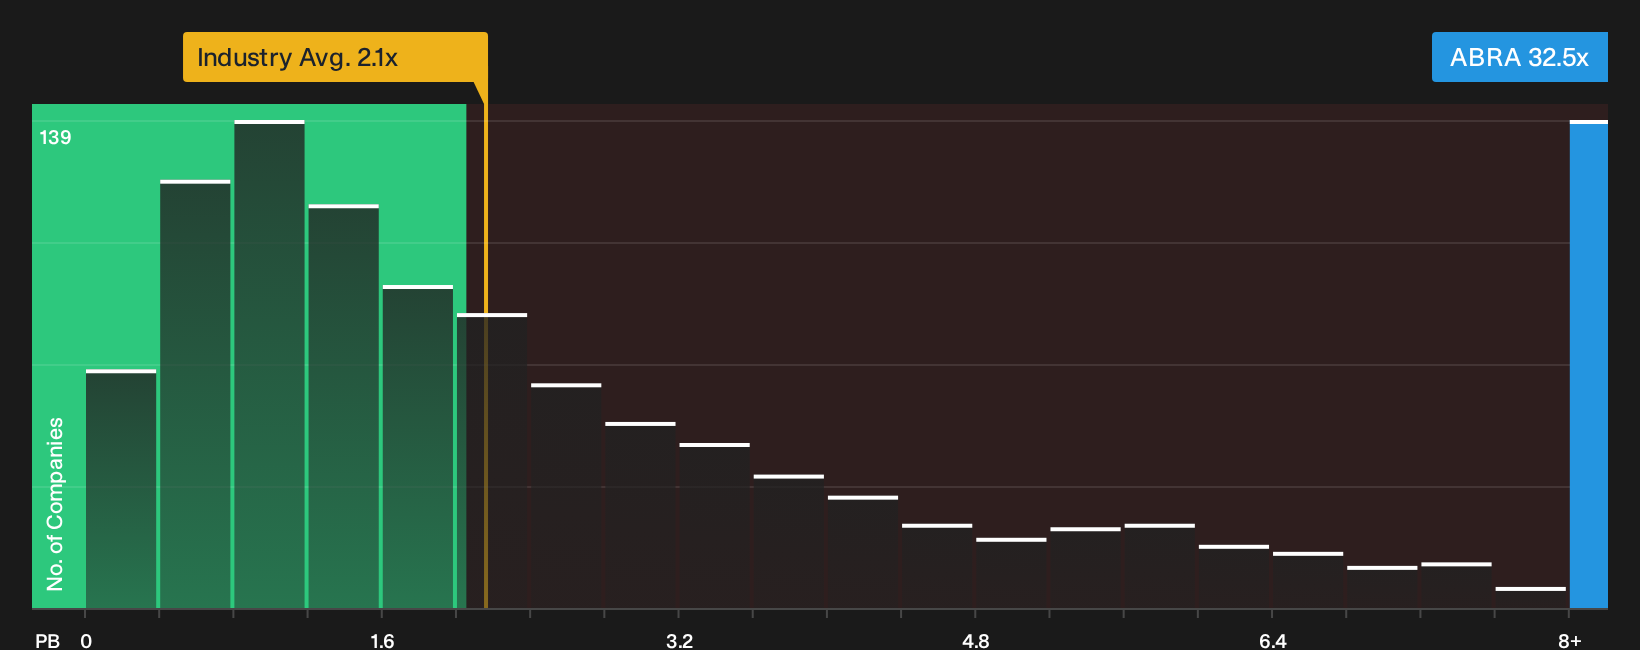
That CA$36 fair value narrative for AbraSilver Resource leans on project economics, yet the market is still pricing the shares at a very rich P/B of 32.5x. The Canadian Metals and Mining sector averages 2.1x, while close peers sit near 126.9x. This raises a simple question: Is this premium a cushion for Diablillos, or a valuation risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big upside stories like AbraSilver Resource can create strong opinions, so pressure test every assumption quickly using the full set of risk flags and the 2 important warning signs.
Looking for more investment ideas beyond AbraSilver Resource?
If AbraSilver Resource has sharpened your focus, do not stop there. Use the Simply Wall Street Screener to surface fresh opportunities that match your approach.
- Target potential mispricings by scanning companies that combine strong fundamentals with what may be appealing entry points through the 5 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (6 results) that can help cushion portfolios when conditions get tougher.
- Hunt for future leaders before the crowd catches on by checking a 8 high quality undiscovered gems that might otherwise stay off your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com