


Oil markets have been jolted again by reports of a US strike on Iran's Qeshm Island, reminding investors how quickly supply disruptions can reshape winners and losers. Periods like this often reward businesses that can grow through disruption, especially when insiders have meaningful skin in the game. This article highlights three fast growing, high insider ownership stocks from our screen that could benefit from disciplined execution in a more volatile world.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where management ownership closely aligns with shareholder interests. However, if you want the names that matter most, these 372 high growth high conviction stocks are the strongest companies we've found.
Sansan (TSE:4443)
Sansan is a Tokyo based software group that runs a cloud contact management and CRM platform at the center of its growth story, with this Sansan and Bill One segment generating ¥48,865 million alongside smaller Eight and other units, and a market value of roughly ¥268.0b.
Sansan ties directly into the fast growing, high insider ownership theme through its CRM led SaaS model, where earnings jumped very sharply year on year and net sales are forecast in the ¥63.7b to ¥65.3b range for FY2027. Investors who care about recurring revenue and margin expansion will watch what happens when that CRM engine meets one unseen pressure on growth quality.
That unseen pressure is exactly where the real story starts, and the 3 key rewards and 1 important warning sign shows how Sansan's growth profile and insider alignment intersect with execution risk.

Micronics Japan (TSE:6871)
Micronics Japan develops semiconductor test gear such as probe cards and wafer probers that serve AI, automotive and cloud chip production, generating about ¥84.9b from its Probe Card Business versus ¥1.4b from TE Business, with a market value near ¥438.5b.
Earnings are forecast to grow about 24.9% a year, with revenue expected to rise roughly 23% and forecast return on equity above 20%. This profile in a critical semiconductor test niche fits the “fast growing with committed insiders” brief, although a rich P/E and share price swings keep attention on what happens if a single key assumption breaks.
If that assumption really matters to you, start with the 2 key rewards and 1 important major warning sign to see what could accelerate Micronics Japan or stall it at the wrong moment.

Kasumigaseki CapitalLtd (TSE:3498)
Kasumigaseki Capital runs a Tokyo based real estate consulting operation that generated ¥163.8b from its Real Estate Consulting Business in Japan. It uses its solar power projects as the clearest link to the fast growth, high insider ownership theme, and carries a market value around ¥180.1b.
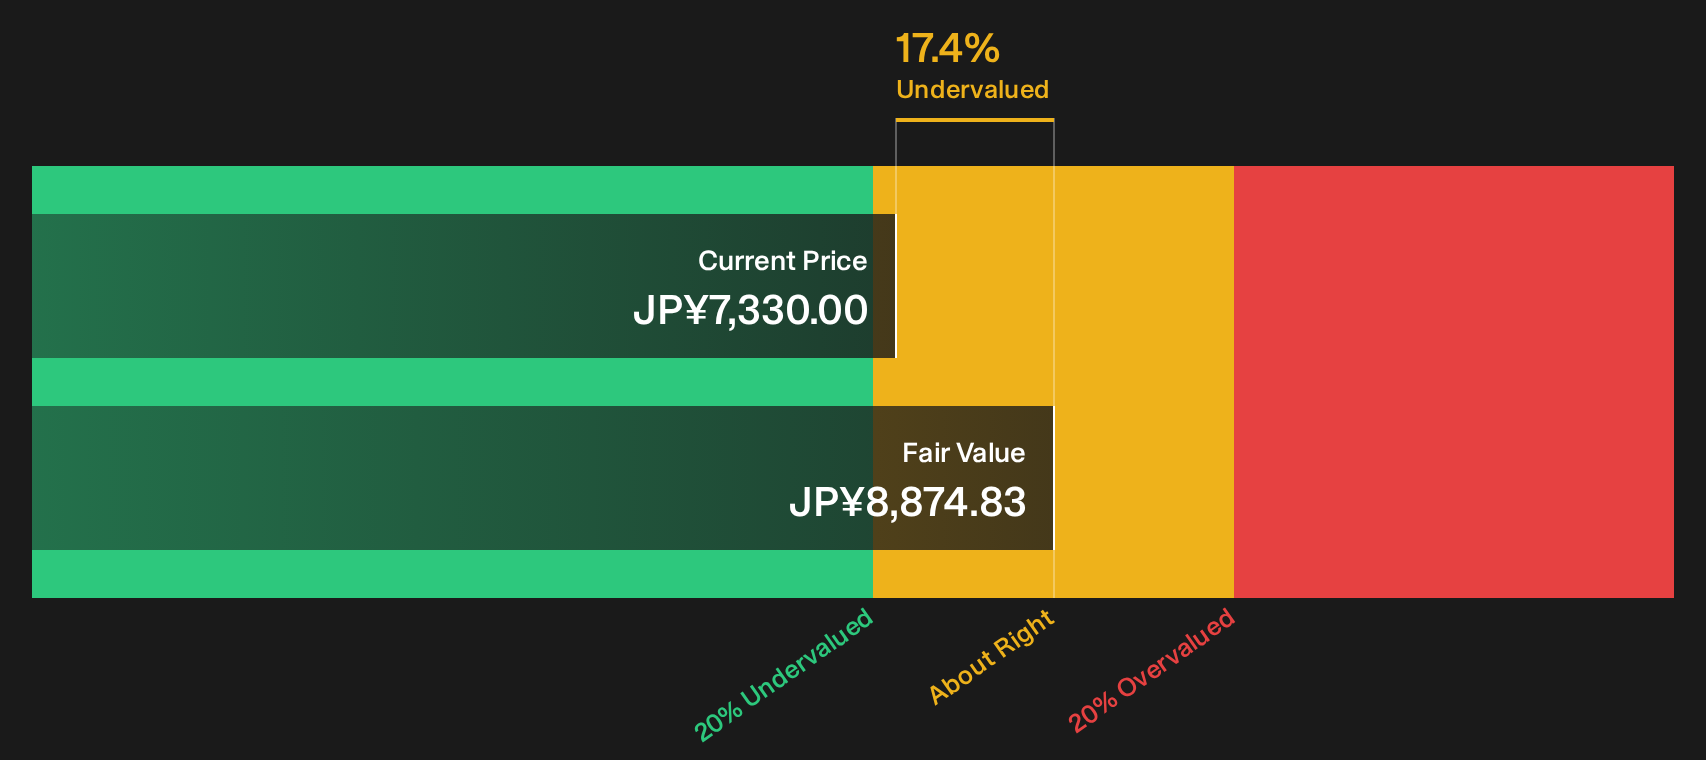
Kasumigaseki Capital combines rapid earnings expansion, with net income at ¥16,692 million on ¥163,756 million of sales in 2026 and forecast earnings growth of 27.86% a year, with a share price about 17.4% below one fair value estimate. This leaves the growth story heavily influenced by what happens when funding-heavy solar and real estate projects meet tighter cash flow tests.
Those cash flow tests are exactly where the story could accelerate, so read the 3 key rewards and 5 important warning signs (2 are major!) before funding pressures and growth expectations decouple.
Seeking Alternatives Before The Crowd
Fresh breakouts rarely stay quiet for long. Momentum can shift quickly, and ideas that are under the radar for now may draw wider attention as more investors take notice.
- Capture income that continues to work in different market conditions by focusing on dependable payers through the 30 dividend fortresses before yields start dropping.
- Identify potential automation leaders early by scanning the 95 robotics and automation stocks while many of these operators remain under the radar.
- Prepare for possible AI infrastructure constraints by reviewing the 53 AI infrastructure stocks and monitoring where capital is building momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com