


If you had put money into Principal Financial Group at the start of this period, the result would likely make you stop and recheck your old notes. Holding Principal Financial Group over the past year would have returned 40.6%, including dividends. That kind of outcome looks simple in hindsight; however, early buyers were weighing fee pressure, digital gaps, and mixed analyst targets. If you faced that same choice again, which of those competing signals would carry the most weight today?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Principal Financial Group. Zero in on 34 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing On Principal Financial Group
The shares cost US$84.02 at the start of the period. Anyone looking at Principal Financial Group then had to choose between two sharply different stories that still sounded reasonable.
The bullish Narrative put Fair Value at US$101. It leaned on rising demand for retirement and wealth products, supported by an aging population and expansion into markets such as Mexico and Southeast Asia.
The bearish view set Fair Value at US$72. It focused on persistent market volatility that could pressure fee income in retirement and asset management and make upcoming quarters harder to predict.
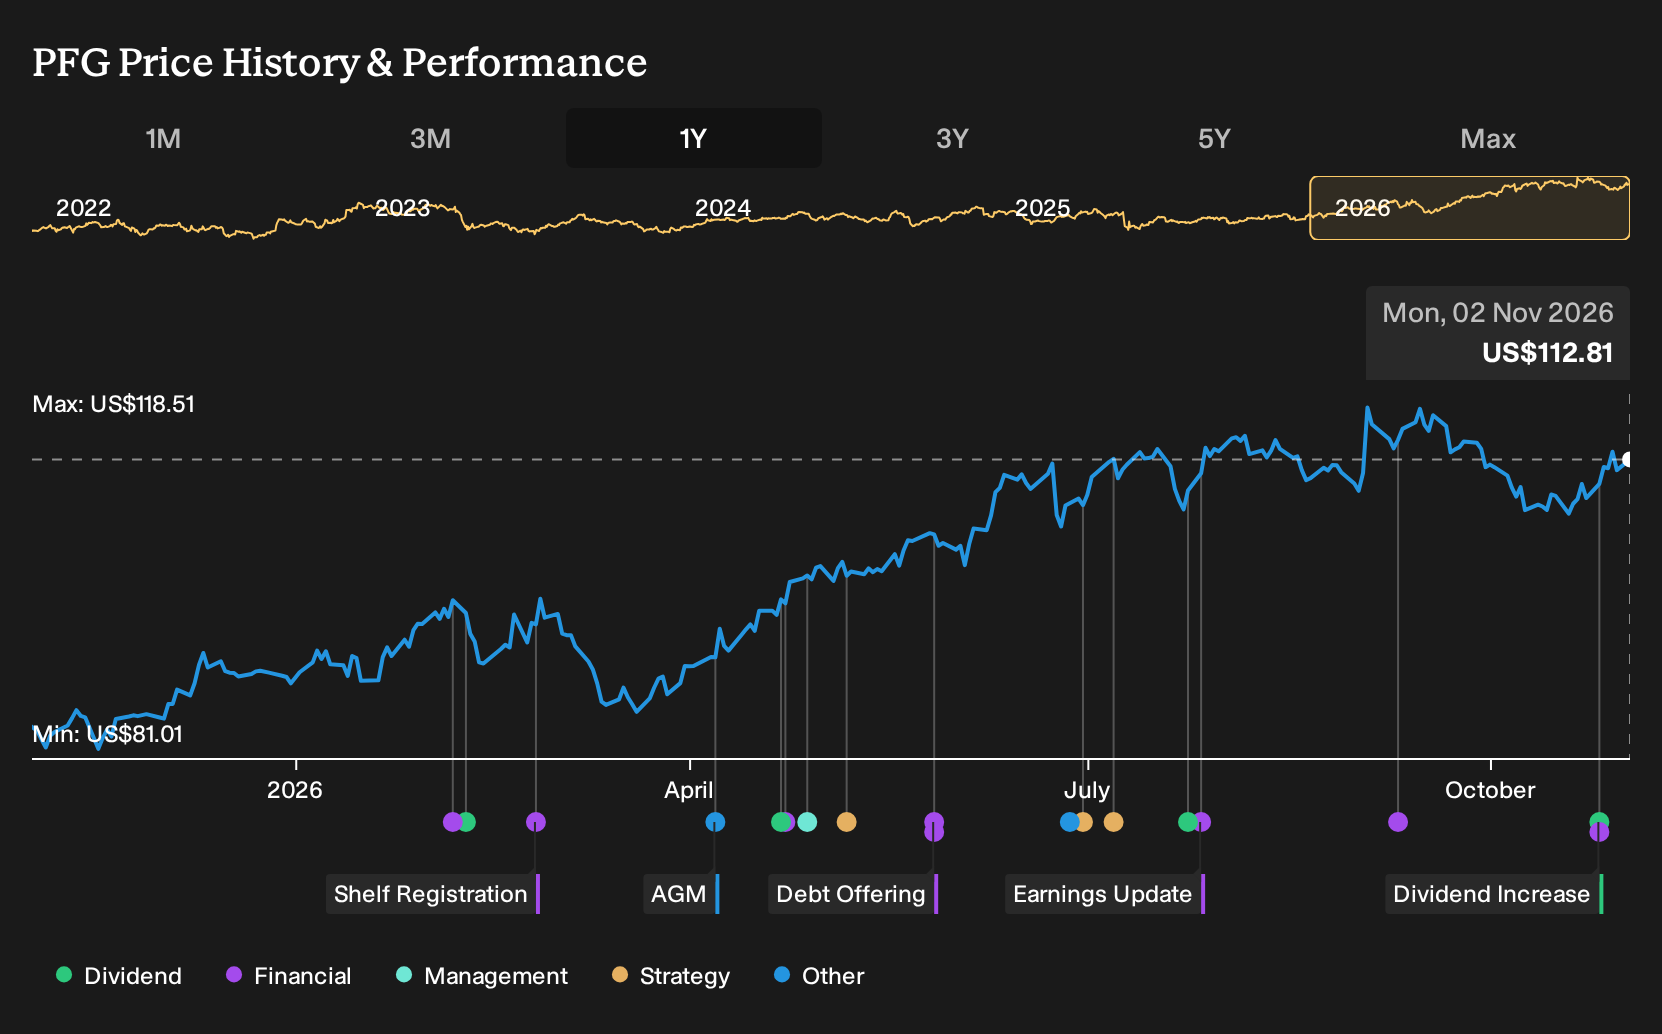
What The Results Changed For The Principal Financial Group Narrative
The clearest shock to both stories came from Principal Financial Group’s Q3 2026 figures. Revenue rose to US$4,616.4m and net income reached US$631.9m, with net margin moving from 5.8% to 13.7%. That scale of profitability supported the optimistic case on earnings power. The 2026 AUM shifts and Beam Benefits acquisition kept pressure on fees and flows, so the evidence cut both ways.
The lesson is simple. When a thesis hangs on margins, treat net income and net margin as the main fact check and track how each quarter lines up with the original narrative.
What Today's Price Already Assumes For Principal Financial Group
Principal Financial Group now trades at US$113. This Narrative’s Fair Value sits below that level, which means the current quote already leans on a more optimistic path than the Narrative itself assigns.
The argument turns on whether strong EPS and margin progress can offset pressured flows and fee rates. For today’s price to add up, a buyer has to believe disciplined costs and solid underwriting will keep margins firm even if net flows in certain strategies remain fragile.
"Key Takeaways: Bearish analysts expect Principal Financial Group’s earnings growth to slow as continued market volatility and ongoing net outflows in certain active equity strategies pressure fee revenue and profitability. The main thing that has to go right is that Principal Financial Group continues to translate its cost discipline and underwriting results in Specialty Benefits and Benefits and Protection into sustained margin strength, even while funding technology and AI investments."
The price and this Narrative do not agree. → Uncover what this Narrative says Principal Financial Group is actually worth
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 49% below our estimate - converts a record backlog of technology heavy data center projects into installation work.
- Company 2 - 36% below our estimate - leans on continued dominance in GPU design and AI software to win data center budgets.
- Company 3 - 30% below our estimate - ties AI demand to a growing cloud platform where subscriptions and usage run together.
That is three of the list. See every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com