


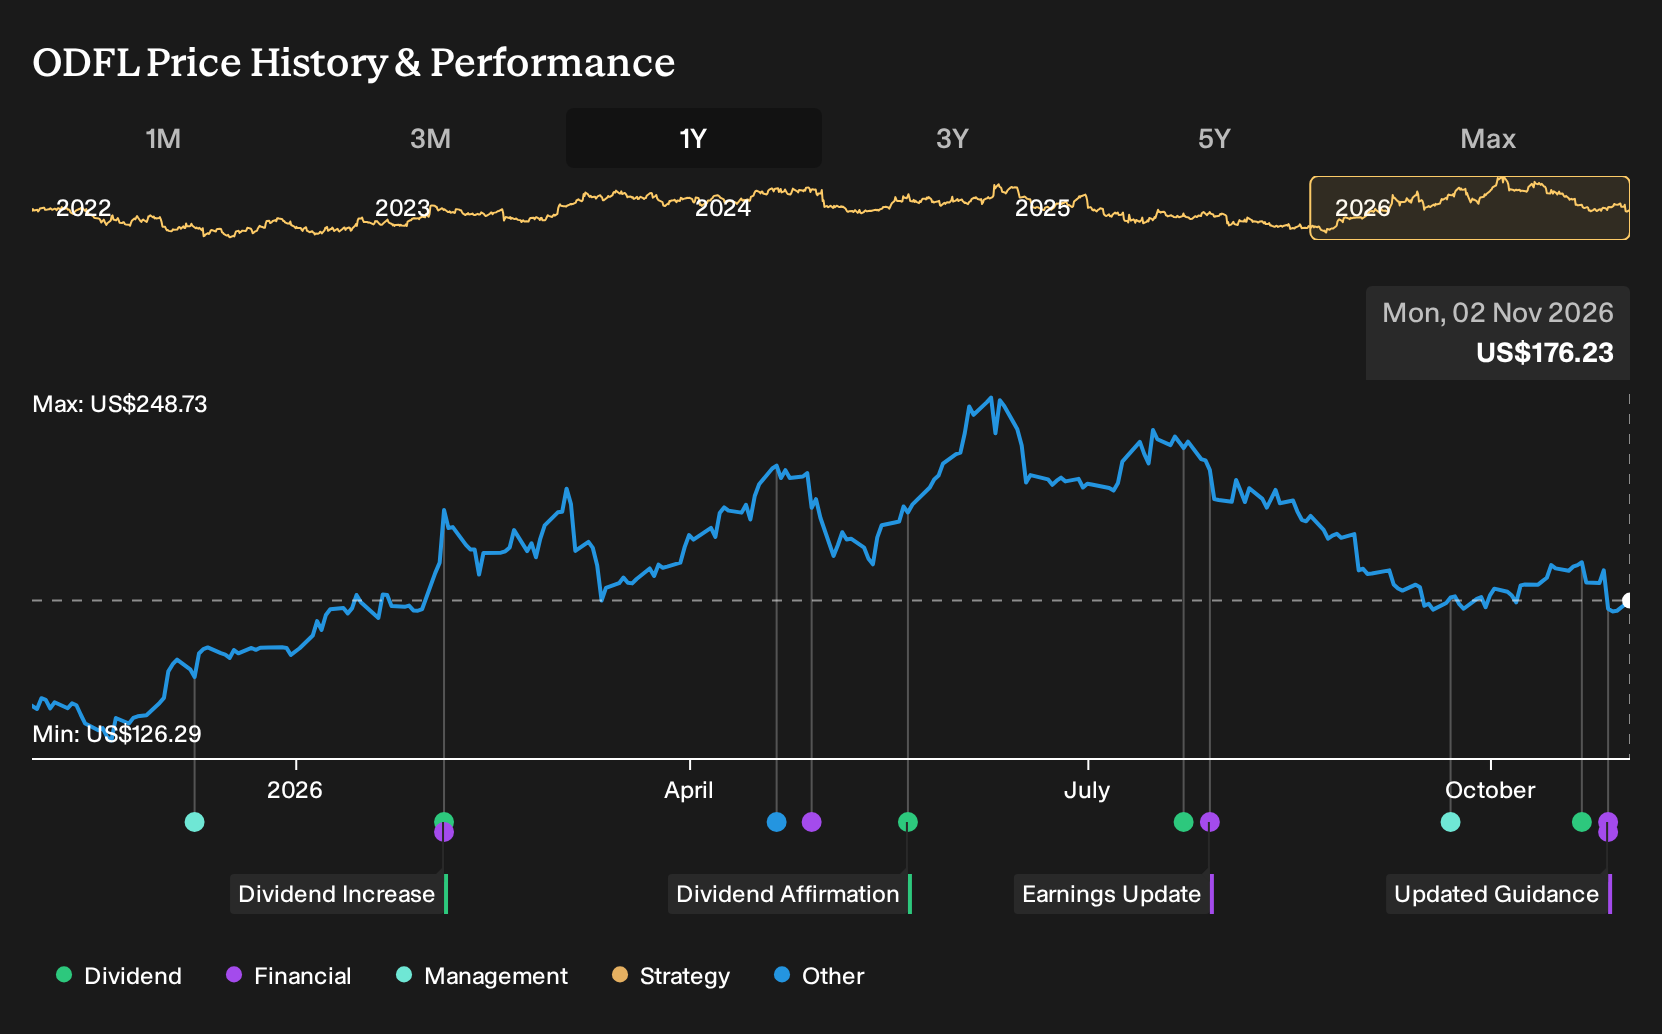
- Old Dominion Freight Line reported third quarter 2026 sales of US$1,590.73 million, net income of US$343.75 million and diluted EPS of US$1.65, and issued fourth quarter revenue guidance of US$1.54 billion to US$1.58 billion that management described as above normal seasonality.
- The board also approved a quarterly dividend of US$0.29 per share for December 2026, a 3.6% increase on the prior year payout. Management indicated that this reflects continued confidence in Old Dominion Freight Line’s cash generation and balance sheet strength.
- We will now look at how Old Dominion Freight Line’s investment narrative is influenced by its above seasonal revenue outlook for the fourth quarter.
Old Dominion Freight Line Investment Narrative Recap
To own Old Dominion Freight Line, you need to be comfortable with a freight story that leans on pricing power, tight execution and heavy investment in the network rather than chasing every shipment. The latest third quarter numbers and above seasonal fourth quarter revenue guide lean into that narrative, since they highlight volume pressure but also show the business still converting revenue into profit efficiently.
The near term catalyst remains whether Old Dominion Freight Line can keep its operating ratio trending lower while unit volumes lag some peers and diesel and capex stay elevated. The main risk is that domestic freight demand or pricing weakens, which would make it harder for management to offset higher operating and investment costs.
The guidance for US$1.54b to US$1.58b of fourth quarter 2026 revenue is the announcement that really matters for this setup. It sits on top of third quarter sales of US$1,590.73 million and net income of US$343.75 million. This confirms the current run rate of earnings power management is working with as it leans into efficiency and yield management.
For you as a shareholder, that revenue range ties directly into the catalysts and the risks. It tests whether Old Dominion Freight Line can keep growing ex fuel yield and holding service levels near 99% on time performance while unit volumes have been softer and diesel and capex budgets, at about US$380 million in 2026, keep pressuring the operating ratio and cash needs.
How Old Dominion Freight Line’s Long Term Story Is Framed By Analyst Assumptions
Analysts are effectively asking you to judge Old Dominion Freight Line on a much bigger canvas than a single quarter or dividend hike. Their models sketch out a freight carrier that compounds revenue at 7.5% a year over the next three years and edges net margins higher from 20.1% today to 22.1% by 2029. That combination feeds into a view of a business putting more of each future sales dollar into profit, even as it continues to spend heavily on trucks, terminals and technology.
The earnings bridge is where the long term call tightens up. Current earnings of about US$1.2b are projected to reach consensus expectations of US$1.6b by 2029, which means an increase of roughly US$400m in annual profit on the base analysts see today. Some forecasters push that to US$1.8b, so the spread between cautious and upbeat views is wide enough that your own conviction on Old Dominion Freight Line’s margin and volume mix really matters. The forecast decline in shares outstanding of about 0.96% each year for the next three years adds another lever, since fewer shares against higher earnings would lift earnings per share if those projections play out.
Valuation assumptions build directly on that earnings path. To reach the consensus price target of US$214.76 from a current share price reference of US$172.41, the stock would need to trade on a P/E of 34.4x those projected 2029 earnings of US$1.6b. That multiple sits above the current 30.9x P/E cited for the wider US Transportation industry and above Old Dominion Freight Line’s own present 30.8x level. This means the thesis is not only about earnings growth but also about the market assigning a richer valuation multiple to those future profits. For investors assessing Old Dominion Freight Line today, the key question is whether that combination of mid single digit volume trends, yield management and capital intensity can reasonably support both the earnings step up and the higher P/E that are embedded in these models.
Old Dominion Freight Line's narrative projects US$7.2b revenue and US$1.6b earnings by 2029. This assumes 7.5% yearly revenue growth and an earnings increase of about US$400m from current earnings of roughly US$1.2b.
Uncover why Old Dominion Freight Line's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bearish twist to keep on your radar is the concern that Old Dominion Freight Line’s heavier capital spending may not earn strong enough returns. Before this latest guidance, the lowest analysts were penciling in about US$7.1b of 2029 revenue and roughly US$1.6b of earnings. That is a much cooler story than consensus. These forecasts were set before the above seasonal fourth quarter outlook, so it may be useful to monitor how opinions evolve as fresh data arrives and compare several viewpoints before deciding how this stock fits your own plan.
Explore 5 other Old Dominion Freight Line fair value estimates, including one that suggests as much as 11% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Old Dominion Freight Line research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Old Dominion Freight Line. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Dominion Freight Line's overall financial health at a glance.
Looking for more Old Dominion Freight Line sized ideas?
If you want to stress test your thesis on Old Dominion Freight Line and widen your opportunity set at the same time, use the Simply Wall St Screener to compare it with other companies that share similar financial traits but sit in very different corners of the market.
- For investors who care most about downside protection and consistent fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can complement or contrast what you see in Old Dominion Freight Line.
- If you are hunting for quality at a price that looks reasonable, scan a curated pool of 34 high quality undervalued stocks that might offer a different risk reward profile to Old Dominion Freight Line.
- When you want to uncover less crowded ideas, widen the lens to a group of 19 high quality undiscovered gems that share strong fundamentals but are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com