


Anthropic just put a gigantic price tag on the AI buildout, with Q3 revenue near $17b and almost $895b in long-term infrastructure commitments, and that kind of scale can reshape where capital flows next. Banks and insurers tied into corporate credit and data-center financing may sit closer to the action than most investors think. This article walks through three stocks exposed to that story, and explains why their AI-linked lending and financing pipelines now deserve a closer look.
The three stocks below are only a small sample of the banks and insurers exposed to this AI buildout theme, and the full screen surfaced 52 more large, liquid financials with equally compelling lending stories that are not covered here. To go broader and identify your own highest conviction angles on this credit and data-center theme, head straight into the Global Banks and Insurers Exposed to Large-Scale Corporate Credit and Data-Center Financing screener.
Skandinaviska Enskilda Banken (OM:SEB A)
Skandinaviska Enskilda Banken plugs directly into the AI buildout theme through its corporate and investment banking franchise, where large Nordic and global borrowers come for structured financing, syndicated loans, and infrastructure projects that can include data centers and high intensity computing facilities.
SEB generates SEK27.3b from Corporate & Investment Banking, SEK22.3b from Business & Retail Banking, SEK11.4b from Wealth & Asset Management, and SEK10.8b from the Baltic segment, with a market value of about SEK406.0b.
"SEB's focus on increasing fees and commissions in the CIB division, now supported by a record SEK 7.2b net fee and commission income in Q2 2026 driven by capital markets activity and card fees, points to a larger share of group revenue coming from fee based income rather than rate sensitive net interest income."
What matters next is how one less visible cost pressure interacts with this push toward a leaner, fee heavy income mix.
That cost pressure is the real hinge. Read the full narrative for Skandinaviska Enskilda Banken to see how Skandinaviska Enskilda Banken's AI linked credit engine could accelerate or quietly stall.

Standard Bank Group (JSE:SBK)
Standard Bank Group is one of the key African lenders plugged into large corporate and infrastructure funding, which naturally includes potential data-center and digital projects. Its scale in everyday payments hints at how that role could grow from here.
Standard Bank Group runs a broad mix of retail, business, corporate and insurance activities, with ZAR76.1b from Corporate & Investment Banking, ZAR51.0b from Personal & Private Banking, ZAR36.4b from Business & Commercial Banking and ZAR26.0b from Insurance & Asset Management, and has a market value of about ZAR484.5b.
"The shift in revenue and funding mix toward payments and transactional activity is more visible after processing ZAR 88t in payments in the first half of 2026, with electronic domestic values up 11% and cross border market share rising to 19%."
What really matters is how one less visible funding pressure interacts with this payments engine if AI driven infrastructure borrowing picks up pace.
If that funding squeeze is what you are worried about, the full narrative for Standard Bank Group joins the dots between Standard Bank Group's payments engine, AI credit pipelines and where mispricing might be hiding.

United Overseas Bank (SGX:U11)
United Overseas Bank taps directly into the screener theme through its corporate and cross border lending engine, which links ASEAN borrowers to large syndicated and infrastructure financings that can include data centre projects tied to the current AI buildout.
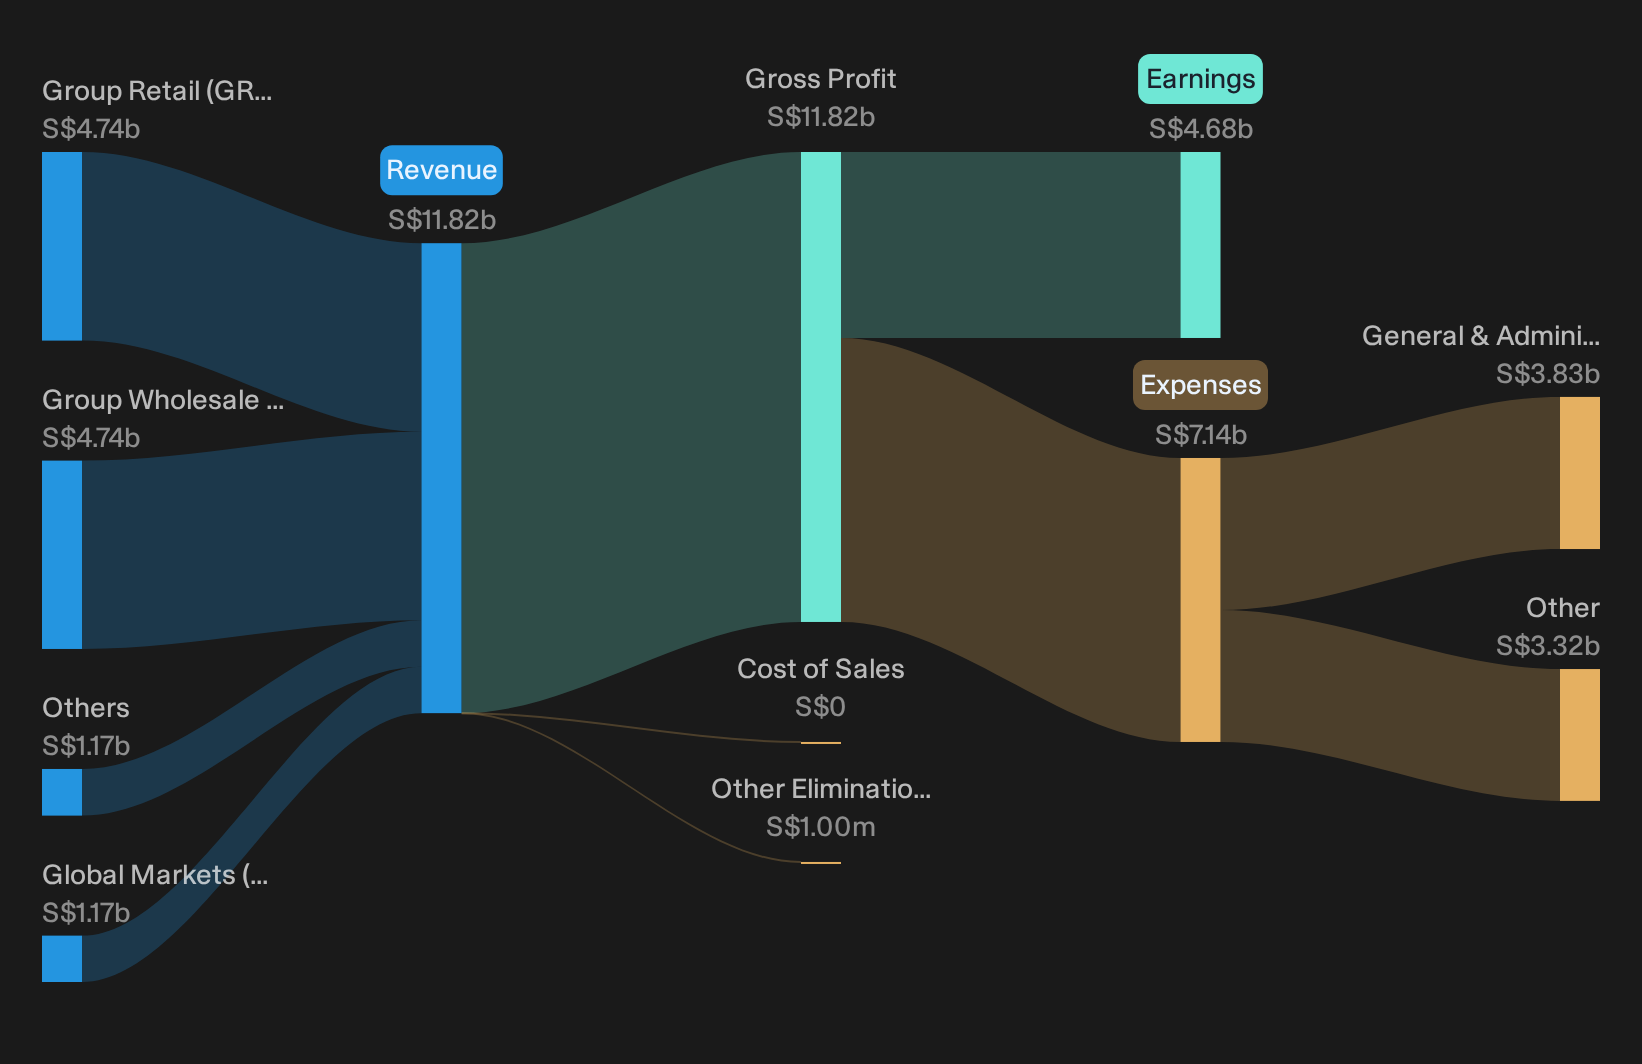
United Overseas Bank runs a broad mix of retail and wholesale banking, with Group Retail contributing about SGD4.7b, Group Wholesale Banking around SGD4.7b, Global Markets roughly SGD1.2b and Others SGD1.2b, and the bank is valued at about SGD67.1b.
"Positioning as a key financier of AI data centres and related power infrastructure in Southeast Asia, including participation in a roughly US$3b data centre financing and a pipeline linked to an estimated US$150b of regional energy infrastructure investment over five years, provides potential for future loan growth and fee income that supports earnings."
What investors really need to watch is how one quiet cost pressure shapes the trade off between that growth pipeline and the profitability that actually reaches shareholders.
That quiet pressure is the real hinge. The full narrative for United Overseas Bank unpacks whether United Overseas Bank's AI data centre momentum is accelerating or quietly masking margin strain.
Seeking Fresh Alternatives Before They Fly
The next breakout ideas often move while most investors are still watching yesterday's winners. Fresh momentum, under the radar for now, can get caught quickly. Consider acting promptly when you identify opportunities that fit your goals and risk tolerance.
- Spot cash rich businesses quietly building strength and use the list of solid balance sheet and fundamentals (197 results) to see which ones still trade before the crowd fully catches on.
- Hunt for income streams that keep paying even when sentiment cools and scan the 221 dividend fortresses before yields change or enthusiasm runs ahead of fundamentals.
- Track early movers in AI infrastructure and run through the 53 AI infrastructure stocks while the strongest operators are still priced like their story is unfinished.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com