


- Castellum reported third quarter 2026 revenue of SEK 2,246 million and net income of SEK 939 million, alongside nine month net profit of SEK 2,873 million and basic earnings per share of SEK 5.75 from continuing operations.
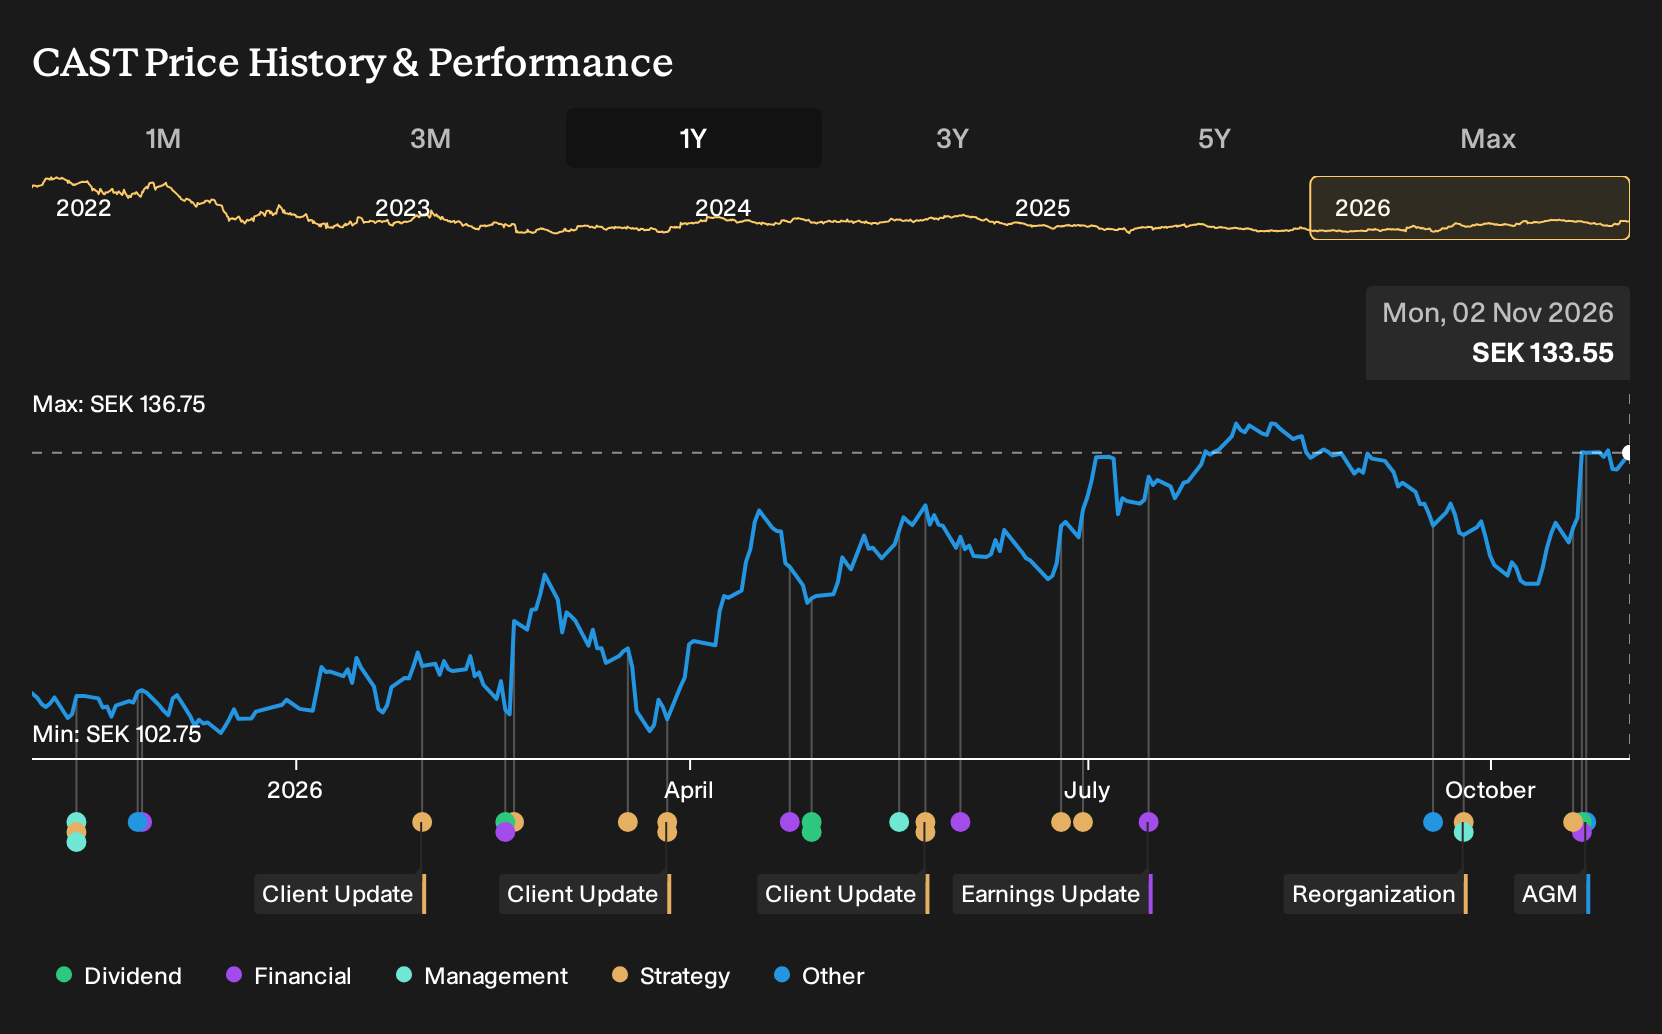
- The board also activated a new buyback mandate that allows repurchases of up to 5,416,107 shares, around 1.03% of issued capital. This signals an intent to return cash while the balance sheet already includes 47,040,587 treasury shares.
- Next, the focus shifts to how Castellum's refreshed buyback program might influence the longer term investment narrative around capital allocation.
Compare Castellum's fresh buyback move with other property stocks returning cash to shareholders by scanning our hand picked 221 dividend fortresses.
Castellum Investment Narrative Recap
To stay on board with Castellum, you need to believe the property portfolio can handle weaker Nordic office demand while cost savings and asset sales keep earnings resilient. The latest quarter showed SEK 2,246 million of revenue and SEK 939 million of net income. The short term focus is still on stabilising like for like rents and occupancy.
The biggest near term swing factor remains vacancy and pricing on lease renegotiations. Higher vacancies, lower like for like income and a rising average interest rate all sit on the risk side. The fresh buyback mandate itself does not materially change those operational challenges. Execution on lettings and cost control still matters more.
The most relevant fresh disclosure is the new SEK funded buyback program of up to 5,416,107 shares, valid until the next AGM. That sits on top of 47,040,587 shares already in treasury and interacts directly with the existing capital return narrative around Castellum.
For you, the link to catalysts is about how per share earnings develop if operating profit, financing costs and vacancies move around. Buybacks can lift earnings per share if profits hold up, but they do not offset risks from lower like for like rental income, an 87.5% occupancy rate and higher interest expense if those pressures persist.
Castellum's current analyst narrative points to revenue of SEK 7.8b and earnings of SEK 4.3b by 2029, based on a forecast 7.9% yearly decline in revenue and an earnings increase of about SEK 1.6b from SEK 2.7b today.
Uncover why Castellum's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame this new Castellum buyback as fuel for a more aggressive earnings per share story. Before this announcement, the bullish camp was already modelling revenue of about SEK 9.0b and earnings near SEK 5.3b by 2029. That is far above consensus, and those views may shift once this fresh program is fully digested.
Explore 3 other Castellum fair value estimates, including one that suggests up to 12% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Castellum research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Castellum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Castellum's overall financial health at a glance.
Looking For More Investment Ideas Beyond Castellum?
If this Castellum update has you rethinking how you spread risk and opportunity, it can help to line it up against a wider field of companies and see where the numbers look more appealing to you.
- If you want a shortlist of companies that combine quality metrics with lower volatility, check out a set of 216 resilient stocks with low risk scores that might better match a cautious style.
- For investors hunting for value, compare Castellum with a curated 193 high quality undervalued stocks that pair stronger fundamentals with prices that some might view as undemanding.
- If you prefer to focus on sturdier finances first and upside later, start with a list of solid balance sheet and fundamentals (197 results) and see which businesses line up with your risk appetite.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com