


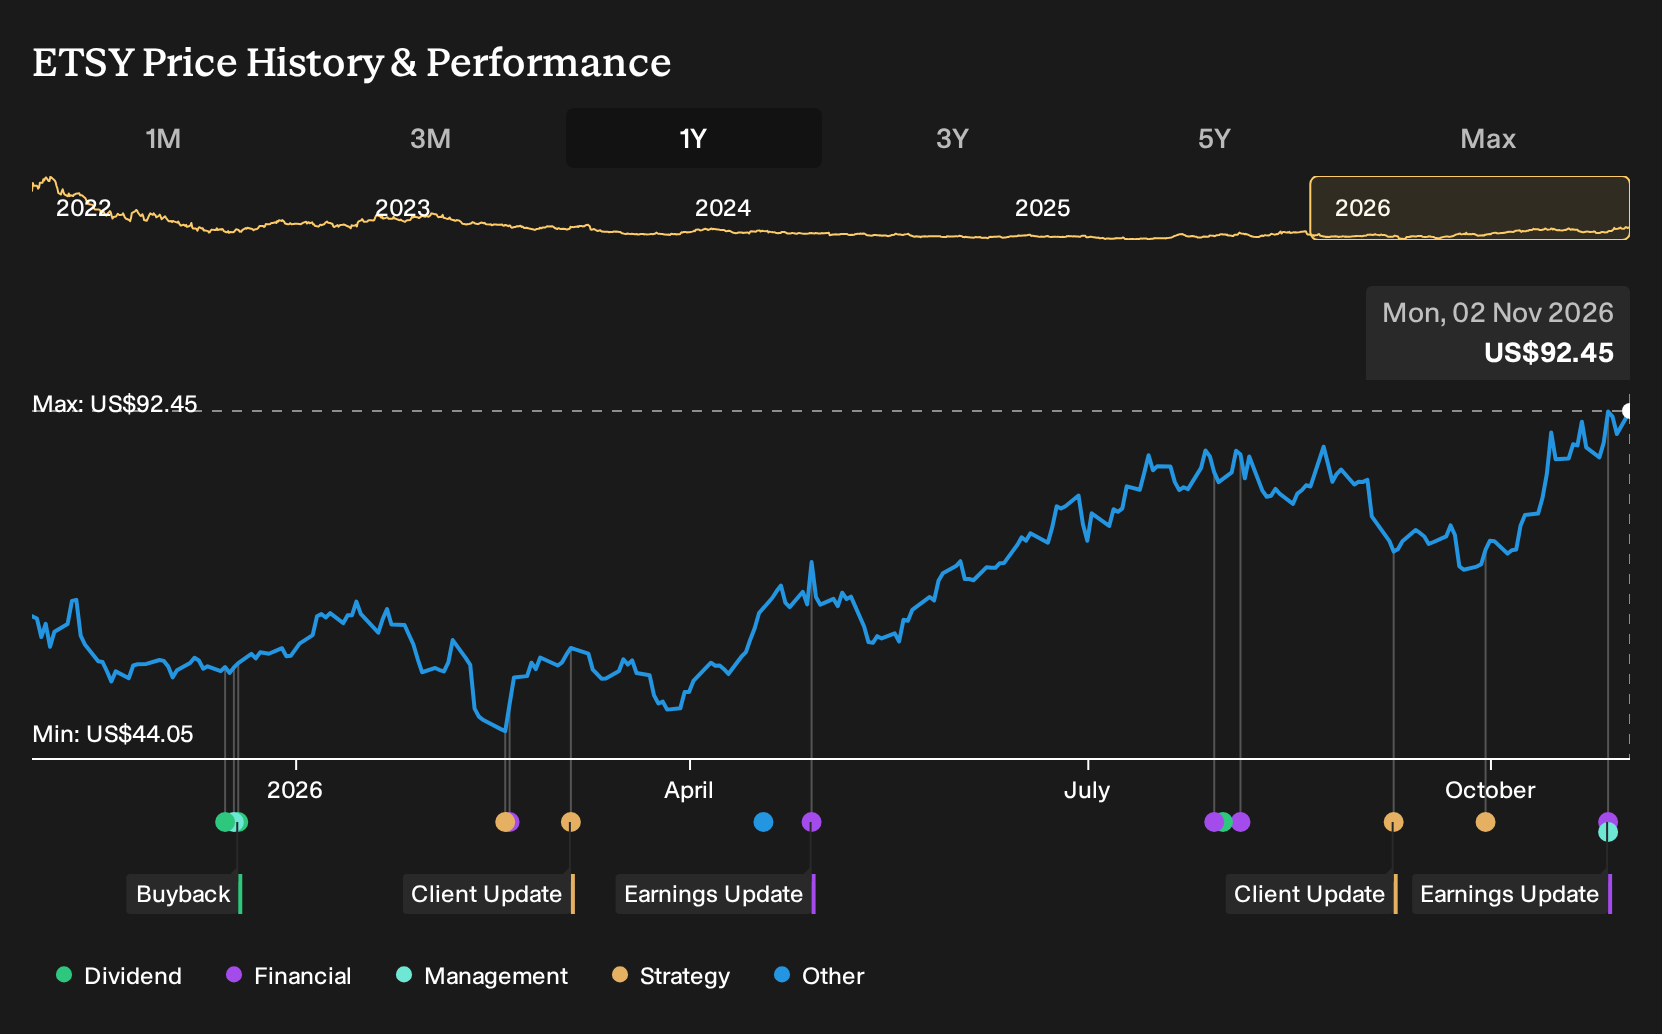
- Etsy reported third quarter 2026 sales of US$692.47 million and net income of US$853.52 million, and confirmed that CFO Lanny Baker will depart in March 2027 and remain as an advisor through July 2027.
- Management also disclosed that Etsy repurchased 7,724,384 shares for US$565.84 million under its existing buyback program, retiring 8.29% of the share count and highlighting the capital light nature of the marketplace model.
- We will assess how Etsy's investment narrative around engagement, profitability and capital returns is affected by the earnings results and the planned CFO transition.
Compare Etsy's buyback and earnings story with other capital light marketplaces by scanning our hand picked list of 19 high quality undiscovered gems that may be flying under most investors' radars.
Etsy Investment Narrative Recap
Etsy still asks you to believe in a focused marketplace that keeps buyers coming back through better discovery, personalization and app engagement, while protecting its brand from low quality or AI generated clutter. The recent quarter showed higher sales and net income, which supports that engagement story, but the real test remains whether active buyers and spending per buyer hold up.
The most important short term catalyst is execution on AI driven recommendations and app based interaction that could sustain GMS and advertising demand. The biggest risk stays the same: external AI shopping tools and lower quality listings could siphon away traffic or trust. The latest earnings do not materially change that balance.
The share repurchase update is the announcement that most directly ties into this earnings print. Etsy completed the buyback of 7,724,384 shares for US$565.84 million under the December 2025 authorization, retiring 8.29% of the share count. For a capital light marketplace, that kind of reduction can meaningfully change per share metrics if operating momentum persists.
For you as a shareholder, the repurchases make the quality of Etsy execution more important. Stronger profitability, like the US$853.52 million net income reported in Q3, flows over a smaller base. Any stumble in buyer engagement, pressure on take rates, or reputational damage from AI driven shopping shifts now carries more weight because there are fewer shares to absorb any earnings volatility.
Etsy Analyst Forecasts and Implied Earnings Path
Etsy's narrative projects US$3.3b revenue and US$561.4 million earnings by 2029. That profile rests on analysts assuming 3.4% yearly revenue growth and an earnings increase of about US$151.8 million from US$409.6 million today.
Uncover why Etsy's fair value is essentially consistent with its current price.
Exploring Other Perspectives
One alternate view says the bigger swing factor is not AI recommendation quality but seller fatigue. The most pessimistic analysts were only pencilling in about US$3.1b of revenue and roughly US$496.3 million of earnings by 2029 before this report. That is a tighter, more cautious Etsy story. Opinions clearly differ. It helps to compare several narratives that may shift as this earnings and buyback news is absorbed.
Explore 3 other Etsy fair value estimates, including one that suggests as much as 30% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Etsy research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Etsy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Etsy's overall financial health at a glance.
Looking For More Etsy Investment Ideas And Comparisons?
Etsy is only one way to express a view on capital light platforms and recurring customer engagement. If you want to pressure test your thesis and see how it stacks up against other businesses, the Simply Wall St Screener gives you a fast way to scan for different types of opportunities that fit your risk and income preferences.
- If you want to tilt toward companies that balance quality with attractive pricing, use the screener to track 34 high quality undervalued stocks that may line up better with your return hurdles.
- For investors who care more about resilience than excitement, you can filter for 29 resilient stocks with low risk scores that score well on stability and business durability metrics.
- If you are building a watchlist of stronger balance sheets to compare with Etsy over time, start with this curated list of solid balance sheet and fundamentals (24 results) and see which ones deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com