


- Amdocs is set to report quarterly earnings after market close on Tuesday, with analysts projecting 3.8% year on year revenue growth compared with a decline in the same quarter last year.
- The firm’s history of missing revenue estimates contrasts with analysts keeping forecasts largely steady, which puts extra focus on how execution and demand across telecom and media customers appear in this report.
- We will examine how Amdocs's investment narrative is shaped by this anticipated return to revenue growth after last year's quarterly decline.
Scan beyond Amdocs before this earnings update by comparing it with a hand picked pool of telecom and software peers in the 19 high quality undiscovered gems.
Amdocs Investment Narrative Recap
Amdocs appeals to shareholders who think telecom and media clients will keep relying on long contracts for cloud, billing and AI driven automation. The key short term question is simple: does this quarter confirm that demand is stabilising after last year’s revenue drop, with the expected 3.8% growth pointing to healthier project execution?
The biggest swing factor right now is how quickly aOS and AI projects scale from pilots into broad rollouts that support earnings quality. The main risk is still soft ordering from carriers or weaker guidance. This earnings print matters for sentiment, but it does not on its own change the long term thesis.
With earnings due after Tuesday’s close, the most relevant data point is the expected return to year on year revenue growth compared with the 9% decline in the same quarter last year. That pivot, if confirmed, feeds directly into the near term catalyst investors are watching, which is evidence that core operations are back on steadier footing.
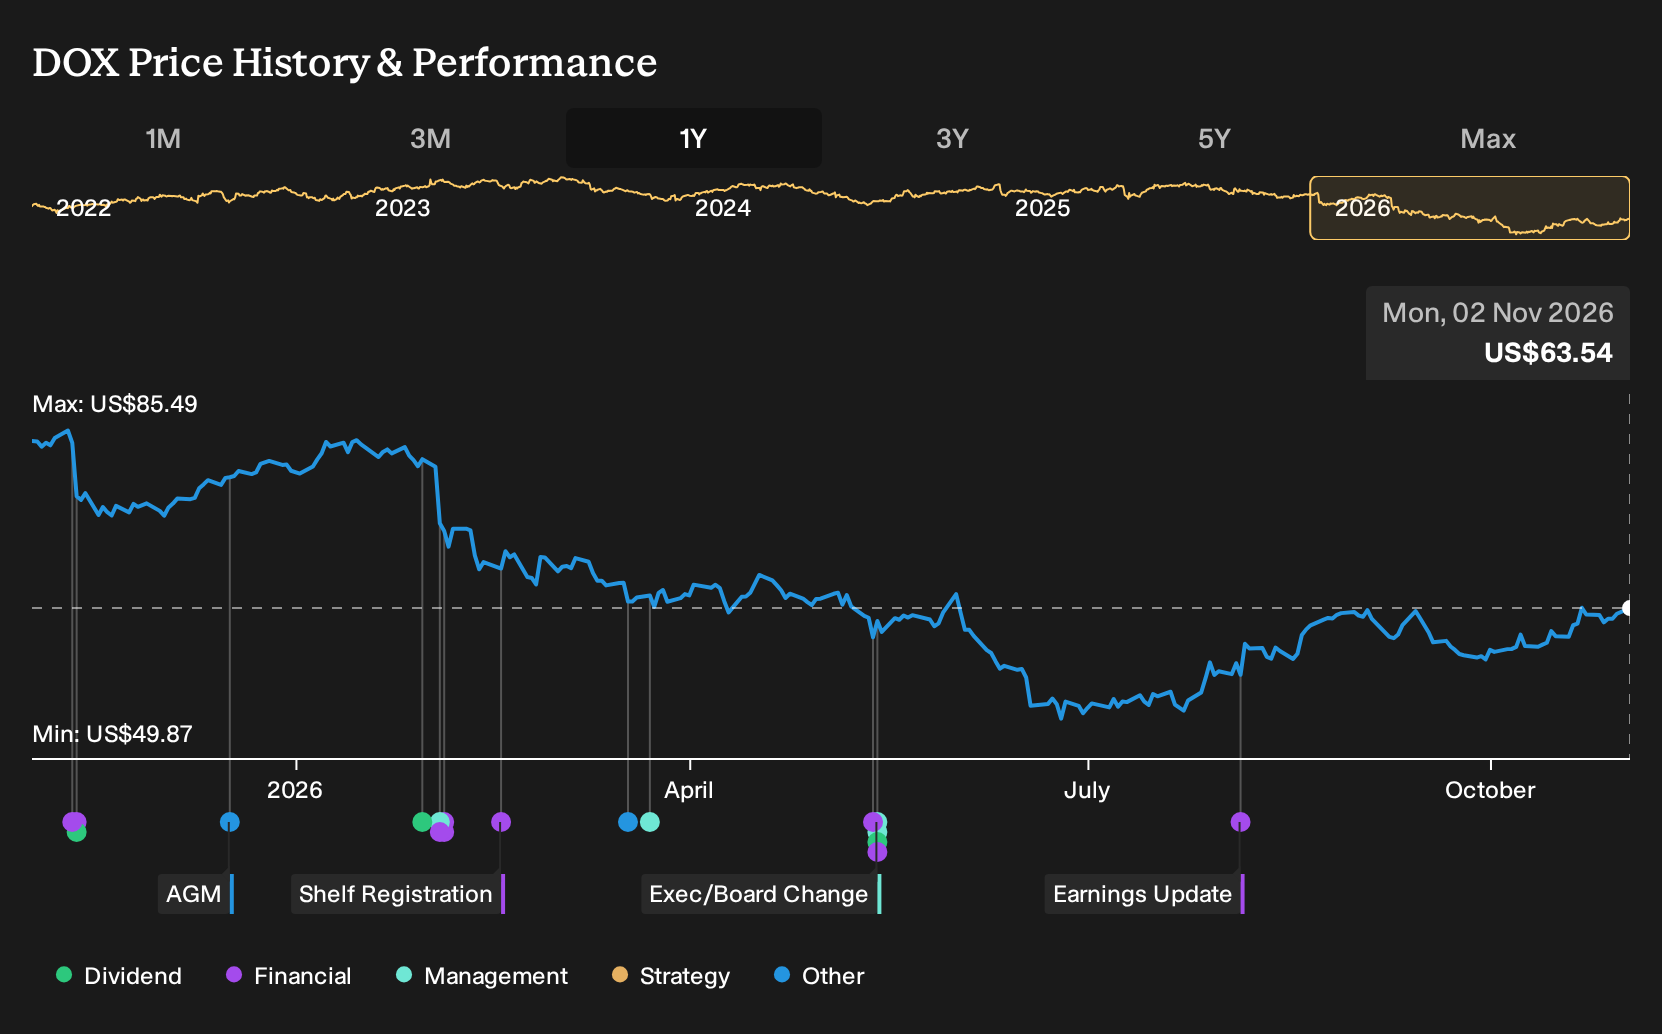
This update also sits against a share price that has fallen about 21.7% over the past year despite a sizeable US$4.28b 12 month backlog and ongoing contract activity. If reported results line up with the forecast improvement while guidance stays intact, it would speak to execution against that backlog. Any renewed shortfall or weaker outlook would keep the focus firmly on telecom spending risk and AI disruption concerns.
Amdocs Long Term Assumptions And Valuation Frame
Amdocs' narrative projects US$5.2b revenue and US$945.9m earnings by 2029. That path is built on analysts assuming 3.6% yearly revenue growth and an earnings increase of about US$490m from US$455.7m today.
Analysts are effectively sketching out a future where Amdocs roughly doubles profit over a few years while keeping top line expansion relatively modest. The starting point in that picture is current earnings of US$455.7m on a margin of 9.8%. The end point is US$945.9m of profit by 2029 at an 18.3% margin, which implies the business would convert a larger share of each sales dollar into net income even if revenue growth itself remains measured.
For the revenue side, the 3.6% annual growth assumption over the next three years sits close to the 3.8% near term sales increase currently pencilled in for the upcoming quarter. That keeps the long range model broadly consistent with the short term expectations around this earnings release. It also means the heavy lifting in the story comes less from acceleration in telecom spending and more from improved profitability as higher margin software, AI and cloud services deepen inside the existing backlog.
On the earnings line, moving from US$455.7m today to US$945.9m by 2029 asks Amdocs to add roughly US$490m of extra profit over that period. That is a large jump in absolute dollars, so the margin bridge from 9.8% to 18.3% matters more than small changes in revenue growth assumptions. Investors who buy into this scenario are effectively saying that operating efficiency, product mix and contract structure can do more of the work than raw top line acceleration.
The valuation framework in the consensus numbers adds another layer to what this upcoming print means for Amdocs. Forecasts connect that 2029 earnings of US$945.9m and projected US$5.2b revenue with a P/E of 10.5x, which is lower than both the current 13.4x multiple on the stock and the 22.0x level cited for the wider US IT group. The gap between those figures gives a sense of how much skepticism is already embedded around execution risk, telecom budgets and AI competition.
Price targets then translate those inputs into a fair value range rather than a single precise point. The consensus sits at US$79.25, while individual analysts span from US$63.00 up to US$105.00. Taken together with the current share price of US$58.36, the midpoint implies a 26.4% higher level than where the stock trades today, with the spread between bullish and cautious views flagging that confidence in the 2029 path is far from uniform.
For you as an investor, the practical question is how much of the 2029 scenario feels realistic. If the idea of US$5.2b in sales, US$945.9m of net income and a 10.5x P/E in that year seems conservative, then the current price may look undemanding. If you think margins could stall closer to the current 9.8% level or you doubt that telecom and media clients will support 3.6% yearly revenue expansion, then the consensus target range might feel rich and the current discount to it less compelling.
That is why this earnings update matters more as a checkpoint than as a verdict on Amdocs. Progress on margins, commentary on AI and aOS adoption, and any change to guidance all feed directly into whether the 3.6% growth path and near doubling of profit stay plausible. The more the reported numbers and outlook align with those building blocks, the more anchored the 2029 narrative becomes. Any stumble or reset, especially around profitability, would force a rethink of both the earnings trajectory and the multiples investors are prepared to pay for it.
Uncover why Amdocs' fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans heavily on telecom cost controls. In that storyline, Amdocs still reaches about US$5.2b of sales and roughly US$962.8m of earnings by 2029, yet the most cautious analysts only attach a US$63.00 target and an 8.1x P/E, reflecting a far more muted response to this week’s earnings update.
Explore 5 other Amdocs fair value estimates, including one that suggests it could be worth just $63.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Amdocs research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amdocs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amdocs' overall financial health at a glance.
Looking For More Investment Ideas Beyond Amdocs?
If the Amdocs story has sharpened your thinking but you want a broader watchlist, use this as a springboard into other opportunities with the Simply Wall St Screener. Mix different angles so you are not relying on a single type of company or one sector for your next idea.
- If you want balance sheet strength to be your starting point, focus on businesses from the list of solid balance sheet and fundamentals (24 results) that can better withstand tougher conditions.
- For investors who care most about paying a measured price for quality, scan the 34 high quality undervalued stocks and see which stocks combine strong fundamentals with more modest expectations.
- If you prefer to sleep a bit easier at night, build a shortlist from the 29 resilient stocks with low risk scores and concentrate on companies where risk scores are already on the lower side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com