


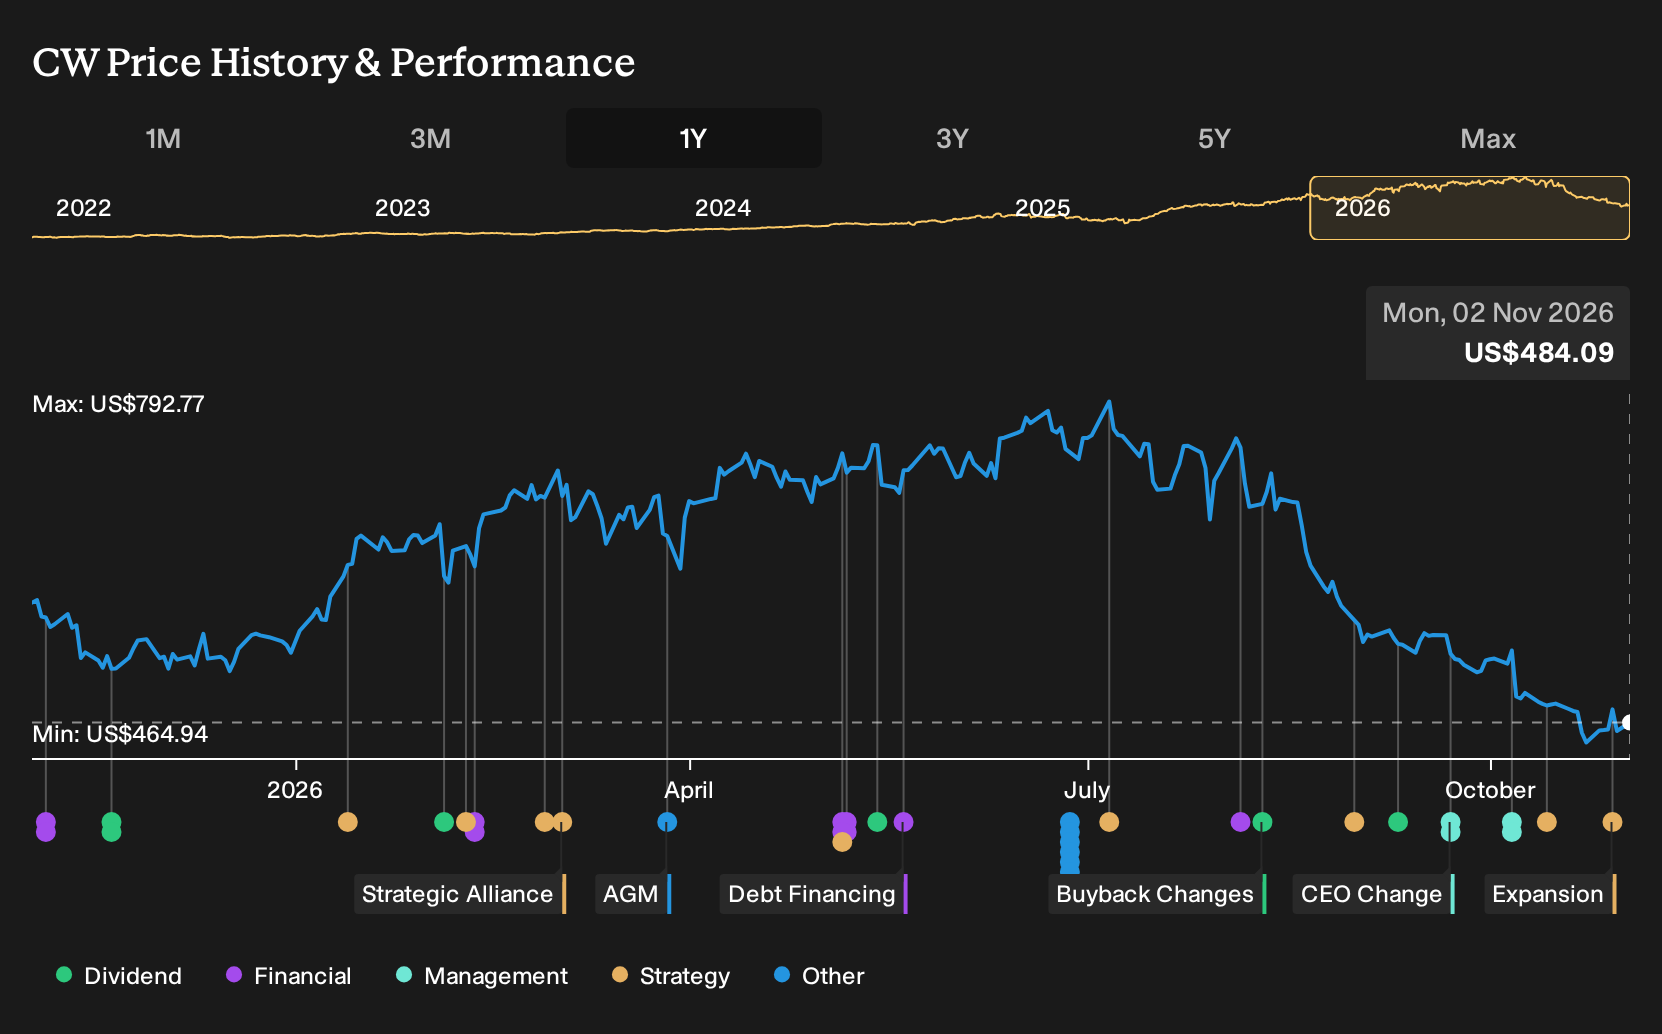
- Curtiss-Wright recently committed US$30 million to expand its Round Rock, Texas facility, aiming to increase Naval & Power manufacturing capacity and support nuclear and industrial applications.
- The build out of an Advanced Innovation Center, metrology lab, and project office in Round Rock points to heavier investment in engineering capabilities and complex instrumentation work rather than just more floor space.
- We will now look at how Curtiss-Wright’s investment narrative could shift with this expanded Texas manufacturing footprint and leadership reset.
Curtiss-Wright Investment Narrative Recap
To own Curtiss-Wright, you need to buy into a simple idea. The business is built around long-cycle defense and nuclear programs where contract visibility and execution discipline matter more than quarter to quarter swings. The Texas expansion and segment leadership reset both lean into that theme but do not instantly change the near term picture.
The key short term catalyst remains how effectively Curtiss-Wright converts its US$4.3b backlog into revenue and margins while absorbing higher growth CapEx and operating costs. The main risk is that large defense and nuclear customers slow orders or renewals, which could expose the current P/E premium and keep valuation concerns front and center.
The leadership overhaul into three Segment Presidents reporting to the new CEO sits closest to this expansion story. Naval & Power, Defense Electronics, and Aerospace & Industrial now have clearer accountability, which matters when Curtiss-Wright is committing US$30m to a site tied directly to nuclear and industrial work.
For you as a shareholder, the question is execution. If segment heads keep order quality, margin discipline, and capital allocation aligned with existing guidance, the Texas build out can support the nuclear resurgence and defense demand already embedded in expectations. If integration missteps occur, investors may focus more on contract timing risk and the already full P/E multiple.
Curtiss-Wright's narrative projects US$4.6b revenue and US$739.5 million earnings by 2029. This implies 8.1% yearly revenue growth and an earnings increase of about US$198.3 million from US$541.2 million today.
Uncover why Curtiss-Wright's fair value indicates a 41% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is how bullish analysts frame Curtiss-Wright’s nuclear exposure. They were already assuming revenue reaches about US$4.8b and earnings of roughly US$780.0 million by 2029. That is more optimistic than the consensus forecasts you saw earlier. With the Texas expansion now announced, those pre news views may evolve in different directions.
Explore 4 other Curtiss-Wright fair value estimates, including one that suggests as much as 80% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Curtiss-Wright research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Curtiss-Wright. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Curtiss-Wright's overall financial health at a glance.
Looking for more Curtiss-Wright style investment ideas?
If Curtiss-Wright’s mix of long-cycle programs and capital investment appeals to you, it can help to line it up against other opportunities with clear financial footing. The Simply Wall St Screener offers curated sets of companies filtered by cash generation, balance sheet strength, and income potential, so you can build a broader watchlist that fits your own risk and return preferences.
- If you want income to play a bigger role in your portfolio, scan a focused group of higher yielding candidates through 4 dividend fortresses that screen for both payout and resilience.
- For investors who prefer to stay on the front foot with risk, review a hand picked universe of steadier businesses via 29 resilient stocks with low risk scores and see which ones line up with your comfort level.
- When the goal is to back solid finances first and growth stories second, start with a curated list of solid balance sheet and fundamentals (24 results) so you are only comparing companies with stronger financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com