


- Monolithic Power Systems reported third quarter 2026 sales of US$1,202.41 million and net income of US$271.07 million, alongside new fourth quarter revenue guidance of US$1,315 million to US$1,385 million and a refreshed finance leadership team.
- The jump in earnings per share alongside higher nine month sales and profit points to firm demand across Monolithic Power Systems' end markets and gives investors fresh data on how the business is absorbing recent capacity and product investments.
- We will examine the ways in which Monolithic Power Systems' investment narrative is influenced by this quarterly performance and revenue outlook.
See how Monolithic Power Systems' latest guidance compares to peers by checking our curated list of 53 AI infrastructure stocks.
Monolithic Power Systems Investment Narrative Recap
To own Monolithic Power Systems, you effectively need to believe its heavy spend on capacity and new power products will be matched by lasting demand from AI data centers and a growing automotive pipeline. The latest quarter, with higher year to date sales and profit, plus Q4 revenue guidance of US$1,315 million to US$1,385 million, supports that utilization story in the near term.
The key short term swing factor is whether data center orders stay firm enough to keep new manufacturing commitments economically efficient. The biggest risk remains under absorption of that extended capacity, which would weigh on free cash flow, together with any fallout from ongoing investigations around customer orders and product quality.
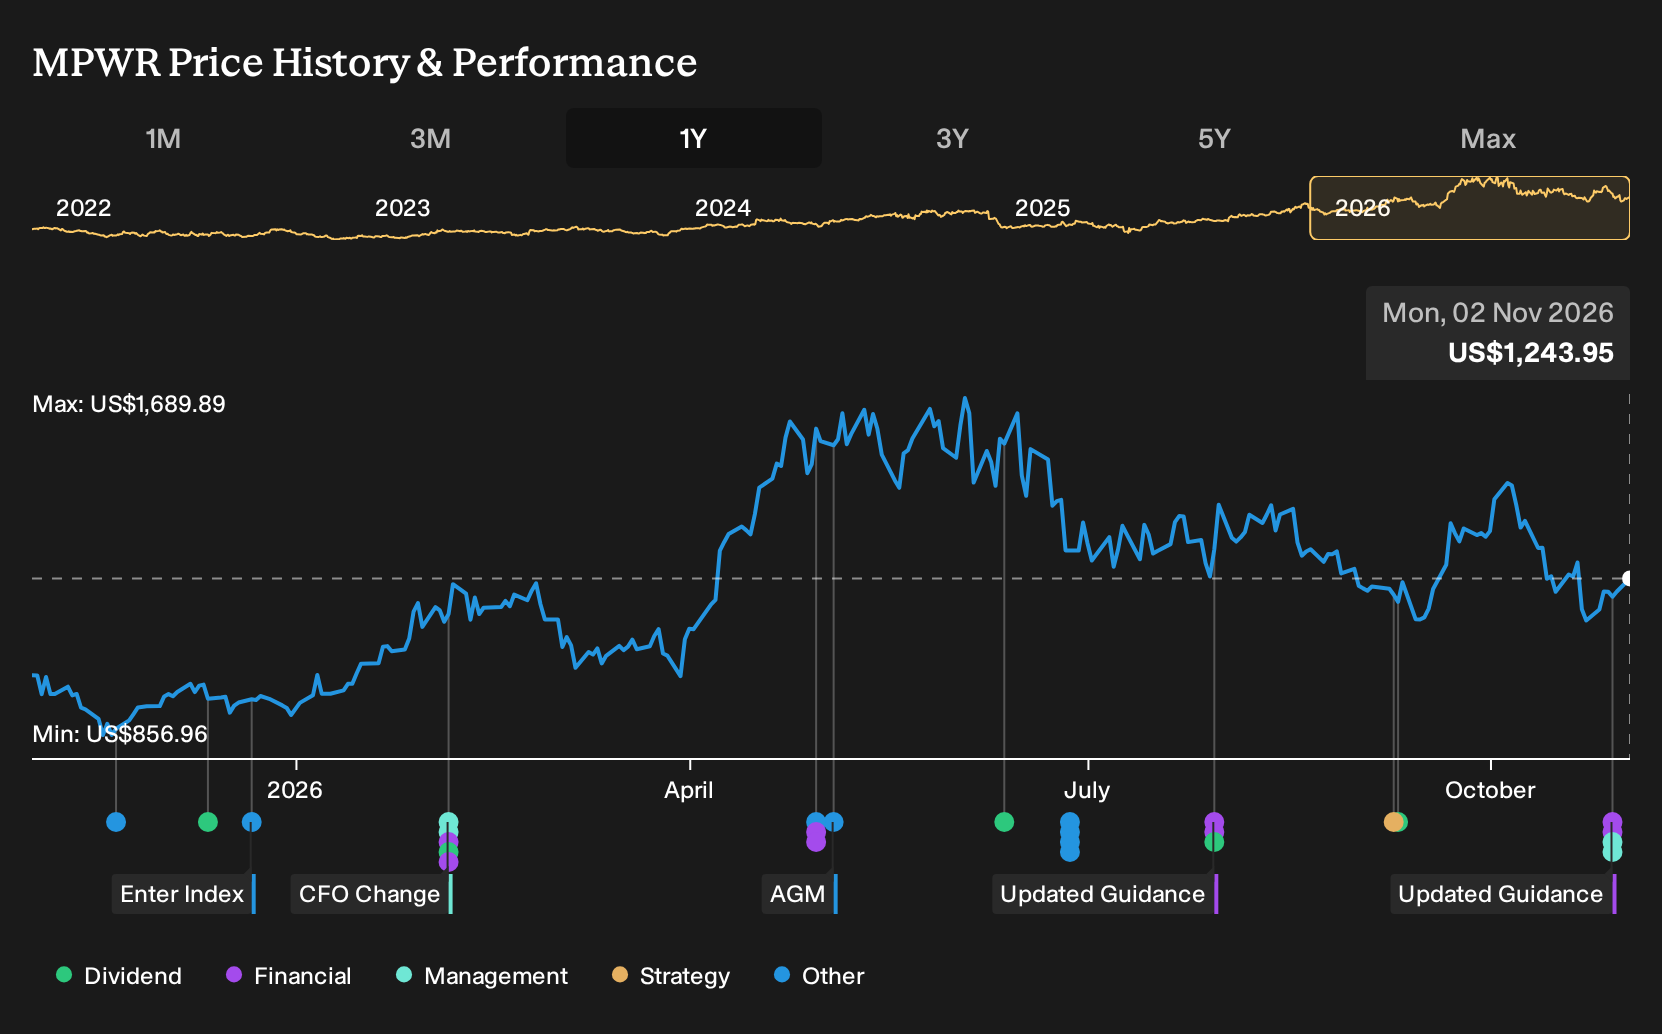
The most relevant recent development for this story is the appointment of Tony Balow as Chief Financial Officer on 29 October 2026, alongside Robert Dean moving into the Chief Accounting Officer role. This refresh comes just as Monolithic Power Systems scales toward a capacity plan linked to more than US$6b in annual revenue equivalents and a new 300mm partnership in Singapore.
For shareholders, the finance reshuffle sits close to the main catalyst and the main risk. Execution on the capacity build, the AI and automotive ramps, and the Singapore manufacturing agreement will depend heavily on tight capital allocation and cost control. A seasoned CFO and dedicated accounting lead may help the business manage cash, margin pressure and any legal or settlement costs tied to current investigations.
What The Analyst Case Implies For Monolithic Power Systems
Analysts sketch a fairly specific path for Monolithic Power Systems over the next few years. The consensus case ties the current AI and automotive story to a set of hard numbers on revenue growth, earnings power and valuation multiples that investors can test against their own expectations.
On the top line, the group of covering analysts is working with forecast revenue growth of 28.3% a year over the next three years. That pace reflects their view of what the existing AI data center exposure, automotive pipeline and broader power portfolio could support if current projects continue to scale and new designs keep converting into production volume.
Earnings today are placed at US$801.9 million, with consensus forecasts pointing to US$2.1b of profit by 2029. That implies an increase of about US$1.3b in earnings from the current level. Reaching the assumed 30.2% margin, compared with the 24.5% margin cited for today, would require both higher sales and a lift in profitability.
The same reports highlight a wide spread between bullish and cautious views. At the high end, some analysts see earnings closer to US$2.5b by 2029, while the most conservative models sit around US$1.8b. That range underlines how sensitive the Monolithic Power Systems story is to utilization of new capacity, the durability of AI related demand and any impact from investigations or customer concentration.
Assumptions on valuation are just as specific. The consensus scenario requires Monolithic Power Systems to trade on a P/E of 63x those 2029 earnings, compared with 69.9x today and a current sector level quoted at 42.4x for US semiconductor peers. In this framework, the thesis leans on both growth in earnings and an elevated multiple relative to the wider industry, even if that multiple moderates a little from the current level.
Forecasts in the report also factor in share issuance, with analysts expecting the share count to expand by about 2.58% annually over the next three years. That dilution becomes important for any investor focusing on per share earnings or long term total returns, since higher absolute profit still needs to be spread across more stock.
To bring all of these moving pieces back to today, the analysis uses an 11.2% discount rate. That discount rate influences what those projected 2029 cash flows and earnings are worth in present terms and helps explain why the implied valuation multiples might differ from simple peer averages or historical levels.
On top of the earnings path, the analysts have settled on a consensus price target of US$1,799.80 per share. Individual targets span from US$1,500 at the low end to US$2,100 at the high end, reflecting different views on how effectively Monolithic Power Systems can turn its capacity plan and product roadmap into cash flow over time.
Relative to a quoted share price of US$1,140.12, that average target is 36.7% higher. For a potential buyer or holder, the practical question is how comfortable you are with the embedded expectations around AI data center demand, automotive ramp timing, free cash flow pressure from the Singapore partnership and any overhang from ongoing investigations.
Monolithic Power Systems' narrative projects US$6.9b revenue and US$2.1b earnings by 2029. This rests on revenue growing at 28.3% a year and an earnings increase of roughly US$1.3b from the current US$801.9 million base.
Uncover why Monolithic Power Systems' fair value indicates a 45% potential upside to its current price. This discount could close faster than many investors expect.
Exploring Other Perspectives
One alternate angle on Monolithic Power Systems focuses on free cash flow strain from the Singapore capacity build. The most cautious analysts were working off revenue reaching about US$6.2b and earnings of US$1.8b by 2029, before this latest guidance and CFO change. That is a slower ramp. Use this range to stress test your own view and consider how these opinions may shift after the new numbers.
Explore 4 other Monolithic Power Systems fair value estimates, including one that suggests as much as 22% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Monolithic Power Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Monolithic Power Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Monolithic Power Systems' overall financial position at a glance.
Looking For More Investment Ideas Beyond Monolithic Power Systems?
If the Monolithic Power Systems story has sharpened your view on AI hardware and capacity driven growth, the next step is to widen your watchlist. The Simply Wall St Screener can help you quickly surface other stocks that match the balance of quality, risk and income you want, so you are not relying on a single bet.
- For investors who want potential upside paired with quality fundamentals, start with a curated group of 19 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation and steadier return profiles matter most to you, filter for 29 resilient stocks with low risk scores that combine stronger balance sheets with lower overall risk scores.
- Income focused investors can concentrate on yields and payout resilience by scanning 4 dividend fortresses that aim to pair higher dividends with durable business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com