


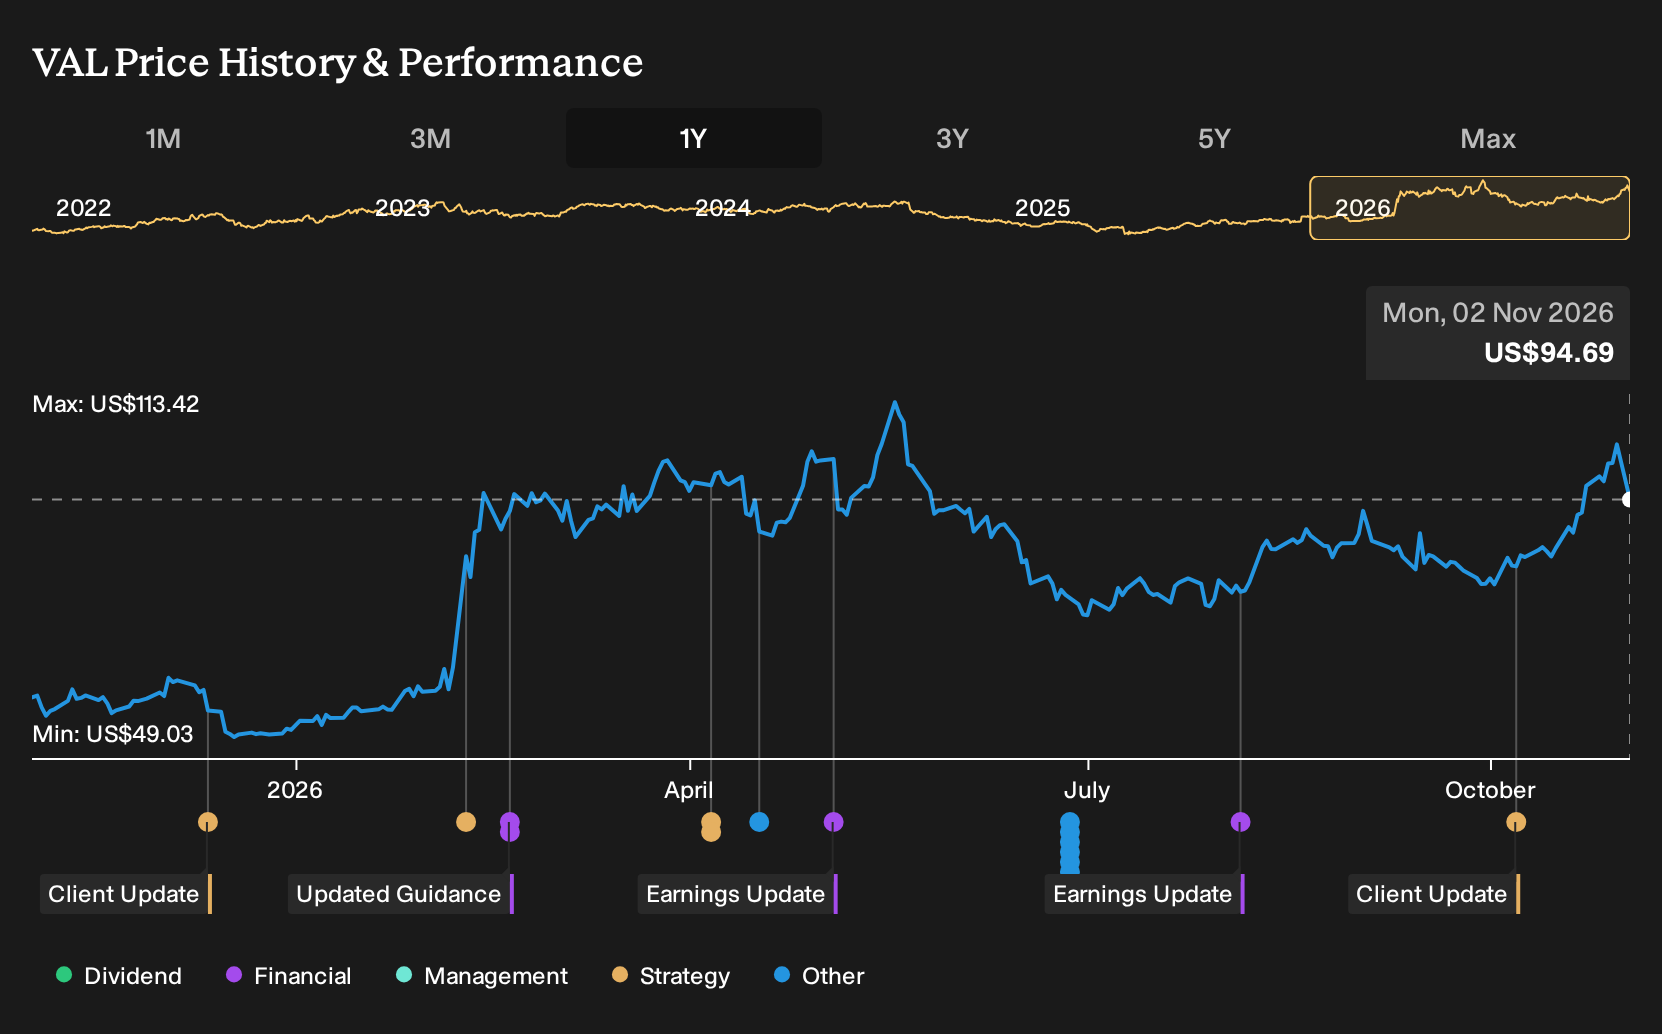
- Valaris Limited reported third quarter 2026 results with revenue of US$593.6 million, slightly below the prior year, while net income fell to US$46.1 million and diluted EPS from continuing operations came in at US$0.66, missing analyst expectations.
- The quarter showed that strong offshore drilling demand and a revenue beat did not translate into cash generation, as margins compressed, free cash flow moved into negative territory and profitability weakened despite a robust contracted rig fleet.
- We will look at how Valaris's investment narrative holds up when strong revenue is accompanied by much weaker earnings and cash generation.
Scan beyond Valaris and compare its latest earnings story with hand picked offshore and energy contractors by checking the list of solid balance sheet and fundamentals (24 results) that pair asset quality with healthier cash generation.
Valaris Investment Narrative Recap
To own Valaris, you really need to believe that a tight offshore rig market and a deep contract pipeline can still translate into solid utilisation, pricing and, crucially, cash generation. The Q3 print challenges that belief at the edges. Revenue tracked roughly flat year on year around US$593.6 million, yet profit dropped sharply and free cash flow slipped into the red, so short term confidence in earnings quality takes a hit.
The biggest near term catalyst remains how well Valaris converts its high specification fleet and backlog into clean operating income and cash, especially as it moves through 2026 opportunities. The key risk right now is that cost inflation, idle days or operational hiccups keep compressing margins even if reported sales hold up. If that happens, the latest earnings miss becomes a more material warning signal rather than a one off bump.
The earnings announcement for the quarter ended September 30, 2026 is the clearest reference point here. Management posted US$593.6 million of revenue, broadly in line with the prior year, but net income of US$46.1 million compared with US$188.1 million a year earlier. Diluted EPS from continuing operations landed at US$0.66 versus US$2.65 to US$2.66 previously, and below the US$1 analyst benchmark highlighted in the summary.
For you as a shareholder, that single report ties straight back into the core catalysts. The offshore opportunity set and Transocean merger case both lean on the idea that utilisation, day rates and cost synergies ultimately flow through to sustainable earnings and free cash flow. When a quarter delivers weaker profitability despite firm demand indicators, it increases execution risk around those catalysts and puts more pressure on coming fleet status updates to show progress rather than just potential.
What The Valaris Forecasts Are Asking You To Believe
Valaris is being modeled into a very different earnings profile than the one shown in the latest quarterly report. Analysts are incorporating revenue expansion of 8.2% a year over the next 3 years, yet they also expect profit margins to compress sharply from 44.0% today to 3.8% by around 2029. That combination implies a larger operation in dollar terms, but a far thinner slice of each sales dollar dropping through to the bottom line.
The consensus forecast calls for earnings to be US$103.1 million by 2029, compared with US$939.6 million of earnings today. That is a drop of about US$836.5 million in profit, even though the same analyst group is using US$2.7 billion of projected revenue and a higher P/E multiple of 56.4x on those future earnings to support a price target of US$67.43. In other words, the current modeling framework has investors paying more for the possibility that a lower margin, lower earnings Valaris still supports a much richer valuation multiple.
Valaris' narrative projects US$2.7 billion in revenue and US$103.1 million in earnings by 2029. This requires 8.2% yearly revenue growth and an earnings decrease of about US$836.5 million from US$939.6 million today.
Uncover how Valaris' fair value indicates a 29% potential downside to its current price, suggesting that the current premium may not hold.
Exploring Other Perspectives
One bullish twist focuses on cash generation. Before this Q3 report, the most optimistic analysts were modeling about US$2.8b of revenue and US$481.6 million of earnings by 2029, with a price target near US$104. That camp saw Valaris converting backlog into stronger free cash flow, so this weaker quarter may prompt sharp revisions.
Explore 4 other Valaris fair value estimates, including one that suggests up to 98% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Valaris research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Valaris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Valaris' overall financial health at a glance.
Looking For More Ideas Beyond Valaris?
If the Valaris story has sharpened your thinking and you want to widen your watchlist, it can help to scan for companies that match the kind of balance sheets, cash generation and income profiles you are comfortable owning.
- For investors focused on financial resilience, start with companies that pair sturdy leverage profiles and liquidity with consistent fundamentals through the 29 resilient stocks with low risk scores.
- If you care most about getting paid to wait, consider businesses that combine higher yields with balance sheets that look built to sustain those payouts in the 4 dividend fortresses.
- When you want to look past the usual tickers and hunt for quality where fewer people are looking, the 19 high quality undiscovered gems can surface candidates with stronger fundamentals that might still be underfollowed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com