


Regal Rexnord (RRX) is back in focus after its board declared a regular quarterly dividend of $0.35 per share, ahead of an earnings report that has investors watching revenue expectations closely.
At a share price of $160.93, Regal Rexnord has bounced 2.35% in the last session and gained 6.94% over the past week, yet the 90 day share price return is down 26.86%, even as the 1 year total shareholder return of 18.49% and 3 year total shareholder return of 63.43% point to momentum that has built over time and now depends on how the upcoming earnings and dividend decision shape expectations around future execution and risk.
Compare Regal Rexnord's setup with other industrials by scanning 43 power grid technology and infrastructure stocks that could react just as sharply to upcoming earnings and dividend news.
Regal Rexnord has pulled back hard over 90 days yet still carries a solid multi year return profile. Is the recent reset creating fresh upside, or did most of the opportunity already play out earlier in the cycle?
Most Popular Narrative: 30% Undervalued
On the most followed view, Regal Rexnord screens as undervalued, with a fair value estimate of $231.10 against the recent $160.93 close. That valuation gap anchors the thesis around how much of the order backlog and margin plan investors choose to credit.
Accelerating project wins and order strength in Regal Rexnord's Automation & Motion Control and Industrial Powertrain Solutions segments, including double digit order growth and higher shippable backlog into 2027, are expected to convert existing longer cycle and blanket orders into future revenue and support operating leverage.
See why 16 investors see Regal Rexnord as 30% undervalued.
Result: Fair Value of $231.10 (UNDERVALUED)
Still, rare earth supply constraints and ongoing tariff and cost pressures could derail the Regal Rexnord margin story that underpins this narrative of being 30% undervalued.
Find out about the key risks to this Regal Rexnord narrative.
Another View: Regal Rexnord Looks Expensive On Earnings
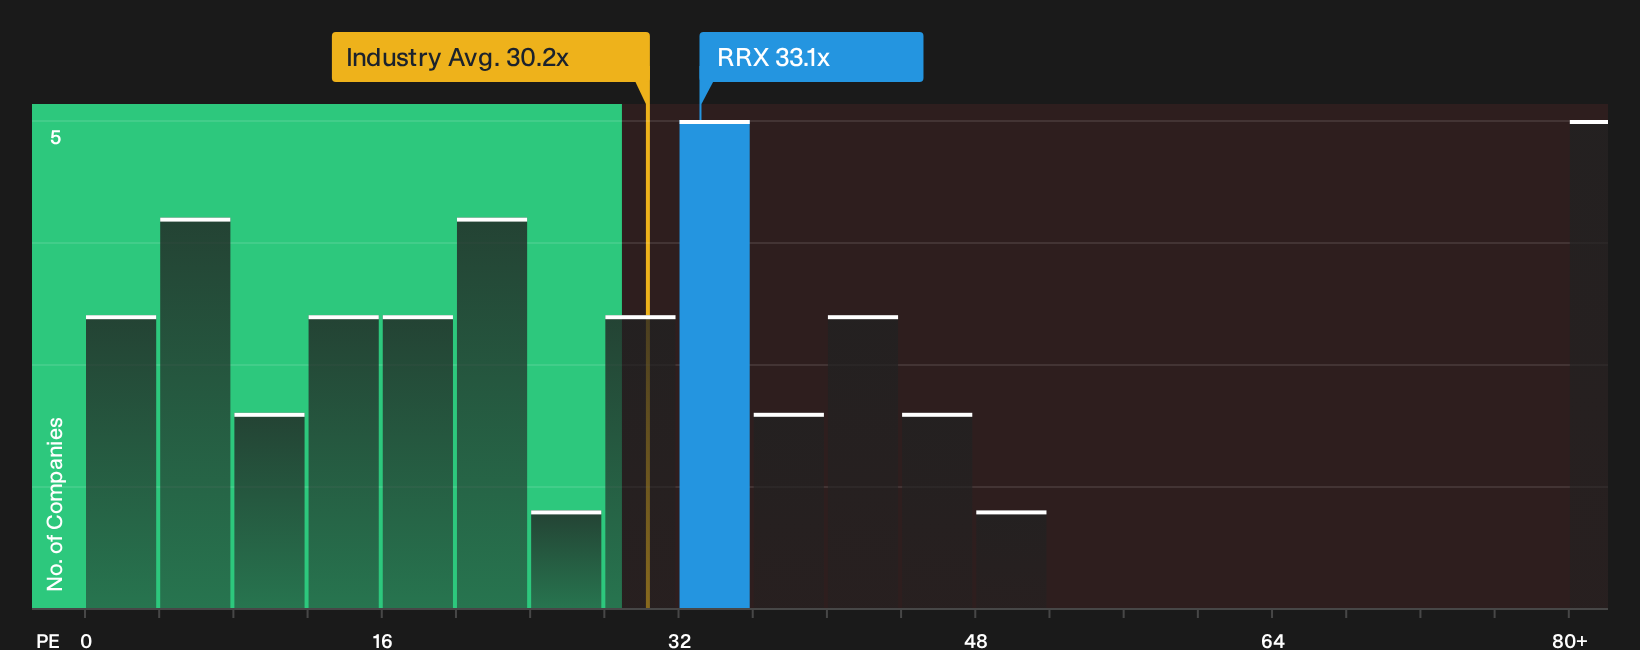
There is a catch. On a simple earnings yardstick, Regal Rexnord trades on a P/E of 33.1x, which is higher than the US Electrical industry at 30.2x, the peer average at 31.3x, and above a fair ratio of 29.9x that the market could move toward. That richer multiple can limit room for error if execution on margins or cash flow slips, so how much premium are you comfortable paying for this story?
For a closer look at how the current pricing stacks up against earnings and peers, including a breakdown of that P/E premium, See what the numbers say about this price — find out in our valuation breakdown.
Use this as a cross check against the broader industrials universe before you commit fresh capital, especially when other companies with similar profiles may trade on lower P/E levels.
Next Steps
Mixed signals around Regal Rexnord's valuation and risk reward profile can pull you in both directions, so move quickly, pull up the underlying charts and filings, and weigh the 3 key rewards and 1 important warning sign
Looking for more Regal Rexnord sized ideas?
If Regal Rexnord has you thinking harder about valuation, dividends, and risk, do not stop here. Broader idea hunting now could shape your next few years.
- Target resilience first by scanning a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stressing cash or leverage.
- Hunt for mispriced quality using a 19 high quality undiscovered gems that flags businesses with fundamentals the wider market may be ignoring.
- Anchor your income plan by reviewing a 4 dividend fortresses built around higher yields and payouts backed by stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com