


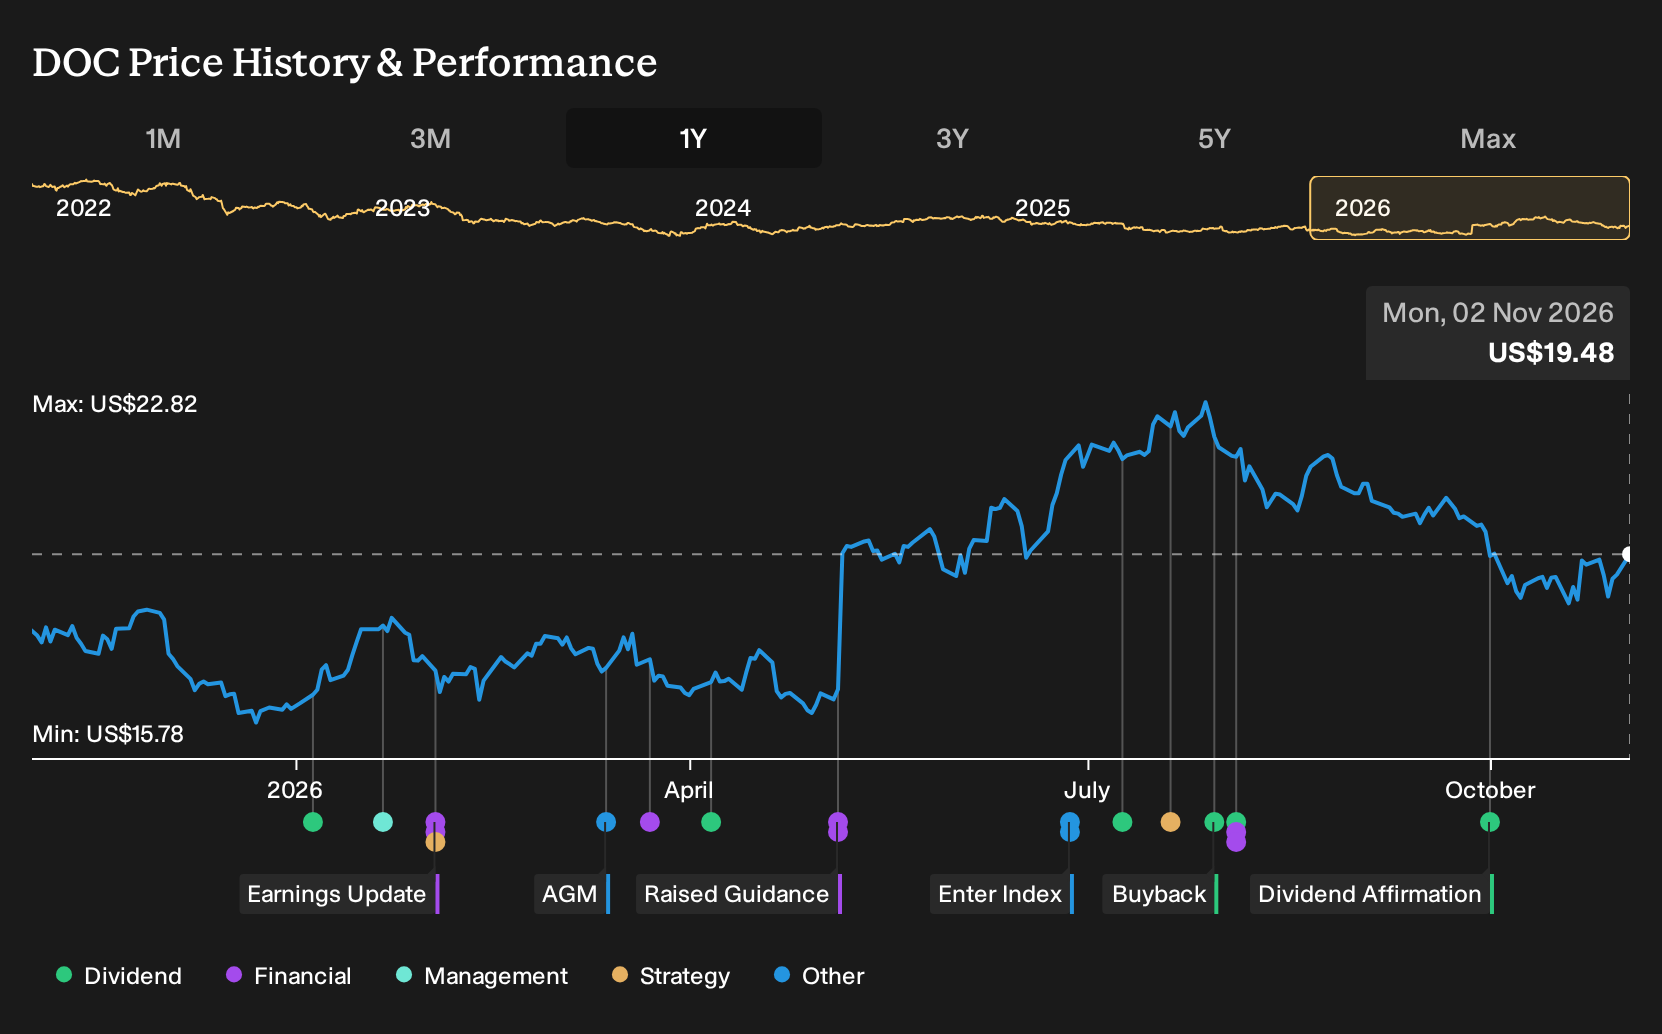
- Healthpeak Properties reported third quarter 2026 results with revenue of US$820.89 million and net income of US$17.26 million, compared with a loss in the prior year period.
- The real estate investment trust combined stronger outpatient medical and lab performance with higher earnings guidance, a new US$500 million term loan facility and a declared dividend, indicating an active approach to funding and operations.
- We will now look at how Healthpeak Properties' stronger than expected revenue and earnings might influence the broader investment narrative.
Review how Healthpeak Properties’ latest earnings compare with peers and identify other real estate opportunities with resilient balance sheets using our curated list of solid balance sheet and fundamentals (24 results)
Healthpeak Properties Investment Narrative Recap
To own Healthpeak Properties, you need to be comfortable with a healthcare REIT that leans on outpatient medical, senior housing and life science assets, each with different cycles. The big short term swing factor remains how quickly the lab and life science portfolio can stabilize, because that segment still influences overall net operating income.
The latest quarter showed higher revenue and a move from a loss to a profit, which supports confidence in the outpatient and senior housing story. It does not fully settle the key risk, which is slower recovery in life science NOI alongside interest costs that are not well covered by earnings.
The most relevant update here is the new US$500 million unsecured delayed draw term loan facility. This expands Healthpeak Properties' financial flexibility at a time when the REIT is relying on capital recycling, joint ventures and acquisitions to reshape the portfolio and support funds from operations.
Extra liquidity matters for the current catalysts. Outpatient medical leasing and Janus Living senior housing growth both require ongoing investment, while any setback in lab leasing or deal activity could pressure cash flow and leverage. The facility gives management more room to execute, although it also keeps the spotlight on interest coverage and balance sheet discipline.
Healthpeak Properties' current analyst narrative points to revenue of US$3.6b and earnings of US$145.5 million by 2029, based on an assumed 6.7% yearly revenue growth rate. That outcome would represent an earnings decline of about US$97.2 million from US$242.7 million today, even as the business is expected to grow its top line over the same period.
Uncover how Healthpeak Properties' fair value indicates a 16% potential upside to its current price, which could narrow quickly as earnings expectations reset.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a faster life science recovery for Healthpeak Properties. Before this earnings release they were modelling revenue of about US$4.0b and earnings of roughly US$220.7 million by 2029, far above the most cautious forecast of US$41.4 million. Use this spread as a reminder to compare several viewpoints and then decide which story you find more convincing as fresh quarterly numbers feed into updated models.
Explore 4 other Healthpeak Properties fair value estimates, including one that suggests the potential for as much as 90% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Healthpeak Properties research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Healthpeak Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Healthpeak Properties' overall financial health at a glance.
Looking for more ideas beyond Healthpeak Properties?
If Healthpeak Properties has sharpened your thinking about risk, income and balance sheet strength, it can be useful to line it up against a wider watchlist built around the traits you care about most.
- For investors who want potential upside with a margin of safety, start by scanning companies that screen as attractively priced relative to their fundamentals using our 34 high quality undervalued stocks.
- If capital preservation comes first for you, focus on businesses with sturdier finances and lower overall risk profiles through our 29 resilient stocks with low risk scores.
- When the goal is to uncover less crowded opportunities with solid underlying quality, broaden your research with our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com