


- Globe Life released third quarter 2026 results showing higher revenue compared with a year earlier, while earnings per share from continuing operations were slightly lower. The company also issued detailed 2026 and 2027 guidance for premium revenue, sales across business lines, and net operating earnings per diluted share.
- Management broke out expected 2027 performance by segment, pointing to relatively faster health premium and Liberty National growth than life premiums. This gives investors clearer visibility into where Globe Life expects its future business mix to shift.
- We will look at how Globe Life's detailed 2026 and 2027 premium revenue guidance reshapes the investment narrative around growth drivers.
Compare Globe Life's guided growth mix with a curated 34 high quality undervalued stocks that already reflect strong cash flows and balance sheets supporting their earnings targets.
Globe Life Investment Narrative Recap
To own Globe Life, you need to believe management can keep growing premium revenue while controlling claims and expenses in its core life and supplemental health lines. The latest guidance, calling for 2026 total premium growth of about 6.5% and normalized EPS growth of roughly 8%, broadly supports that operating thesis rather than reshaping it.
The near term swing factor is still execution on health underwriting and claims volatility, especially as health premium growth is guided well above life. The main risk remains pressure on margins and book value if health obligations, prior period adjustments, or direct to consumer softness persist. This guidance does not remove that concern.
The most relevant update is Globe Life's detailed 2027 outlook for premium mix and net operating earnings per share of US$16.10 to US$17.10. At the midpoint, management projects total premium growth of 6% to 8%, with life premiums in the low single digits and health premiums in the mid teens. This reinforces health as the key volume driver.
That tilt matters for catalysts. A lot now rests on health lines such as Liberty National, Family Heritage and United American delivering the low double digit and high single digit sales growth ranges that the company laid out, while claims stay manageable. If that occurs and the Bermuda reinsurance and AI cost initiatives track to plan, the business has several levers to support its earnings guidance.
Globe Life's analyst narrative points to revenue of US$7.5b and earnings of US$1.4b by 2029, based on an assumed 6.0% yearly gain in revenue and an earnings increase of about US$200m from current earnings of US$1.2b.
Uncover why Globe Life's fair value indicates a potential 18% upside to its current price that could narrow quickly.
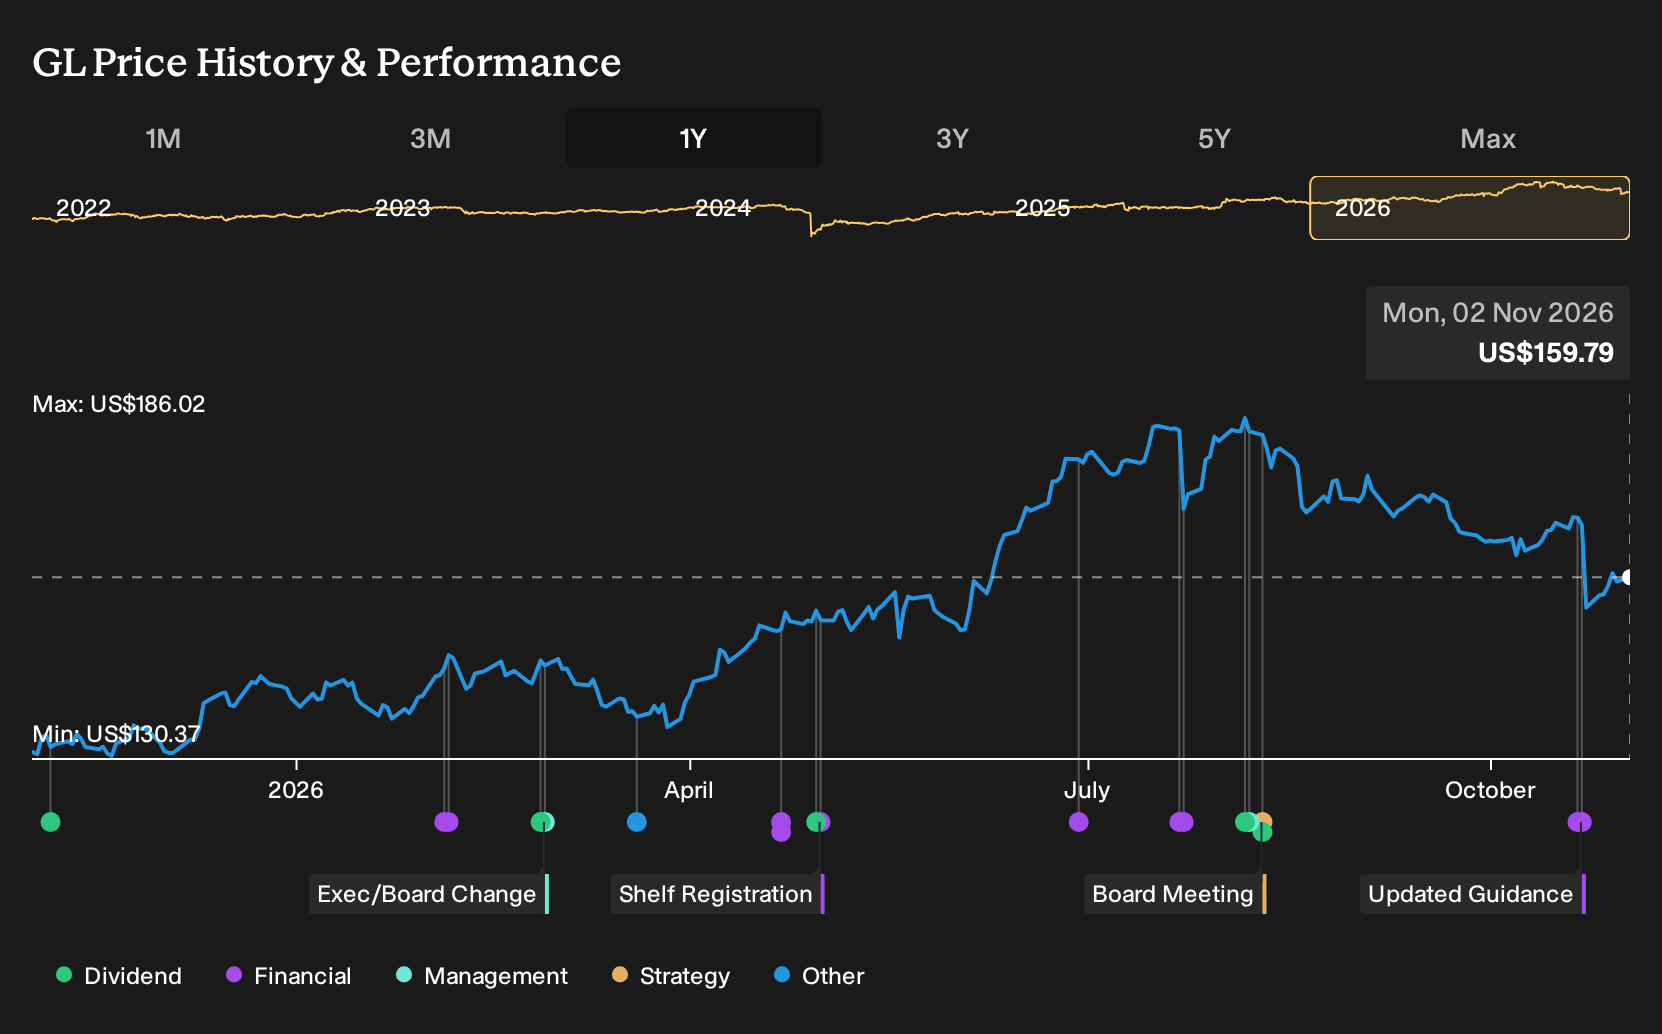
Exploring Other Perspectives
One alternate view on Globe Life leans hard into the buyback story. The most optimistic analysts were modeling revenue of about US$7.7b and earnings of roughly US$1.4b by 2029, helped by steady repurchases. Those projections predate the latest 2026 and 2027 guidance, so you should expect that narrative to evolve from here.
Explore 3 other Globe Life fair value estimates, including one that suggests there could be as much as 123% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Globe Life research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Globe Life. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Globe Life's overall financial health at a glance.
Looking for more investment ideas beyond Globe Life?
Once you have a view on Globe Life, it helps to line it up against a broader watchlist so you can see where the most compelling risk and reward profiles really sit.
- If resilience matters most to you, start with a basket of companies screened for sturdier risk profiles through a 29 resilient stocks with low risk scores that can help you focus on steadier performers.
- If dependable income is the priority, check out a curated set of higher yielding payers via a 4 dividend fortresses designed for investors who want returns driven by distributions as well as price moves.
- If you want solid balance sheets backing up the story, compare Globe Life with a list of solid balance sheet and fundamentals (24 results) and see which businesses pair financial strength with consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com