


Why Dropbox Stock Is Back In Focus
Dropbox (DBX) moved back onto investors' radar after the company reaffirmed its third quarter 2026 revenue guidance while announcing a 9% global workforce reduction and the upcoming departure of its Chief Technology Officer.
Across the past year, Dropbox has combined a 32.34% year to date share price return with a 20.0% 1 year total shareholder return. This suggests momentum is still positive even after the recent 1 day and 7 day pullback as investors weigh the reaffirmed guidance alongside job cuts and the CTO exit.
Scan how Dropbox compares with other software players reacting to fresh guidance and cost cuts by reviewing our hand picked 34 high quality undervalued stocks right now.
Dropbox now trades above the average analyst target, while a separate fair value model indicates nearly a 50% discount. After this latest move and guidance update, where does a reasonable estimate actually land?
Most Popular Narrative: 55% Overvalued
Dropbox closed at $35.64 while the most followed narrative pegs fair value at $23.00. This implies the stock price already bakes in a lot of success and leaves limited room for disappointment if things do not go to plan.
Dropbox is embedding AI features like Dash intelligence across its Teams base while guiding to gross margin of about 81.5% for 2026. If AI related compute costs rise faster than monetization or infrastructure efficiencies, the pressure on gross margin could be greater than implied and weigh on net margins and earnings.
See why 0 investors see Dropbox as 55% overvalued.
Result: Fair Value of $23.00 (OVERVALUED)
Still, if Dropbox converts heavy engagement in Dash into paid add ons and continues retiring shares with strong free cash flow, this bearish narrative could weaken.
Find out about the key risks to this Dropbox narrative.
Another View: Dropbox On Earnings And Cash Flow
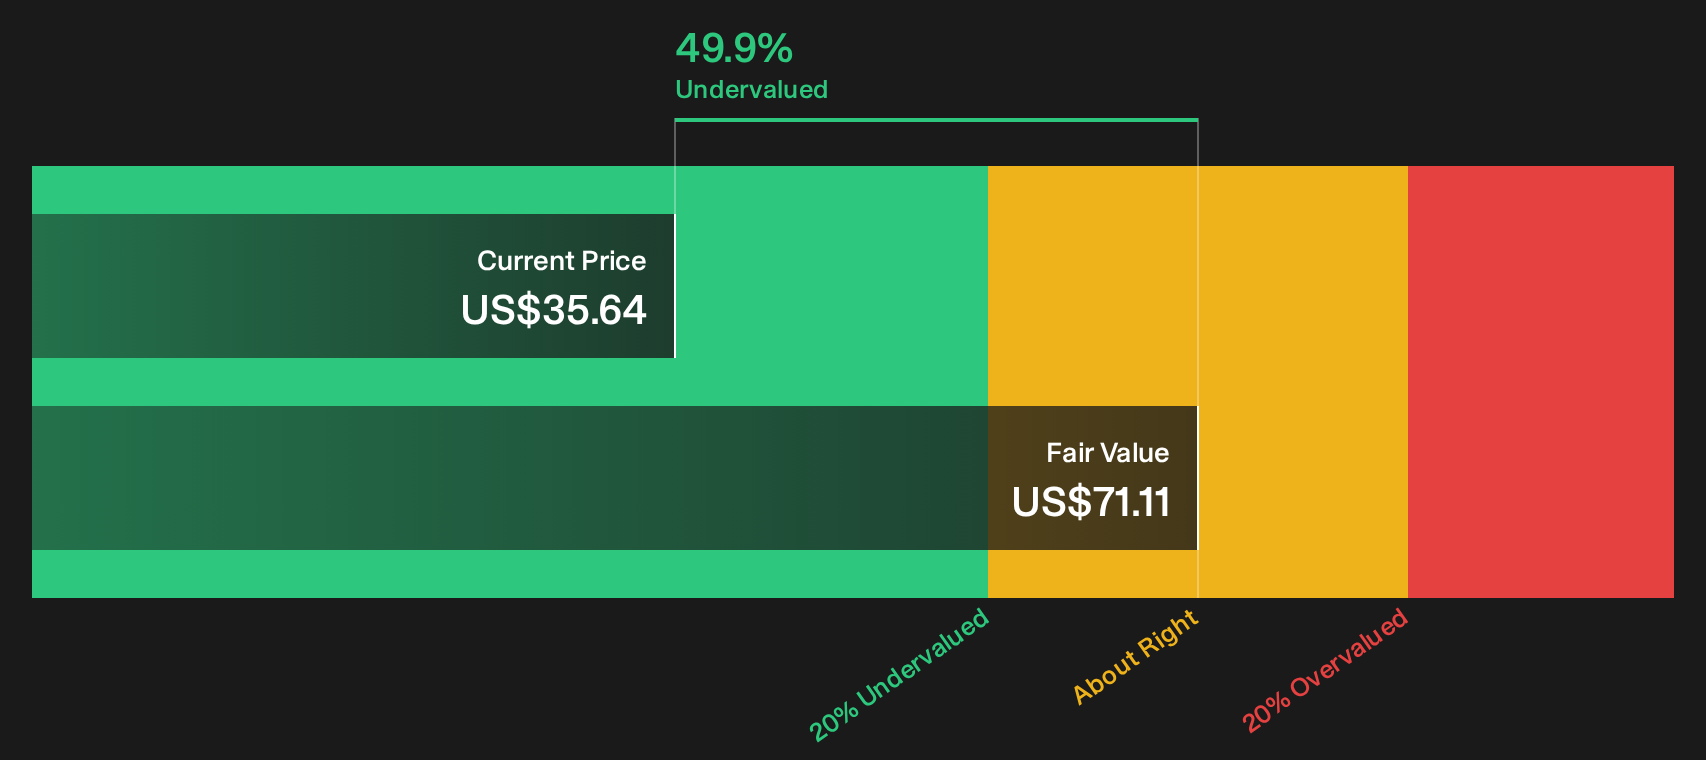
The bearish fair value of $23.00 leans on analyst expectations. A different lens tells a very different story. Our DCF model estimates Dropbox stock at $71.11, which is almost double the current $35.64 price and frames the recent move as potentially undervalued rather than stretched.
That raises a direct question for you. Is the analyst driven narrative too cautious, or is the DCF too optimistic about future cash flows and margin durability, especially with AI costs in the mix?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of caution and optimism around Dropbox feels familiar, that is the point; markets rarely line up neatly on one side. Move fast, review the underlying numbers for yourself, and stress test your own thesis against the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Dropbox?
Do not stop your research with a single stock. Broaden your watchlist using focused screeners that surface opportunities you might otherwise miss.
- Target quality at a discount by scanning companies flagged as 34 high quality undervalued stocks before the crowd pays attention.
- Prioritise resilience and sleep easier at night by checking a 29 resilient stocks with low risk scores that filters for sturdier businesses.
- Hunt for the next potential standout by reviewing a 19 high quality undiscovered gems that highlights overlooked ideas with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com