


Domino's Pizza Group (LSE:DOM) reported a third quarter 2026 trading update showing total system sales up 3.5%, a move that sharpened investor interest in how the business is executing its UK and Ireland franchise model.
The recent trading update lands after a strong run in the shares, with a 1-month share price return of 9.18% and a year to date share price gain of 34.60%, suggesting momentum has been building in Domino's Pizza Group.
Scan beyond Domino's Pizza Group and review our hand picked list of 13 high quality undervalued stocks to see how other consumer-focused franchises are trading.
Domino's Pizza Group has delivered strong share price gains alongside a modest 3.5% sales uplift. Is the current valuation still skewed towards attractive upside, or has the balance tipped towards downside risk?
Most Popular Narrative: 1% Overvalued
The most followed narrative puts Domino's Pizza Group fair value at £2.32, almost in line with the £2.33 last close. This frames the recent share price strength as only slightly ahead of that estimate.
The digital first ordering platform and upcoming national rollout of a data driven loyalty program, already active with around 2.2m customers on the pilot, is moving onto a new system. Management expects to use this to increase order frequency and migrate some aggregator users into owned channels, which can support revenue and net margins.
See why 21 investors see Domino's Pizza Group as 1% overvalued.
Result: Fair Value of £2.32 (ABOUT RIGHT)
Still, if franchise store economics remain pressured by labour and tax costs, or if chicken and loyalty uptake underwhelm, the current Domino's Pizza Group thesis could soften.
Find out about the key risks to this Domino's Pizza Group narrative.
Another View: Domino's Pizza Group Through The Earnings Lens
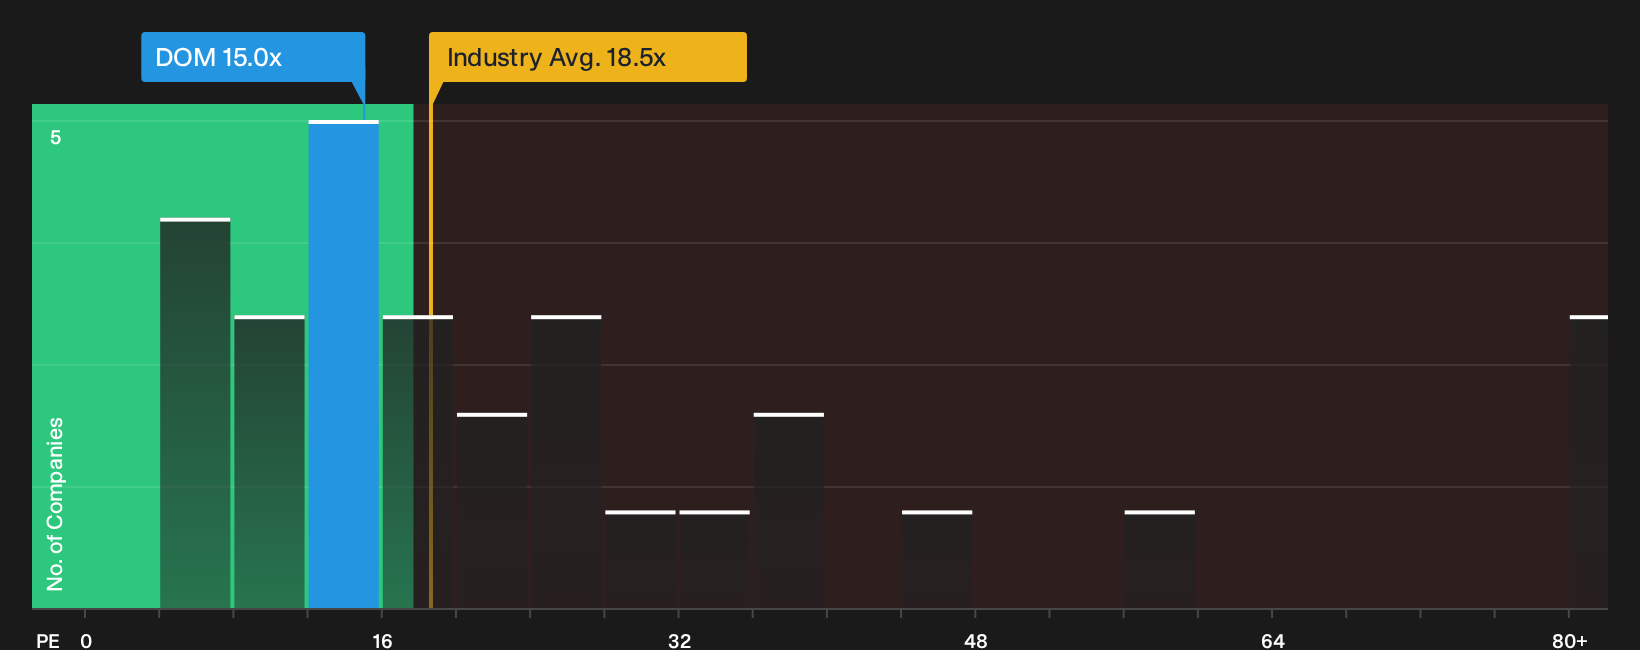
A different lens on Domino's Pizza Group comes from its P/E ratio. The shares trade on roughly 15x earnings compared with about 18.5x for the wider UK Hospitality group and 18.8x for peers, while the fair ratio sits nearer 17.3x. That gap hints at valuation risk running lower than sector averages, although it also raises a simple question. If sentiment cools, does the discount narrow or widen from here?
To see how this earnings based view lines up with other checks on Domino's Pizza Group, take a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Domino's Pizza Group after all that, or starting to lean one way? Either way, move quickly and stress test your own thesis with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Domino's Pizza Group?
If you stop with Domino's Pizza Group and never look wider, you could miss other opportunities that fit your style even better.
- Target reliable cash generators and scan for businesses on our 5 dividend fortresses that prioritise returning income to shareholders.
- Hunt for quality at a discount by checking companies on the 5 high quality undiscovered gems before the broader market pays attention.
- Dial down portfolio stress and focus on resilience by screening for 5 resilient stocks with low risk scores that score well on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com