


- Peab AB reported third quarter 2026 sales of SEK 15,897 million and net income of SEK 975 million, with basic EPS from continuing operations at SEK 3.48.
- For the first nine months of 2026, Peab posted SEK 43,287 million in sales and SEK 1,391 million in net income.
- Next, the focus shifts to how Peab's reported earnings per share influence the investment narrative that underpins the construction group's appeal.
Scan how Peab's construction earnings story compares with other financially solid operators by reviewing our hand picked list of solid balance sheet and fundamentals (197 results) in related sectors.
What Is Peab's Investment Narrative?
To own Peab, you need to believe in a fairly steady Nordic construction story rather than a hyper growth one. The group is deeply tied into housing, infrastructure and property development across Sweden, Norway, Finland and Denmark, so the real question is whether demand and pricing can stay supportive enough for projects to earn decent returns on a capital intensive base. The latest quarter, with SEK 975 million in profit and SEK 3.48 in earnings per share, fits into that narrative as another data point showing that operations can convert a large order book into cash flow.
In the short term, the stronger nine month earnings profile and higher net income compared with last year can give management a bit more breathing room as they juggle debt, project risk and an uneven construction cycle. Analysts see earnings growth, but not at explosive levels, so the potential catalysts are more about execution discipline, bidding sensibly and managing working capital than major shifts in strategy. The main risks still relate to balance sheet leverage and how sensitive Peab is to any slowdown in activity or pricing in key markets.
That said, there is a specific pressure point in Peab's setup that could matter far more if ...
There's only one way to know the right time to buy, sell or hold Peab. Head to Simply Wall St's company report for the latest analysis of Peab's Fair Value.
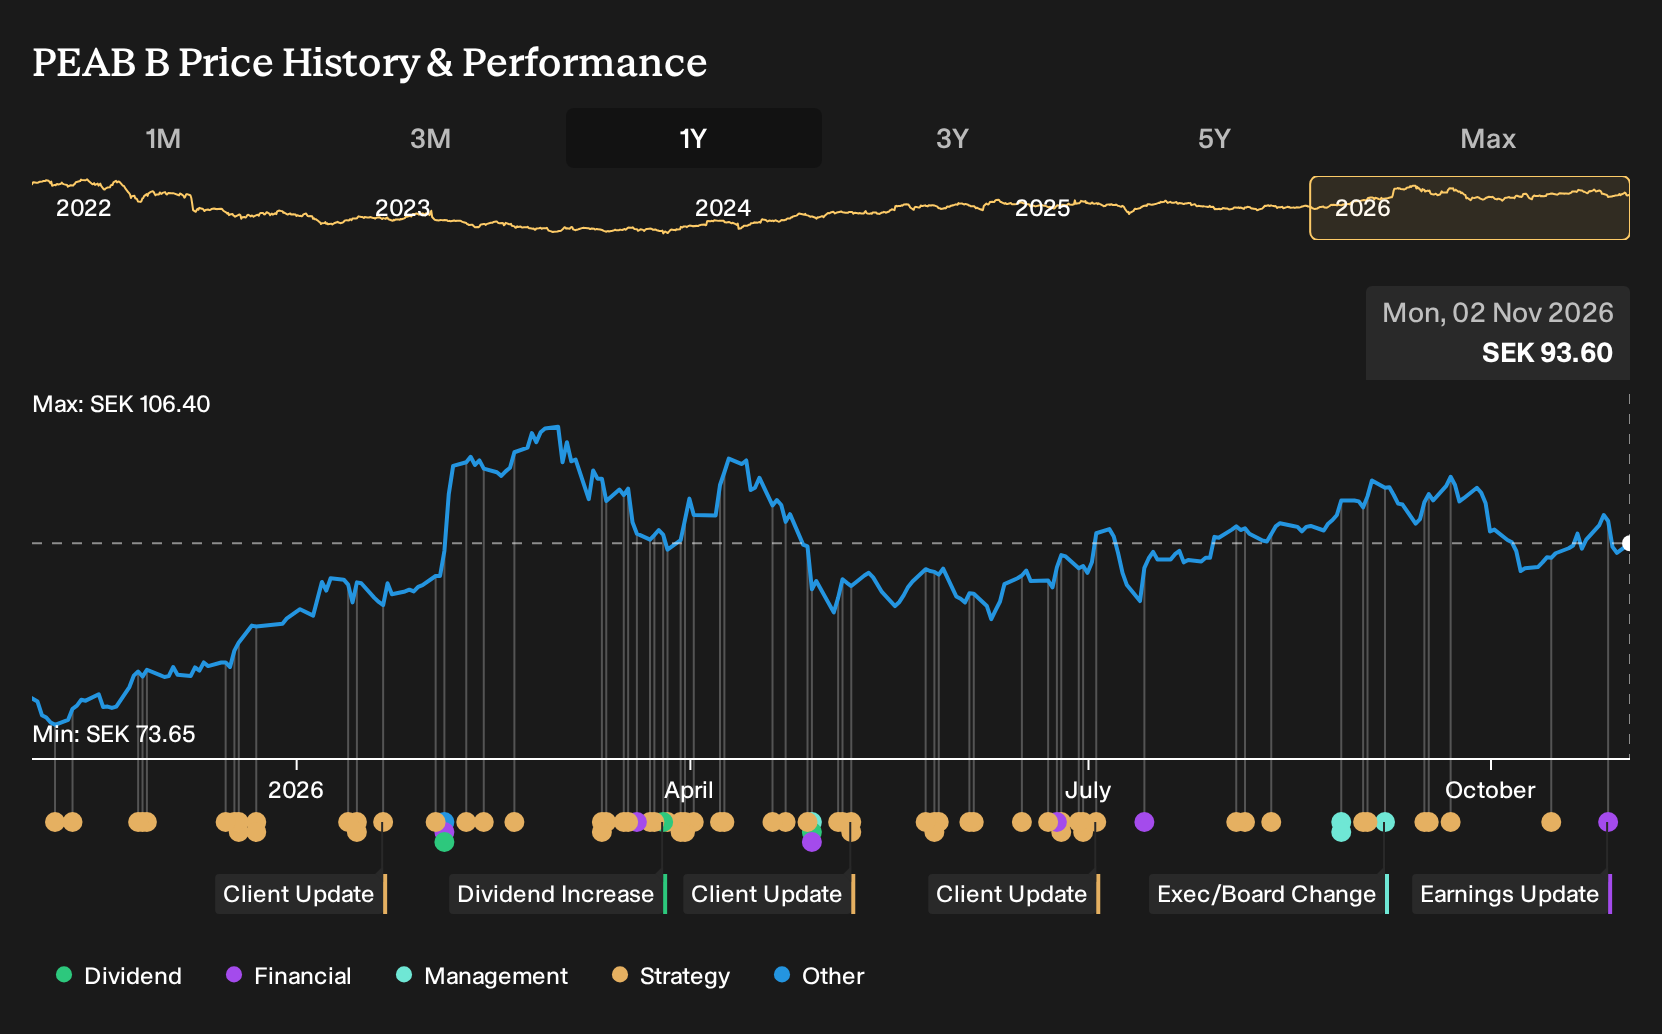
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community put Peab anywhere between SEK 74 and about SEK 179 per share, so retail opinions already span a wide gap. Those assessments were made before the latest earnings release, which means the stronger recent profit picture could prompt fresh forecasts. Investor opinions are likely to remain scattered, so consider using that spread to stress test several alternative viewpoints before committing capital.
Explore 2 other Peab fair value estimates, including one that suggests as much as 92% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own judgment.
- A useful starting point for your Peab research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Peab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Peab's overall financial health at a glance.
Looking For More Investment Ideas Beyond Peab?
If Peab has sharpened your thesis on construction and capital intensive businesses, it can help to widen the lens and see how other listed companies stack up on quality, valuation and resilience.
- For investors hunting for quality at a reasonable entry point, review companies screened as having both solid fundamentals and attractive pricing through our 193 high quality undervalued stocks.
- If capital protection and steadier profiles matter most to you, consider broadening your watchlist with a 216 resilient stocks with low risk scores that filters for businesses with lower risk scores.
- When you want to uncover potential outliers that the market may not be paying full attention to, scan our 603 high quality undiscovered gems that focuses on underfollowed companies with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com