


Amneal Pharmaceuticals has delivered a very strong share price run in recent years, which naturally puts a spotlight on what investors are now paying for its earnings. With the stock recently closing at US$20.44, the live question is how that price lines up with the profits the business is generating today.
- Over the past 3 years, Amneal Pharmaceuticals has returned about 3.9x, which raises the issue of how much of that gain reflects sustainable earnings power versus higher expectations baked into the multiple.
- The company’s model in complex generics and specialty drugs can influence margins and the reliability of future cash flows, which are key ingredients when judging how much to pay for each dollar of current profit.
- Your read on Amneal Pharmaceuticals is one view; the desks covering it have another. See what analysts think Amneal Pharmaceuticals's shares could be worth.
The stock’s next move may depend on whether the earnings now support a valuation that justifies the recent share price around US$20.44.
If you want to benchmark Amneal Pharmaceuticals against other companies through the same earnings lens, it helps to scan a wider field using 34 high quality undervalued stocks.
Is Amneal Pharmaceuticals Getting Expensive on Earnings?
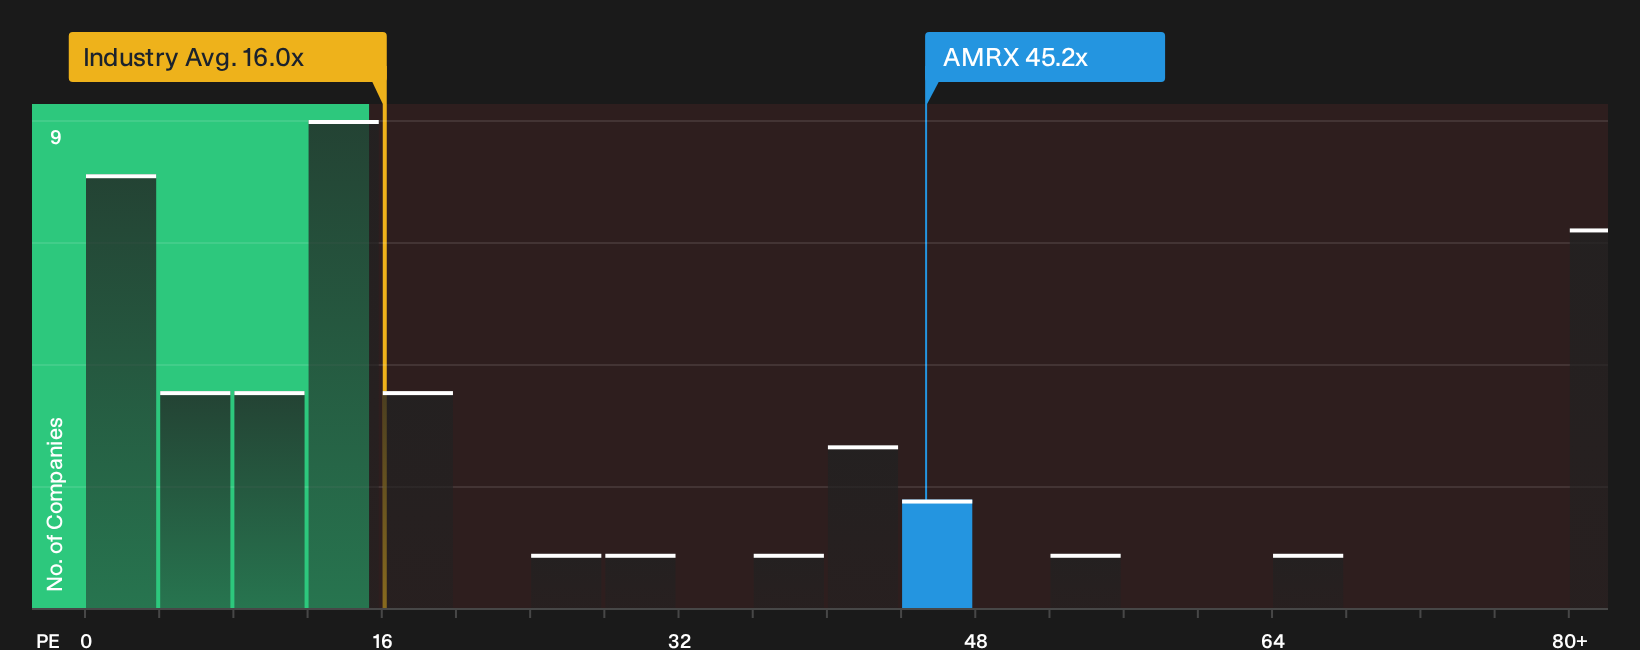
P/E suits Amneal Pharmaceuticals because earnings are now positive and investors can directly compare what they pay for each dollar of profit. At about 45.2x earnings, the stock trades well above the broader pharmaceuticals sector, where the average P/E is roughly 16.0x. It also comes in below a peer group average of about 76.0x, which shows the market is assigning Amneal a premium against the sector overall but not the highest valuation in its group.
A tailored fair value framework that blends the company’s growth profile, margins, size and risk points to a lower P/E as a reference level than the current 45.2x, so the shares screen as overvalued on this metric. For anyone assessing Amneal Pharmaceuticals, that gap means the current quote already bakes in confident expectations about how earnings will hold up, and it raises the bar for future results to keep the multiple from compressing. Explore the numbers behind Amneal Pharmaceuticals's P/E valuation.
The Amneal Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Amneal Pharmaceuticals pick up where the valuation puzzle leaves off and explain which potential paths for future growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s share price. Each scenario links a fair value estimate to a particular mix of potential catalysts and risks for Amneal Pharmaceuticals' business, allowing you to track which storyline appears to be unfolding over time on the Community page.
Community views on Amneal Pharmaceuticals are split between those who see more upside left and those who think expectations already look full.
Bull case: 11% undervalued
"Management is targeting an additional US$1b to US$2b of Affordable Medicines revenue by 2030, which directly targets higher value revenue growth..."
Discover why this Narrative puts Amneal Pharmaceuticals at 11% undervalued.
Bear case: roughly fairly valued
"Reliance on a large and growing biosimilars pipeline, including more than 20 programs and capacity expansion, could expose Amneal Pharmaceuticals to execution setbacks and regulatory delays..."
Explore why this Narrative puts Amneal Pharmaceuticals at roughly fairly valued.
One more check on Amneal Pharmaceuticals sits with who is steering it
Price tags and profit multiples only tell part of the story, because how the leadership team thinks and what they are paid to aim for can strongly shape future outcomes. See who runs Amneal Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com