


- Spire Missouri previously filed a rate case with the Missouri Public Service Commission seeking approval for higher residential bills, approximately 11% in western Missouri and 15% in eastern Missouri, to support continued investment in its natural gas network.
- The filing outlines nearly US$808 million of capital deployed into Missouri gas infrastructure, which directly ties customer bills to the scale of recent safety and reliability spending.
- We will examine how Spire's investment narrative is affected by this Missouri rate case that links US$808 million of spending to customer bills.
Scan how other regulated utilities are priced for safety and bill stability by comparing Spire's setup with the hand picked list of solid balance sheet and fundamentals (24 results).
Spire Investment Narrative Recap
To own Spire, you need to be comfortable with a regulated gas utility that leans heavily on continuous capital spending and constructive regulators. The Missouri rate case is a clear example, directly tying US$808 million of recent work to customer bills. The near term swing factor is how closely approved rates match those costs and the timing of that recovery.
The biggest operational risk right now sits in that same regulatory bucket. Any delay, partial disallowance, or tighter view on returns would bite into earnings and cash available for the dividend, especially with interest costs flagged as a pressure point. If regulators sign off broadly as filed, the case is more of a routine, yet visible, step in Spire’s plan.
Recent commentary around Spire’s US$11.2b long term capital plan and roughly US$800 million of fiscal 2026 capex ties directly into this Missouri filing. The utility is effectively asking investors to view the rate case as one chapter in a multi year effort to refresh pipes, expand its rate base, and keep the system reliable across Missouri and newer territories such as Tennessee.
For you, the question is execution quality. Spire reports high quality earnings, steady recent profit growth and a long history as a dividend payer, yet interest coverage and free cash flow coverage of the payout have been flagged as weaker areas. Every large rate proceeding, starting with this Missouri request, becomes a key checkpoint on whether the capital plan, earnings trajectory, and balance sheet discipline still line up.
What the Spire forecasts assume
Spire's narrative projects US$3.4b revenue and US$386.0m earnings by 2029. This is based on analysts' assumption of 8.5% yearly revenue growth and an earnings increase of about US$117m from US$268.8m today.
Uncover why Spire's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
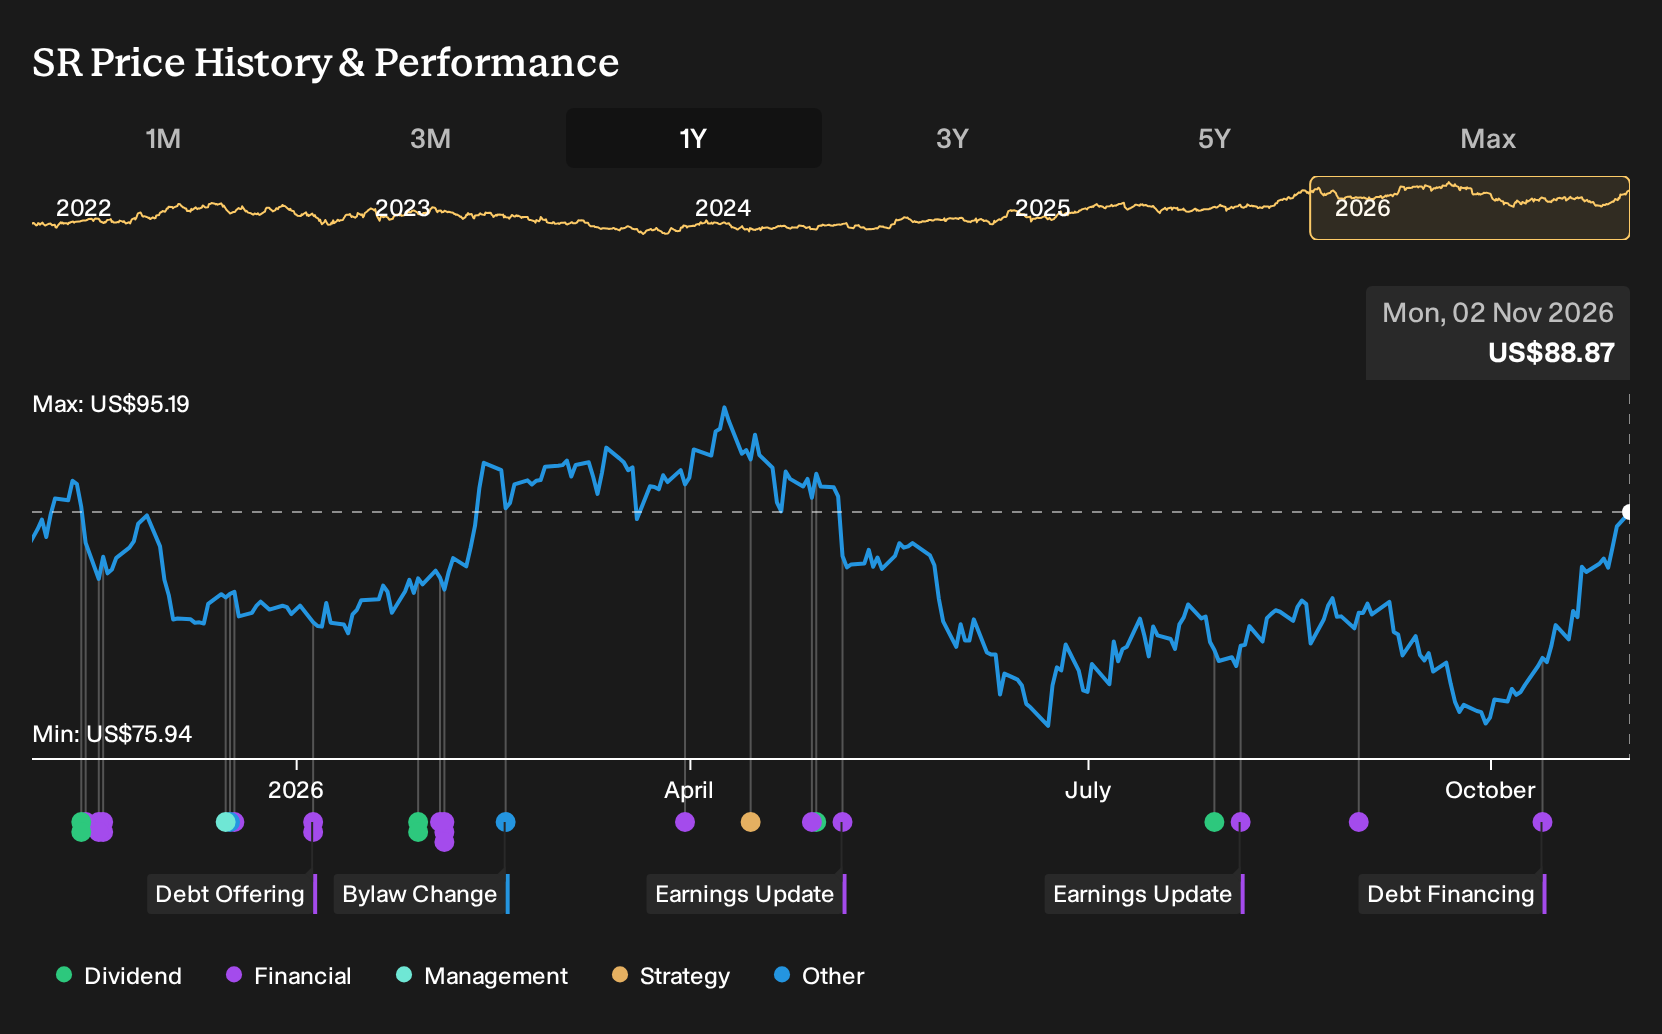
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly between about US$83.6 and US$91.4, yet those private investors are still split on where Spire should trade. When you set that against live risks around electrification and evolving ESG rules, you get a wide decision set that rewards checking multiple viewpoints.
Explore another Spire fair value estimate, including one that suggests it could be worth as much as $91.40.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Spire research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Spire. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Spire's overall financial health at a glance.
Looking for more investment ideas beyond Spire?
You do not need to stop with Spire. If you want to stress test your thesis or widen your watchlist, use the Simply Wall St Screener to line up other companies with the balance sheets, income profiles, or return patterns that fit your style.
- If capital preservation comes first for you, start with a curated set of resilient businesses by running the 29 resilient stocks with low risk scores.
- For investors who like income on top of potential price moves, consider companies with stronger yields and consistent payouts through the 4 dividend fortresses.
- If you are hunting for quality that is not yet widely followed, scan through the 19 high quality undiscovered gems and see which profiles match your checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com