


Dividend declaration puts cash returns in focus for Paycom Software
Paycom Software (PAYC) just put fresh cash on the table. The board approved a US$0.375 per share dividend, payable on December 7, 2026, to shareholders of record on November 23.
That cash return comes after a strong run in Paycom Software’s share price. The stock is up 20.39% over the past month and has posted a 74.57% year to date share price return. The 1-year total shareholder return of 45.28% points to momentum that has recently picked up following a weaker 5-year total shareholder return, which declined 46.55%.
Compare Paycom Software's dividend move and recent share price momentum with other companies on our curated list of 4 dividend fortresses.
Paycom Software now trades above the latest analyst target yet screens at roughly a 53% discount to one intrinsic value estimate. Is that gap a genuine opportunity, or is the market flashing a justified warning sign?
Most Popular Narrative: 9% Overvalued
On Simply Wall St’s most followed narrative, Paycom Software screens with a fair value of $244.65, which sits below the last close of $266.04 and frames the dividend against a stock already pricing in a lot of optimism.
Management's decision to invest heavily in proprietary AI ready data centers in 2025, and its subsequent commentary that these investments are now contributing to savings in research and development and lower third party AI fees, provides a structural cost base change that can support high adjusted EBITDA margins, rising free cash flow and continued capacity for buybacks and dividends.
See why 83 investors see Paycom Software as 9% overvalued.
Result: Fair Value of $244.65 (OVERVALUED)
Still, if rival HR platforms roll out similar AI tools at lower prices, or if Paycom Software's bundled IWant fails to drive broader module uptake, that upbeat margin narrative could fray.
Find out about the key risks to this Paycom Software narrative.
Another View on Paycom Software’s Value
Analyst targets peg Paycom Software at a fair value of $244.65, which frames the stock as about 9% overvalued versus the last close of $266.04. The SWS DCF model points in the opposite direction and values future cash flows at $563.56 per share, implying deep upside instead.
The gap is wide enough that it raises a simple question for investors: Do you trust the more conservative earnings based targets, or does a cash flow lens better match how you see Paycom Software’s long term potential to turn its automation stack into hard dollars?
Look into how the SWS DCF model arrives at its fair value.
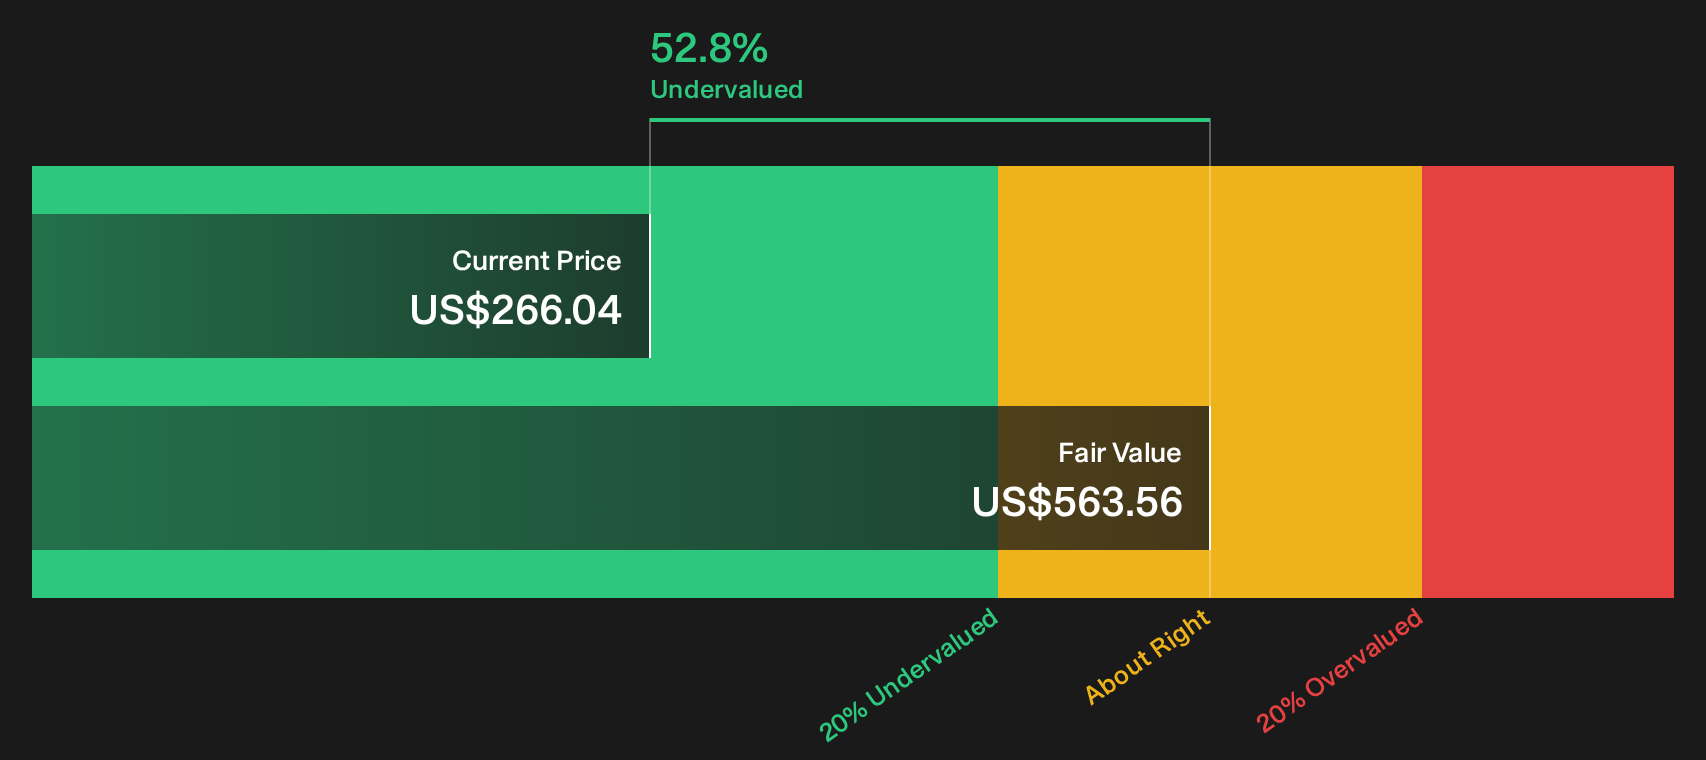
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Paycom Software for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Paycom Software’s value and risk profile make this a moment to move fast, review the numbers yourself, and pressure test the story from both sides. Before settling on a view, weigh the 3 key rewards and 2 important warning signs.
Looking for more Paycom Software sized investment ideas?
Do not stop at Paycom Software. Broaden your watchlist with fresh ideas filtered by quality, value, and resilience so you are not relying on a single story.
- Pinpoint potential bargains that pair solid financial strength with attractive pricing by scanning our hand picked 34 high quality undervalued stocks.
- Build a sturdier portfolio foundation by focusing on companies with clean balance sheets and dependable fundamentals in the list of solid balance sheet and fundamentals (24 results).
- Get ahead of the crowd by hunting for underfollowed opportunities with strong numbers hiding in plain sight across the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com