


What Donaldson’s new note program means for equity investors
Donaldson Company (DCI) has set up a new Note Purchase Agreement that allows up to US$1.5b of senior unsecured notes, with US$250m of initial Series 2026-A notes expected to fund in January 2027.
The first US$250m tranche is split across three maturities with fixed coupons between 5.93% and 6.23%. This structure provides Donaldson with long term funding visibility and locks in interest costs at defined levels.
Recent months have been busy for Donaldson Company, with the Alpha Pore filtration launch, the Facet Filtration acquisition and now this US$1.5b note program all landing while the stock trades at US$85.33 after a 2.9% 1-day share price gain and a 2.3% 1-year total shareholder return that contrasts with a 50% 5-year total shareholder return, suggesting near-term momentum has cooled even as the longer-run record remains strong.
Scan how Donaldson Company’s new debt play compares with other industrials by reviewing a curated set of 29 resilient stocks with low risk scores that pair balance sheet resilience with measured growth plans.
Donaldson Company looks like a solid filtration business with fresh products, a large acquisition and new long term funding now in place. The open question is whether US$85.33 already reflects that strength.
Most Popular Narrative: 15% Undervalued
Donaldson Company’s most followed valuation story pegs fair value at $100.40, against the latest close of $85.33. This points to a meaningful discount and puts the new note program in the context of a business that analysts already see as underpriced on fundamentals.
Expansion of Donaldson Company’s recurring aftermarket base, which currently accounts for about two thirds of revenue and roughly 80% of Mobile Solutions and about 50% of Industrial, is expected to keep smoothing revenue across cycles and support earnings resilience as the installed base grows and filters require regular replacement.
See why 11 investors see Donaldson Company as 15% undervalued.
Result: Fair Value of $100.40 (UNDERVALUED)
Still, the Donaldson Company story can break if Life Sciences and bioprocessing remain slower for longer, or if efforts to improve Industrial margins related to Facet take much longer than expected.
Find out about the key risks to this Donaldson Company narrative.
Another View on Donaldson Company’s valuation
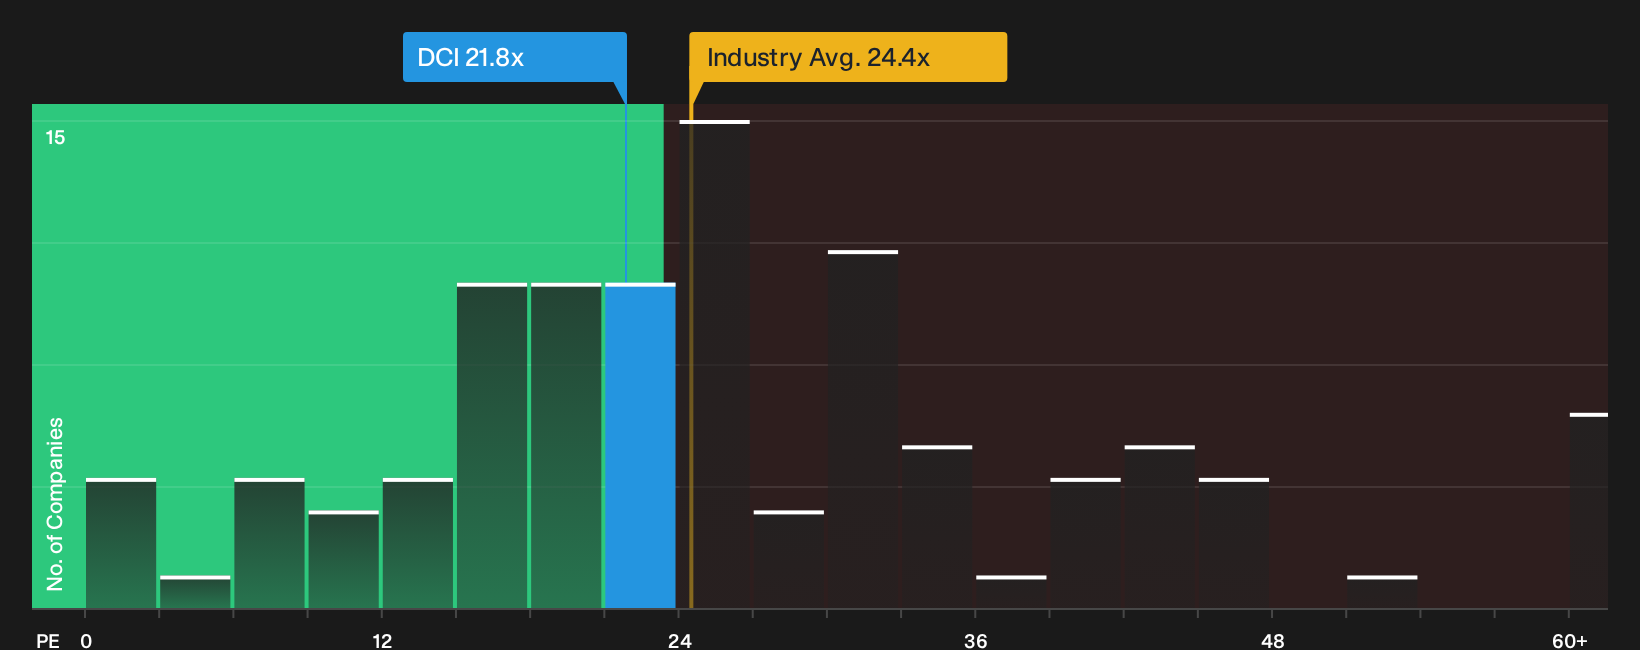
That 15% discount to a US$100.40 fair value rests on future earnings estimates. The current P/E of 21.8x offers a different angle. It is slightly above a fair ratio of 20.8x, yet sits below both the peer average of 27.8x and the US Machinery industry on 24.4x. For investors, that mix of modest premium to the fair ratio and discount to peers raises a practical question: Is Donaldson Company priced for reasonable execution or already charging you for quality?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Donaldson Company’s value and new debt package are clear, so move quickly to check the underlying numbers and shape your own stance using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Donaldson Company?
Donaldson Company may be your starting point, but widening your watchlist now can surface opportunities you will wish you had seen earlier.
- Target resilient compounding potential by reviewing a 4 dividend fortresses that focuses on income strength backed by substantial payout support.
- Spot potential mispricings early by scanning a 19 high quality undiscovered gems that couples solid fundamentals with limited current market attention.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (24 results) that pairs financial flexibility with disciplined capital allocation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com