


The semiconductor sell-off has been brutal, with Intel, Nvidia and other chip giants shedding billions in market value and dragging even healthy businesses toward their 52-week lows. Sharp pullbacks like this can leave sturdier companies mispriced, which matters if you are hunting for value or trying to avoid a falling knife. This article walks through three beaten-up semiconductor stocks exposed to the recent news and what their new valuations might signal.
The stocks covered below are just a small sample, and the full screen surfaced 19 more semiconductor companies with similarly priced-in pessimism and different twists to their stories that are not shown here. If you want to identify potential value setups for yourself, head straight into the Semiconductor value opportunities after sector-wide sell-off screener to filter, analyze, and focus on the highest conviction ideas after this sell-off.
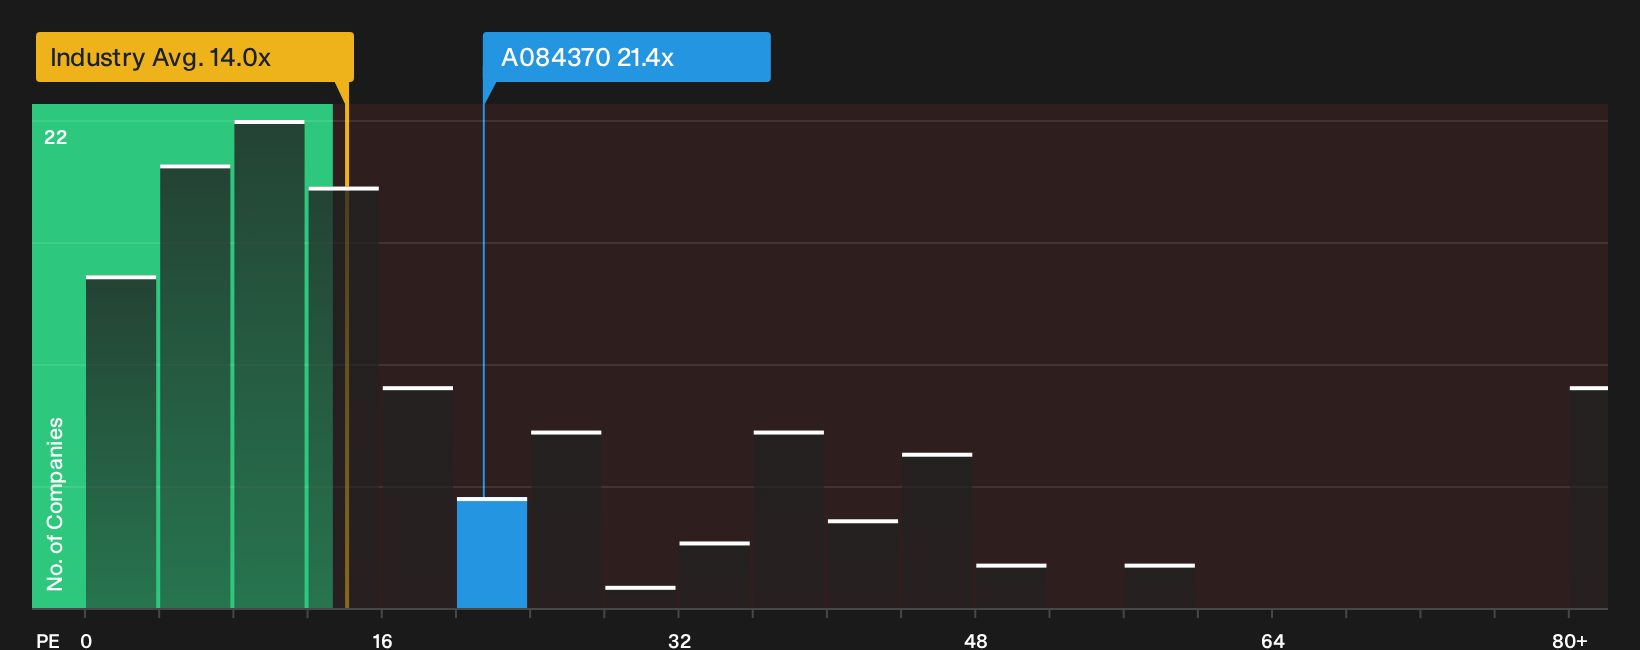
Eugene TechnologyLtd (KOSDAQ:A084370)
Eugene TechnologyLtd supplies semiconductor production gear such as LPCVD, plasma treatment, ALD and dry cleaning systems, putting it squarely in the wafer fab equipment segment targeted by this value screener. Almost all sales come from semiconductor equipment at about ₩371.1b, with smaller industrial gas revenue near ₩15.1b. The stock’s market value is about ₩2,380.1b.
Eugene TechnologyLtd fits the sell-off screen as a large Korean chip equipment supplier that has pulled back with the sector despite solid profitability, with net margins near 28.8% and strong recent earnings. Investors gain exposure to wafer-fab capex at a lower valuation. However, a single unresolved pressure on future spending still affects how that margin profile may evolve.
That unresolved capex pressure is exactly why it is worth skimming the 4 key rewards and 2 important warning signs (1 is major!) before deciding whether Eugene TechnologyLtd’s current pricing truly reflects the trade off.
BIWIN Storage Technology (SHSE:688525)
BIWIN Storage Technology focuses on semiconductor memory across SSDs, embedded chips, and enterprise storage that feed directly into data centers and AI hardware. All CN¥26.4b of revenue comes from semiconductors, and the company has a market value around CN¥62.7b.
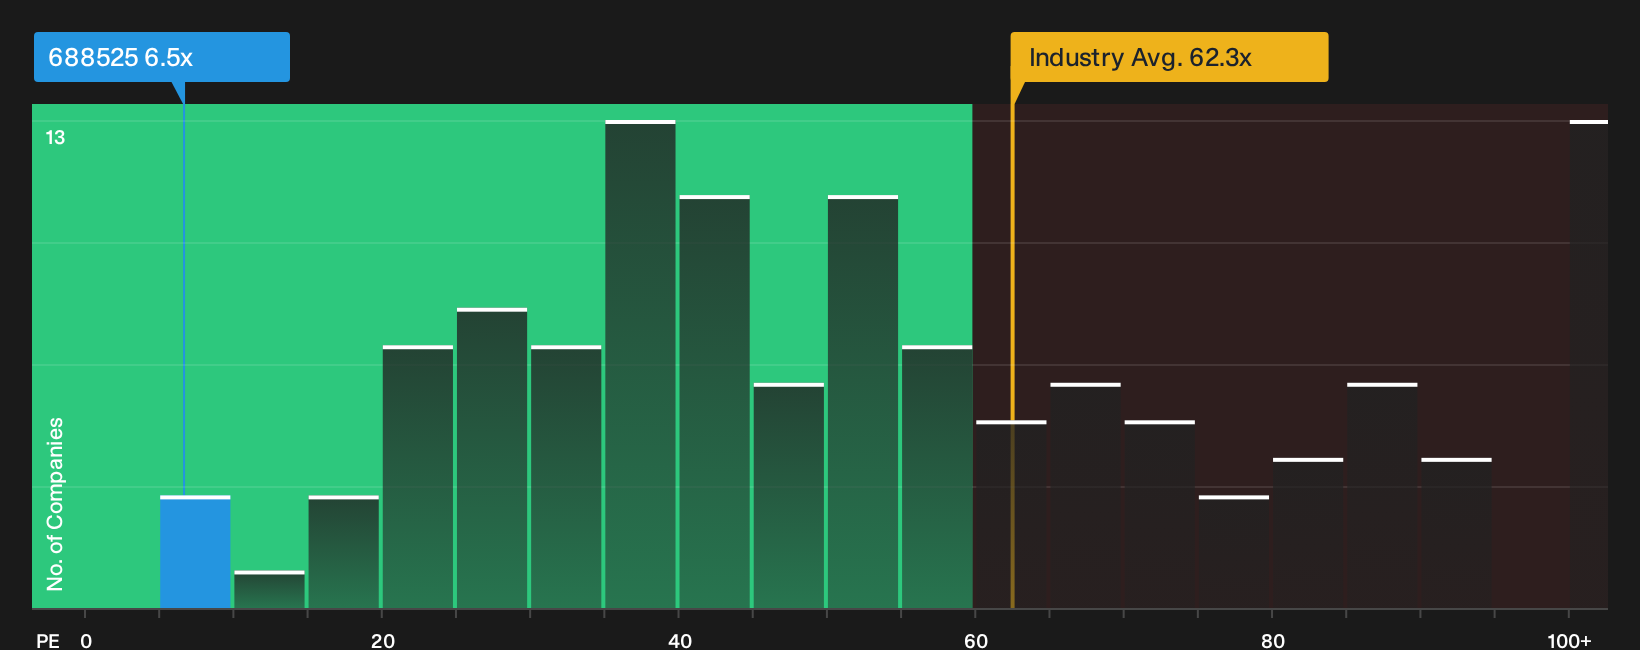
BIWIN Storage Technology aligns with this value screen, with a P/E near 6.5x compared with a richer China market and sector, a recent slide toward 52-week lows, and profitability now in place. The key question is how future cash generation will address one less visible pressure on funding and balance-sheet risk.
That quieter balance sheet question is exactly where the 4 key rewards and 4 important warning signs (3 are major!) could show whether BIWIN Storage Technology’s low P/E reflects hidden strain or mispriced resilience.
Shibaura Mechatronics (TSE:6590)
Shibaura Mechatronics is a long-established wafer and fab equipment supplier in Japan that taps the same capex cycle now on sale after the sector pullback, with its Fine Mechatronics and Mechatronics Systems units bringing in about ¥48.1b and ¥35.0b respectively and the stock valued near ¥204.5b.
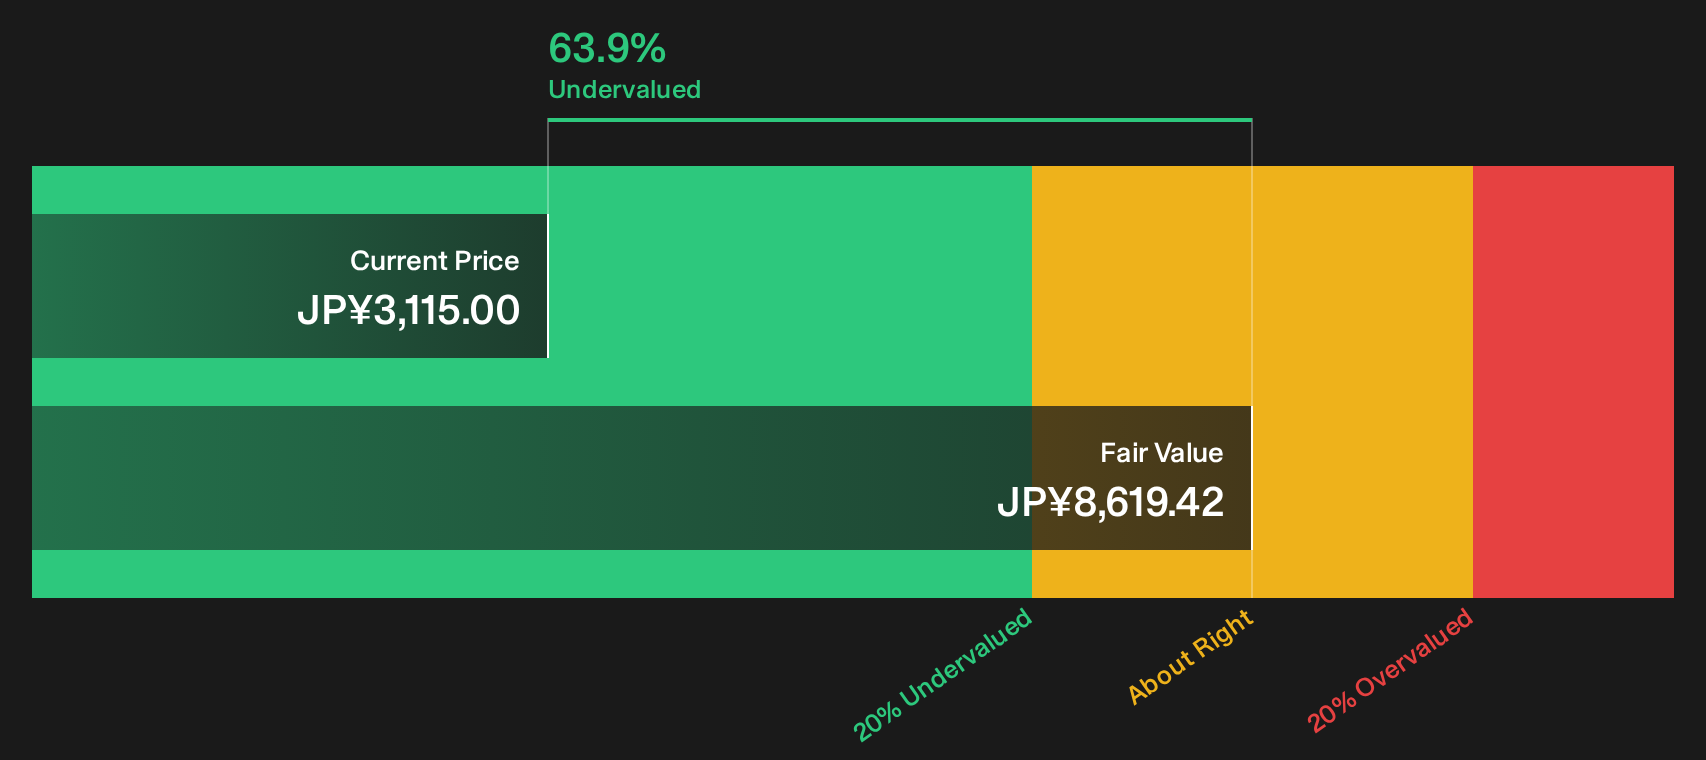
Shibaura Mechatronics gives you direct exposure to core fab tools at a time when the broader semiconductor sell-off has pushed even healthier equipment stocks down near 52-week lows. Forecasted double digit earnings and revenue growth are presented alongside a sizable discount to estimated fair value, which keeps everything dependent on how one pressure on cash flow and payouts is resolved.
That hinge on cash flow makes it worth scanning the 2 key rewards and 2 important warning signs (1 is major!) to see what might be masking or magnifying Shibaura Mechatronics’ current discount.
Curious To Explore Stronger Alternatives?
Chip stocks move fast. Fresh ideas with real momentum can get caught and repriced before the crowd even blinks, while weaker stories keep dropping. Scan these under the radar for now lists and get in early.
- Target solid cash generators and skip fragile balance sheets by scanning the list of solid balance sheet and fundamentals (197 results) that highlights financially resilient businesses before everyone else piles in.
- Chase income while others hesitate by reviewing the 223 dividend fortresses that spotlights potential high-yield payout machines that may not stay overlooked for long.
- Ride structural themes, not headlines, by checking the 43 power grid technology and infrastructure stocks that zeroes in on critical infrastructure players tied to long-term electrification demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com