


- Carpenter Technology reported first quarter 2027 sales of US$798.2 million and net income of US$162.5 million, alongside basic earnings per share from continuing operations of US$3.26.
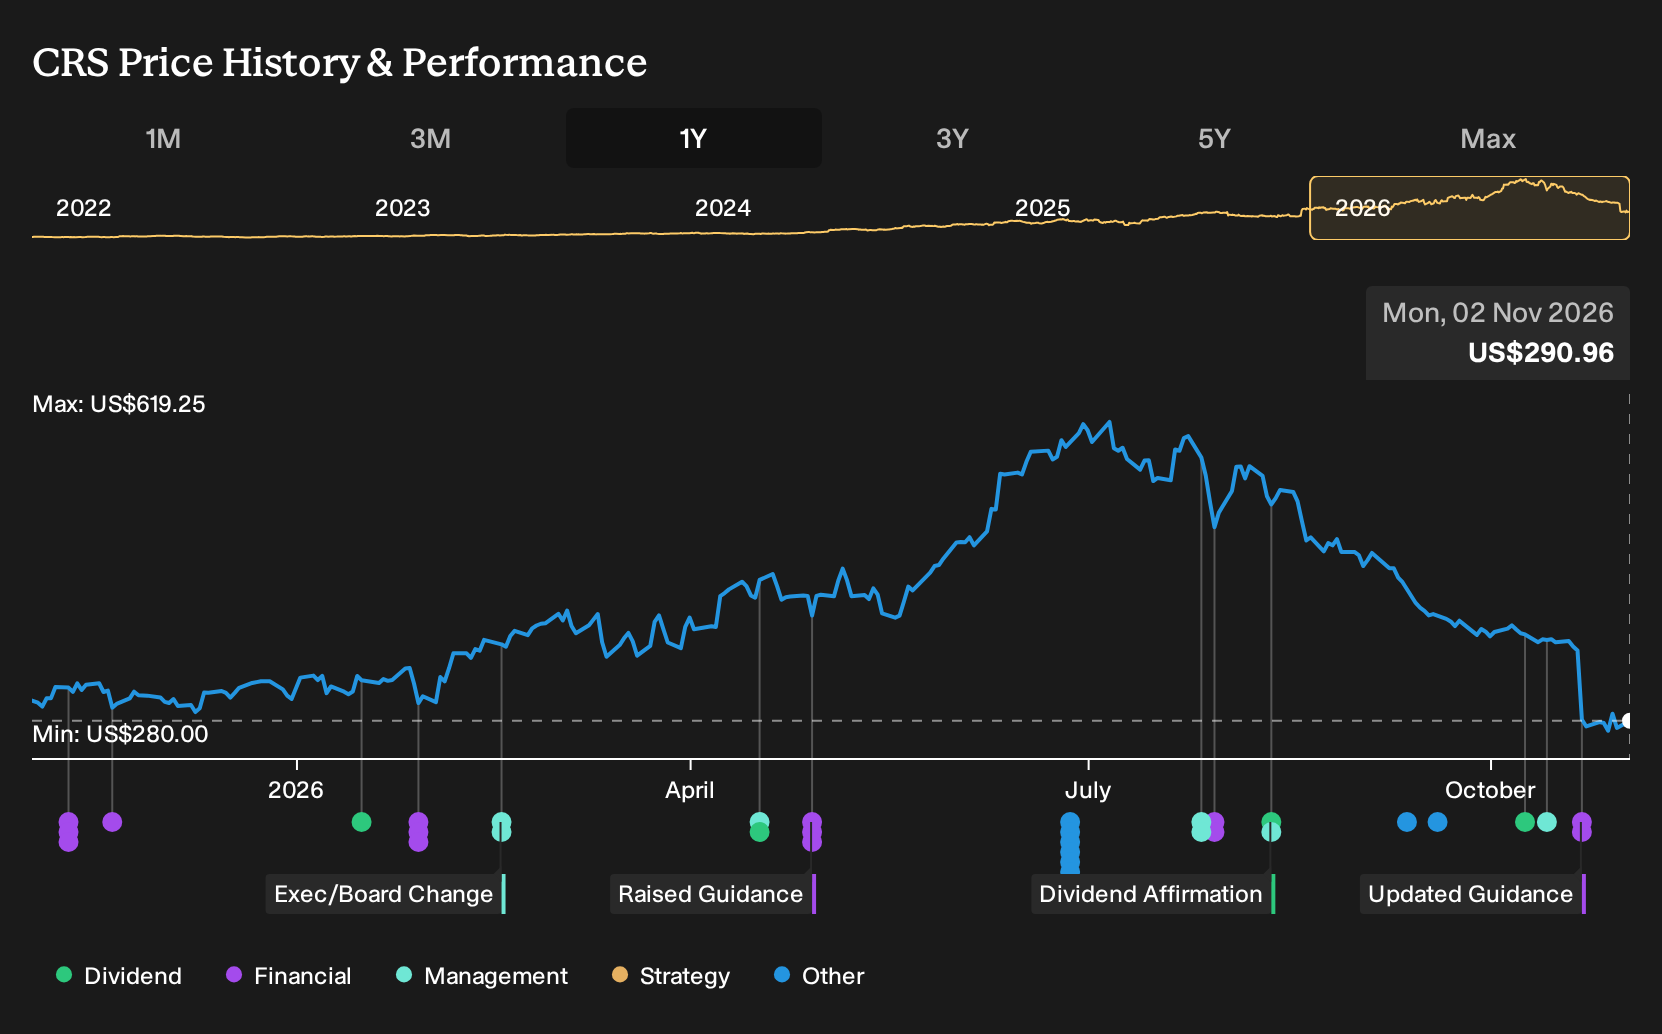
- Management kept fiscal 2027 operating income guidance in a range of US$850 million to US$880 million. This helps frame how current profitability trends connect to the longer term earnings plan already on investors’ radar.
- We will now examine how Carpenter Technology's affirmed 2027 operating income outlook could reshape the existing investment narrative around margins and cash.
Carpenter Technology Investment Narrative Recap
To own Carpenter Technology, you have to believe the current high margin, aerospace led order book can support the operating income path management has laid out while the heavy capital plan stays on track. The reaffirmed fiscal 2027 operating income range of US$850 million to US$880 million keeps that thesis intact and ties neatly to the strong first quarter print.
The near term swing factor is still execution through Specialty Alloys Operations and pricing discipline as aerospace, energy and medical volumes move through the mills. The main operational risk remains the large brownfield expansion and broader aerospace exposure, because any timing slip or weaker build rates could make that fiscal 2027 target harder to hit.
The most relevant piece of news here is the confirmed guidance for second quarter operating income of US$192 million to US$197 million, alongside the maintained full year 2027 outlook. That bridge from a single quarter to the full year gives you a concrete check on how Carpenter Technology is pacing against its stated plan.
This range effectively becomes a live stress test for margins, mix and productivity after a strong start to the year. If quarterly delivery tracks within that band while capital spending and the expansion project stay disciplined, it reduces some execution risk around the longer dated brownfield earnings contribution and provides a clearer view of how realistic the 2029 operating income ambition looks from an operational standpoint.
What The 2029 Consensus Tells You About Carpenter Technology
Analysts are effectively asking you to judge whether Carpenter Technology can grow into a much larger profit pool by 2029 while keeping its current capital heavy buildout under control. The latest consensus ties together a multi year revenue lift, higher margins and a slightly richer valuation multiple. Together these elements frame how ambitious the current price targets really are.
The report pegs revenue growth at 10.4% per year over the next three years, with profit margins moving from 17.9% today to 22.9% in roughly the same window. That combination matters more than any single quarter because it describes a business that would be converting a greater share of each sales dollar into profit at the same time as the top line is expanding.
On the earnings side, Carpenter Technology is modeled to move from US$569.5 million in earnings today to US$979.9 million by 2029, with earnings per share of US$19.84 on that endpoint. The implied earnings increase of roughly US$410 million is the core of the story investors are being asked to underwrite, since it depends on both the brownfield expansion and continued high contribution from the aerospace heavy Specialty Alloys Operations segment.
Valuation assumptions round out the picture. The consensus view has the stock trading on a P/E of 27.4x those 2029 earnings, compared with about 26.0x today and a current sector multiple quoted at 33.7x for US aerospace and defense peers. That setup asks investors to accept a premium price relative to today but not the highest multiple in the sector, based on the idea that higher future earnings and margins justify paying more for each dollar of profit.
Bringing the revenue line into focus, the same analyst set is working with a 2029 top line of about US$4.3b and earnings of US$979.9 million, both discounted at 8.0% to derive a fair value range. The forecast also bakes in a modest decline in share count of 0.56% per year over the next three years, which would add a small tailwind to earnings per share if it plays out as modeled.
Carpenter Technology's outlook implies revenue of about US$4.3b and earnings of US$979.9 million by 2029, built on 10.4% yearly revenue growth and an earnings increase of roughly US$410 million from the current US$569.5 million level.
Uncover why Carpenter Technology's fair value indicates a 51% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view on Carpenter Technology leans hard into brownfield risk. The most pessimistic analysts already pencilled in about US$4.2b of 2029 revenue and US$993.2 million in earnings, yet still used a much lower 19.5x P/E. That presents a more cautious perspective on execution, which this fresh guidance could eventually challenge or reinforce.
Explore 2 other Carpenter Technology fair value estimates, including one that suggests it could be worth just $414.57!
Reach Your Own Conclusion
Disagree with existing narratives? Consider that extraordinary investment results may sometimes come from independent thinking, so go with your instincts.
- A great starting point for your Carpenter Technology research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Carpenter Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Carpenter Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Carpenter Technology?
If the Carpenter Technology story has sharpened your thinking around margins, guidance and capital plans, it can help to widen the lens and compare it with other listed businesses that fit different quality, risk and income profiles through the Simply Wall St Screener.
- For investors who want growth potential paired with disciplined balance sheets, start with a list of solid balance sheet and fundamentals (24 results) to focus on financially stronger candidates.
- If capital preservation and steadier return profiles matter most to you, review a 29 resilient stocks with low risk scores that screens for companies with more resilient characteristics.
- When you are hunting for under followed potential, scan a 19 high quality undiscovered gems that highlights smaller businesses with strong fundamentals that may sit off the usual radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com