


Ladder Capital has delivered a 16.5% total return over the past five years, yet the share price near US$9.28 today puts fresh focus on what investors are really paying for its earnings power. With shorter term moves mixed and income focused investors watching closely, the question now is how that track record lines up with the profits the business is generating.
- The 16.5% gain across five years puts real money on the line for investors who care whether the current valuation is properly anchored to Ladder Capital's earnings.
- The company's model as a real estate finance lender means interest income, credit quality and funding costs can all shift the relationship between reported earnings and the price you pay for each dollar of profit.
- The analysts covering Ladder Capital have run their own numbers. See what analysts think Ladder Capital's shares could be worth.
For investors, the debate is whether Ladder Capital's recent share price leaves you paying too much, too little or roughly in line with what its earnings justify.
If you want to test the same earnings question you are asking of Ladder Capital against a wider field of potential ideas, run the numbers across the 34 high quality undervalued stocks.
Has Ladder Capital Run Too Far on Earnings?
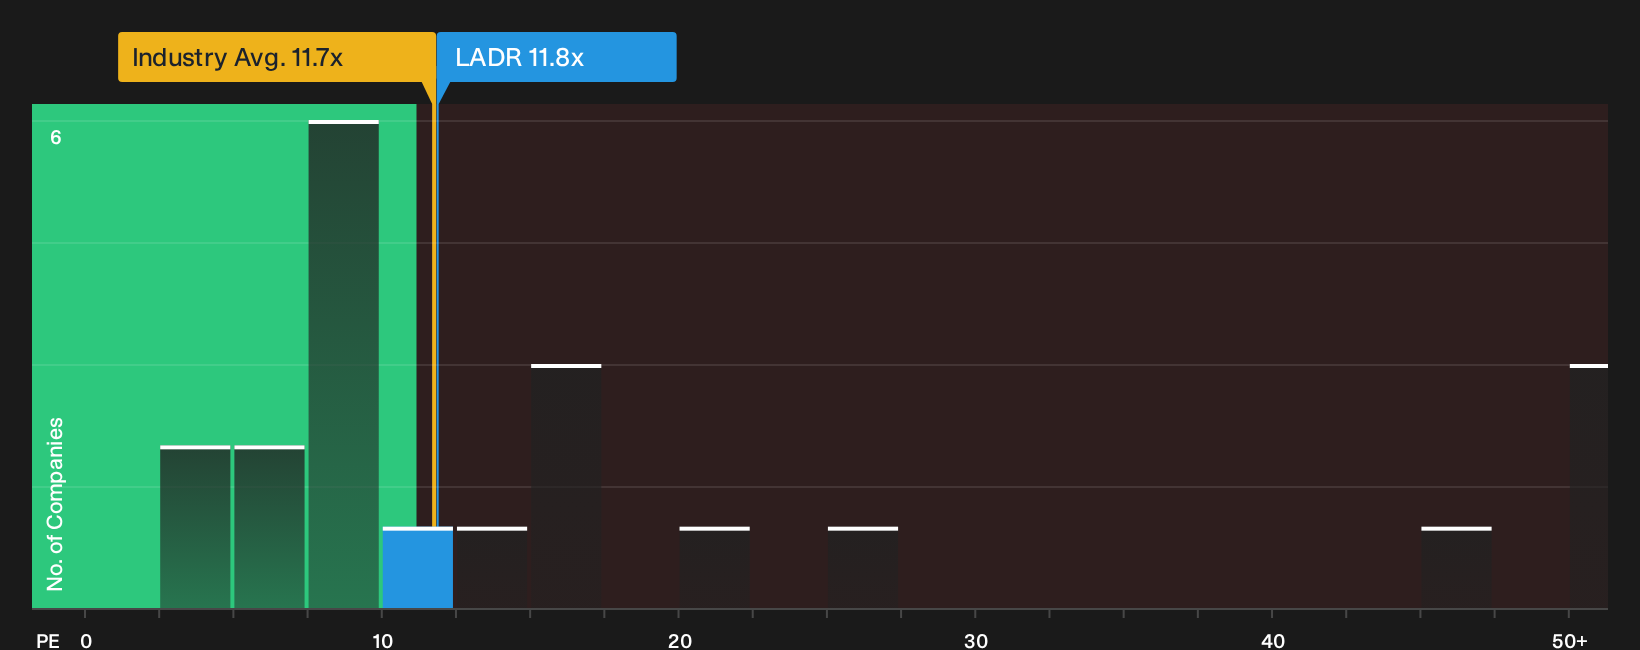
P/E works well for Ladder Capital because earnings are a key lens for a mortgage REIT where interest income and credit costs drive the story. At the current multiple of about 11.8x, the stock trades very close to the Mortgage REITs sector average of roughly 11.7x. This means the market is broadly pricing its earnings in line with the wider group. Against a peer set on about 14.3x, the shares change hands at a lower earnings multiple, which points to more cautious expectations baked into the tag on each dollar of profit.
The Fair Ratio model, which blends factors like Ladder Capital's margins, return on equity record, risk profile and size, flags a lower P/E as the level that would be more consistent with those fundamentals. That gap leaves the current 11.8x looking overvalued on this tailored yardstick, so anyone considering the stock would need to be comfortable that its earnings quality and balance sheet justify paying above that modelled range. Explore the numbers behind Ladder Capital's P/E valuation.
The Ladder Capital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ladder Capital pick up where the P/E debate stops. They spell out the specific paths for Ladder Capital's earnings, margins and growth that would need to play out for the stock to be worth materially more or less than today, and they sit on the Community page. Where a single ratio or valuation model offers one number, these frameworks describe the future that number relies on so you can watch how closely reality tracks it.
One of the top community narratives on Ladder Capital: 23% undervalued
"Enhanced portfolio management, including the rotation of capital from T bills and lower yielding AAA securities into higher yielding first mortgage loans..."
Discover why this Narrative puts Ladder Capital at 23% undervalued.
One more Ladder Capital cross check before you close the file
Price ratios and community narratives tell you what today implies, while the published projections for Ladder Capital a few years out offer a separate yardstick you can compare against the current tag. Explore where analysts expect Ladder Capital to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com