


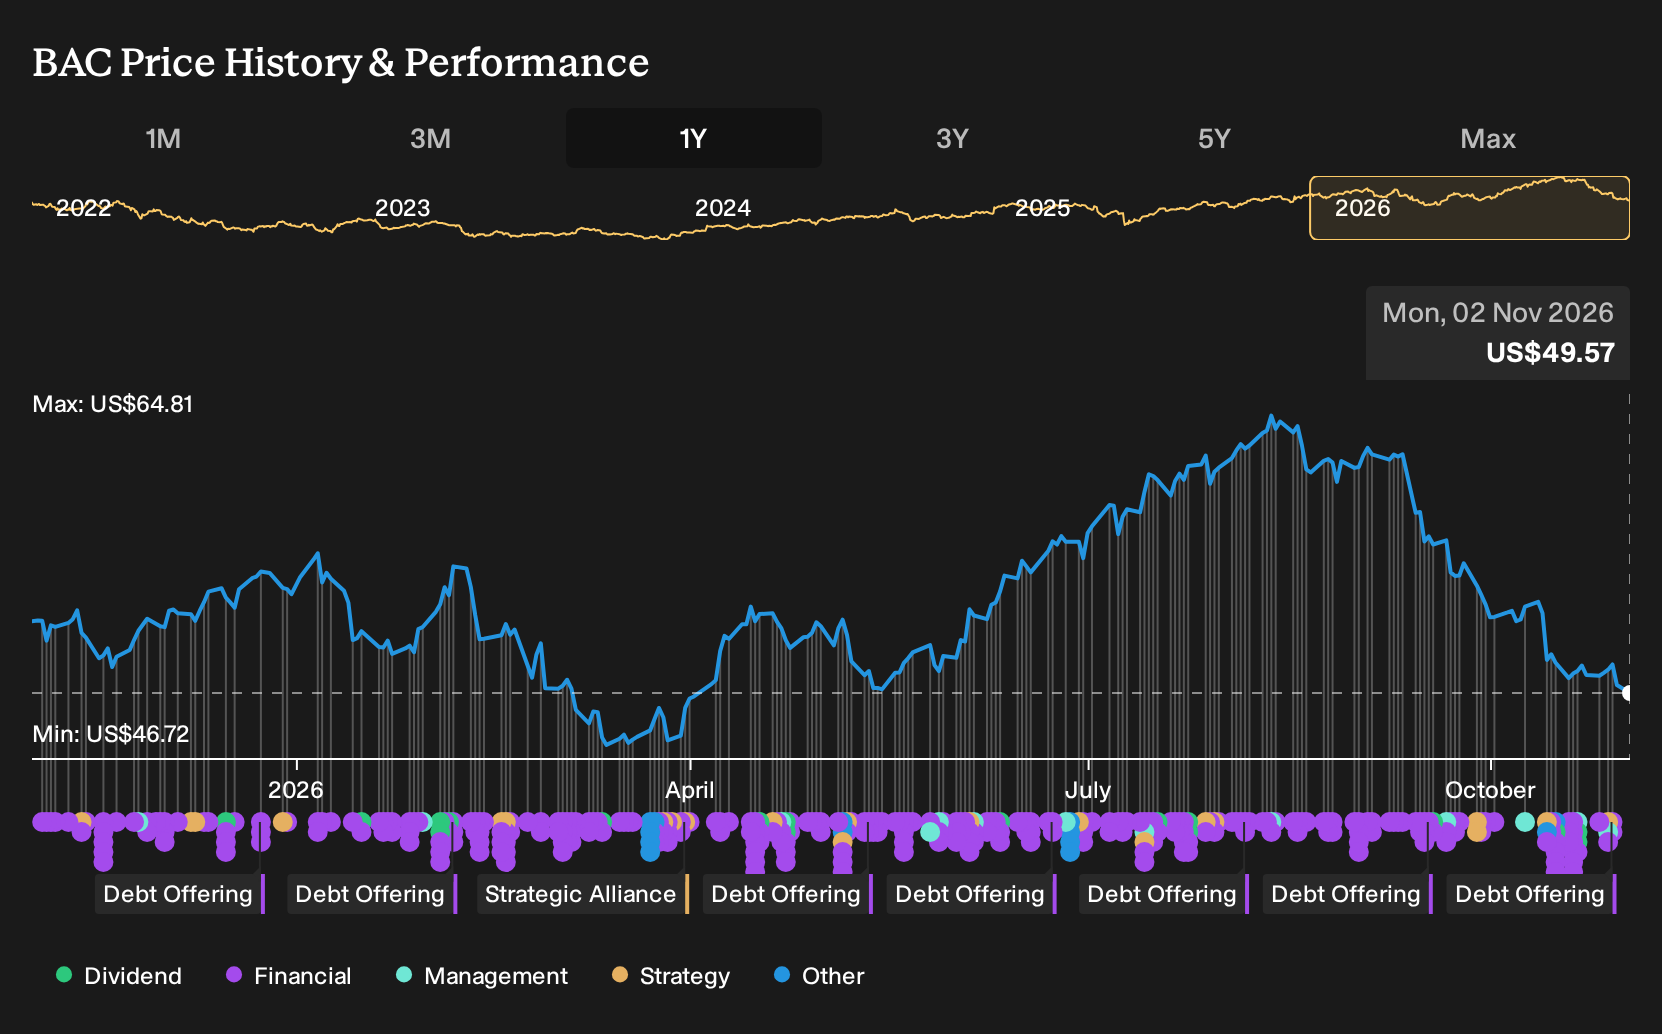
- Bank of America reported weaker than expected Q3 2026 earnings that included a US$1.2b regulatory settlement charge and a consent order requiring stronger anti money laundering oversight, with related class action lawsuits adding to legal and compliance pressures.
- The recent fixed income activity, including multiple callable senior unsecured note offerings, highlights Bank of America’s need to balance funding costs and capital structure while addressing higher compliance and litigation expenses.
- We will examine how Bank of America’s investment narrative holds up in light of the heavier regulatory settlement burden and consent order.
Scan how Bank of America's regulatory and funding reset compares with other large institutions managing legal costs, capital and dividends in our curated 29 resilient stocks with low risk scores list.
Bank of America Investment Narrative Recap
To stay invested in Bank of America, you need to believe the institution can convert its huge consumer and commercial base into steadier fee and interest income while keeping a tight grip on costs. The big short term swing factor is how quickly legal, regulatory and compliance expenses stabilize after the recent settlement and consent order, which could weigh on margins if remediation is slower or more complex than planned.
The main risk now is that higher noninterest expenses from compliance upgrades, AI investment and class action lawsuits collide with already softer capital markets fees. That mix could constrain operating leverage even if the core deposit franchise and lending engine keep doing their job, especially with management already trimming operating leverage ambitions.
The flurry of recent fixed income offerings, including the 5.05% notes due January 18, 2028 and the 6.70% notes due November 9, 2046, matters for anyone tracking Bank of America right now. These callable senior unsecured issues shape funding costs, duration and flexibility at the same time the bank is absorbing regulatory and litigation charges tied to anti money laundering oversight.
For catalysts, the key question is whether this fresh funding supports the ongoing build out of AI, digital platforms and branch expansion without pushing overall interest expense uncomfortably higher. Execution risk sits in how well Bank of America matches these higher coupon obligations with assets and fee streams that sustain earnings, while still leaving room to keep dividends and balance sheet strength intact.
Bank of America's narrative projects US$138.0b revenue and US$37.4b earnings by 2029. This aligns with analysts who assume 6.3% yearly revenue growth and an earnings increase of about US$6.6b from US$30.8b today.
Uncover why Bank of America's fair value indicates a 27% potential upside to its current price, a discount that could close more quickly than many investors expect.
Exploring Other Perspectives
Seven fair value estimates from the Simply Wall St Community cluster tightly between US$62.61 and US$69.37, so retail opinions on Bank of America sit in a relatively narrow band. You can weigh those views against fresh risks from mounting compliance lawsuits and the expansion and AI spending plans that management will discuss at upcoming forums. Opinions clearly differ, so explore several viewpoints before deciding how this story fits your portfolio.
Explore 6 other Bank of America fair value estimates, including one that suggests it could be worth just $62.61!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of America research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Bank of America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of America's overall financial health at a glance.
Looking for more investment ideas beyond Bank of America?
Once you have a view on Bank of America, it can help to broaden the watchlist with other companies that fit clear risk and reward profiles. The Simply Wall St Screener lets you filter for different styles so you can match potential holdings to your own approach instead of relying on a single headline story.
- If capital preservation sits near the top of your priority list, focus on companies that score well on stability and financial resilience through the 29 resilient stocks with low risk scores.
- For investors who want income on top of potential price moves, scan for payout heavy businesses with robust cash flows using the 4 dividend fortresses.
- If you prefer to hunt for under-followed opportunities with solid fundamentals, sift through a curated pool of quality outliers using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com