


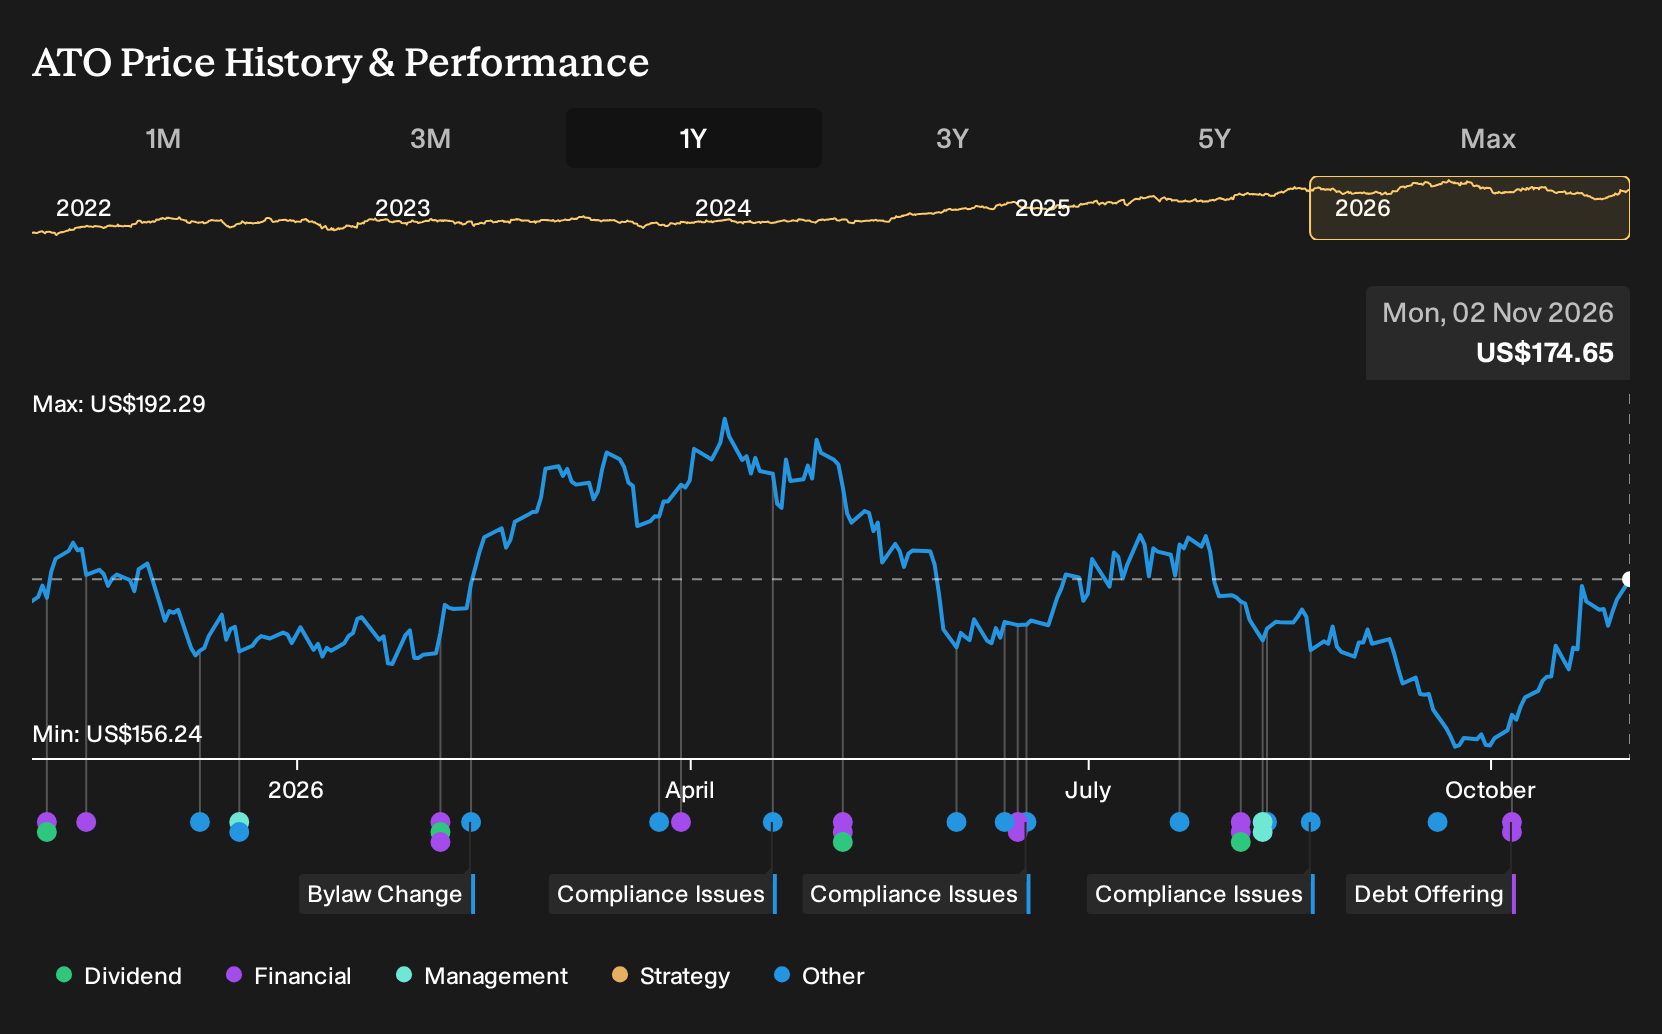
- Atmos Energy reported that it would release its fourth quarter fiscal 2026 results on November 4 after market close, with performance shaped by customer additions, natural gas demand and ongoing investment in its distribution and pipeline infrastructure.
- The upcoming earnings update will also reflect higher operating and maintenance spending, rising compliance obligations and exposure to commodity price swings that may influence how investors view the durability of Atmos Energy’s cost structure.
- We will now see how Atmos Energy’s investment narrative could be affected by its pending fourth quarter earnings release and higher expenses.
Scan how Atmos Energy’s earnings story compares to other regulated utilities by running through our hand-picked 29 resilient stocks with low risk scores, which focuses on resilient balance sheets and steadier cash flows.
Atmos Energy Investment Narrative Recap
To own Atmos Energy, you need to be comfortable with a regulated utility that leans heavily on long term capital projects, rate cases and customer additions. The near term story still revolves around how well customer growth and new infrastructure returns offset higher operating and maintenance spending. The upcoming fourth quarter update looks important for testing that balance.
The biggest short term catalyst is clear progress on converting the large fiscal 2026 capex and Texas legislation into steady earnings and cash generation. The key risk is that operating, compliance and legal costs trend higher without enough rate relief. The earnings release may refine, but not radically change, that risk reward equation.
With fourth quarter fiscal 2026 results landing on 4 November, the most relevant update is Atmos Energy’s guidance around its US$4.2b capital program for the year. Investors will be watching how much of that spend is already reflected in rate approvals and how much still depends on future regulatory decisions and load growth.
That capex focus links directly to the current catalysts. Customer additions, recent Texas legislation on cost deferrals and the US$396m of annualized operating income increases already in place work together to support returns on new assets. Execution risk sits on the other side of the ledger if project timing, costs or regulatory outcomes move against the business.
Atmos Energy Earnings Assumptions Behind The Story
Forecasts around Atmos Energy give you a rough map of what the fourth quarter update is lining up against. Analysts are building their models on the idea that revenue grows by 10.6% a year over the next three years while profit margins edge up from 28.5% today to 29.0% by around 2029. That framing matters because it shows how much of the current investment pitch leans on turning a heavy capital program and regulatory tools into slightly better profitability, not a radical shift in the economics of the business.
On earnings, the consensus anchors on Atmos Energy moving from US$1.4b of earnings today to US$1.9b by about 2029, with those forecasts broadly aligned across analysts. That step up is roughly a US$500m increase in profit over the period, helped by expected customer growth, rate mechanisms and a rising regulated asset base rather than one off gains. If the upcoming fourth quarter numbers or guidance push that earnings path higher or lower, the whole narrative around what investors are paying for Atmos Energy in 2026 may need to be revisited.
The equity story being modeled is not just about the income statement. Analysts also factor in share issuance, with the share count projected to expand by about 4.51% annually over the next three years. That assumption affects earnings per share even if total profit tracks expectations and it sets a context for how investors might assess any future equity raises that help fund the US$4.2b fiscal 2026 capex plan or subsequent programs.
Valuation work around Atmos Energy then ties these operating forecasts to what investors are assumed to pay for those future earnings. To reconcile current views, analysts assume a P/E of 22.8x on projected 2029 earnings, compared with about 19.1x today and against an industry level of 16.1x for US gas utilities. That implies a richer multiple for Atmos Energy than the wider peer group, which investors may see as hinging on confidence in Texas legislation, rate outcomes and steady execution on safety focused projects.
Atmos Energy's narrative projects US$6.7b revenue and US$1.9b earnings by 2029. This rests on revenue growing at about 10.6% per year and a roughly US$500m earnings increase from the current US$1.4b level.
Uncover why Atmos Energy's fair value indicates a 6% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
Two Simply Wall St Community fair value estimates span roughly US$134 to US$186, which already shows how far opinions on Atmos Energy can stretch. Those views do not yet reflect the upcoming US$4.2b capex year or higher operating and compliance costs, so treat them as starting points and compare several angles before you commit fresh money.
Explore another Atmos Energy fair value estimate, including one that suggests up to 6% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Atmos Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Atmos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atmos Energy's overall financial health at a glance.
Looking for more investment ideas beyond Atmos Energy?
Once you have a handle on Atmos Energy, it can help to widen the lens and compare it with other businesses that share similar financial traits or risk profiles. The Simply Wall St Screener is built for exactly that kind of side by side work, letting you filter by balance sheet strength, valuation, income potential and more.
- If you care most about stability and capital preservation, start with a curated group of companies that score well on resilience and risk using our 29 resilient stocks with low risk scores.
- For readers who want value oriented ideas, scan a focused set of potentially mispriced opportunities screened for quality fundamentals through the 34 high quality undervalued stocks.
- Income focused investors can zero in on cash return potential by checking out a targeted selection of higher yielding payers via the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com