


Ingevity has delivered a solid share price run in recent years, which naturally raises a question for anyone looking at the stock today. Is the current valuation still in step with the earnings power of the business, or has the price moved ahead of what its profit base can reasonably support?
- The stock has returned 84.0% over the past 3 years, which puts real weight on whether that gain lines up with its underlying earnings profile.
- The business model is closely tied to specialty chemicals and performance materials, so margins, capital intensity and how effectively profits translate into cash can all shape what investors are prepared to pay for each dollar of earnings.
- The analysts covering Ingevity have run their own numbers. See what analysts think Ingevity's shares could be worth.
For investors, the debate is whether Ingevity's current share price is appropriately grounded in its earnings, given how the stock has already performed.
If you want a broader watchlist of earnings focused opportunities while you research Ingevity, a targeted screen like 34 high quality undervalued stocks can be a useful next step in your process.
Does Ingevity Look Pricey on Earnings?
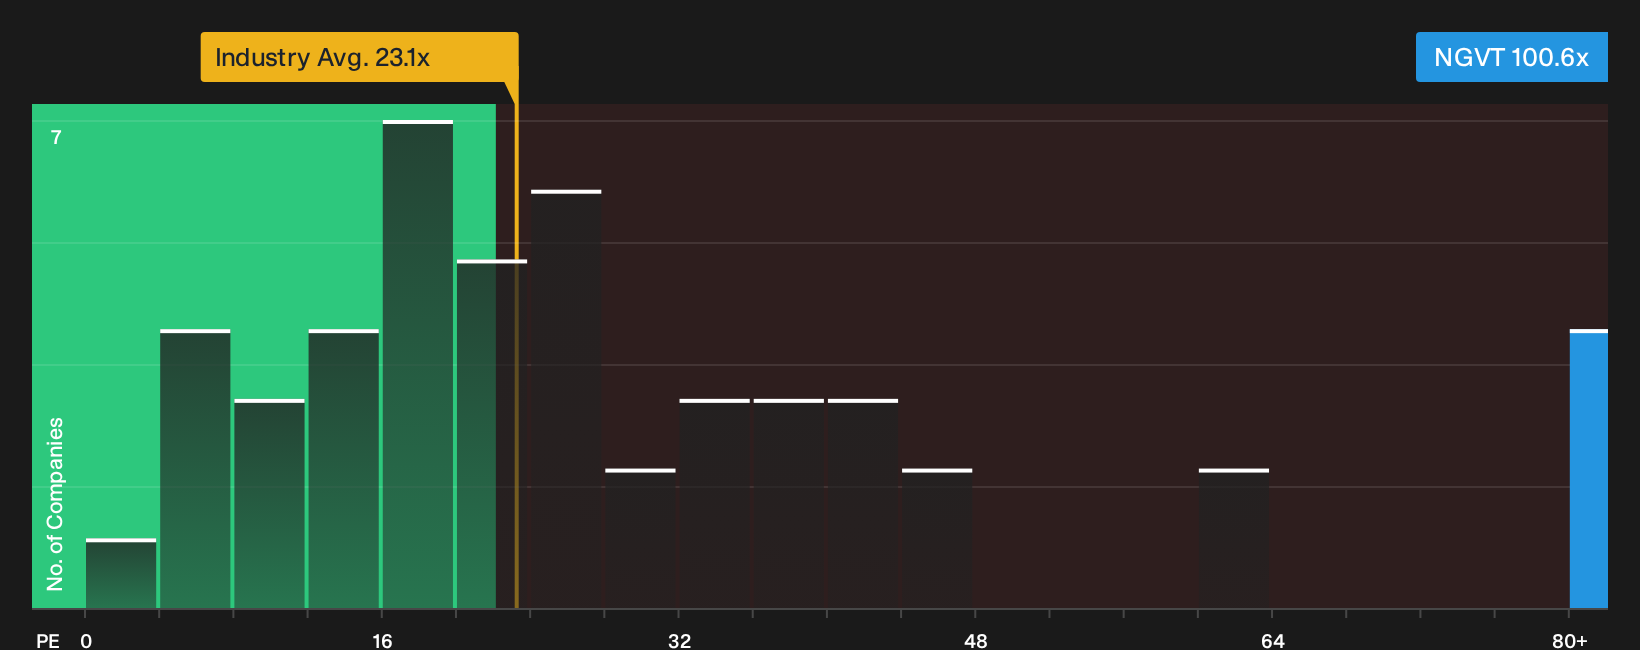
P/E works well for Ingevity because earnings remain a key anchor for how investors frame the chemicals sector. On that yardstick, Ingevity trades on a P/E of 100.6x, compared with an industry average of 23.1x for Chemicals and a peer group around 26.4x. That is a very large premium to what the wider market is paying for similar businesses, so anyone eyeing the stock is being asked to accept a lot of earnings power already reflected in the price.
The fair-value framework that blends Ingevity's growth profile, profitability, size and risk flags this gap as overvalued. The distance to that reference point is so wide that the model looks more like a warning signal than a precise target. It implies the current valuation is heavily front loading expectations about how consistently the company can convert its specialty products into durable profits. For a fresh position, the key question is whether that kind of earnings quality and resilience feels realistic at this price or whether it makes sense to wait for a P/E that sits closer to what the underlying numbers can support. Explore the numbers behind Ingevity's P/E valuation.
The Ingevity Narrative: What Would Justify Today's Price?
Narratives for Ingevity pick up where the high P/E puzzle leaves off, by laying out the specific paths for growth, margins and earnings that would need to materialise for the stock to be worth materially more or less than it is today, and they sit on Simply Wall St's Community page. Instead of giving a single ratio or model number, they unpack the future that figure relies on so you can track how closely reality follows that story over time.
One of the top community narratives on Ingevity: 17% undervalued
"Accelerated portfolio repositioning and the advanced-stage divestiture of non-core, lower-margin businesses are expected to drive a step-change in margin profile…"
Discover why this Narrative puts Ingevity at 17% undervalued.
For Ingevity, valuation is only half the story
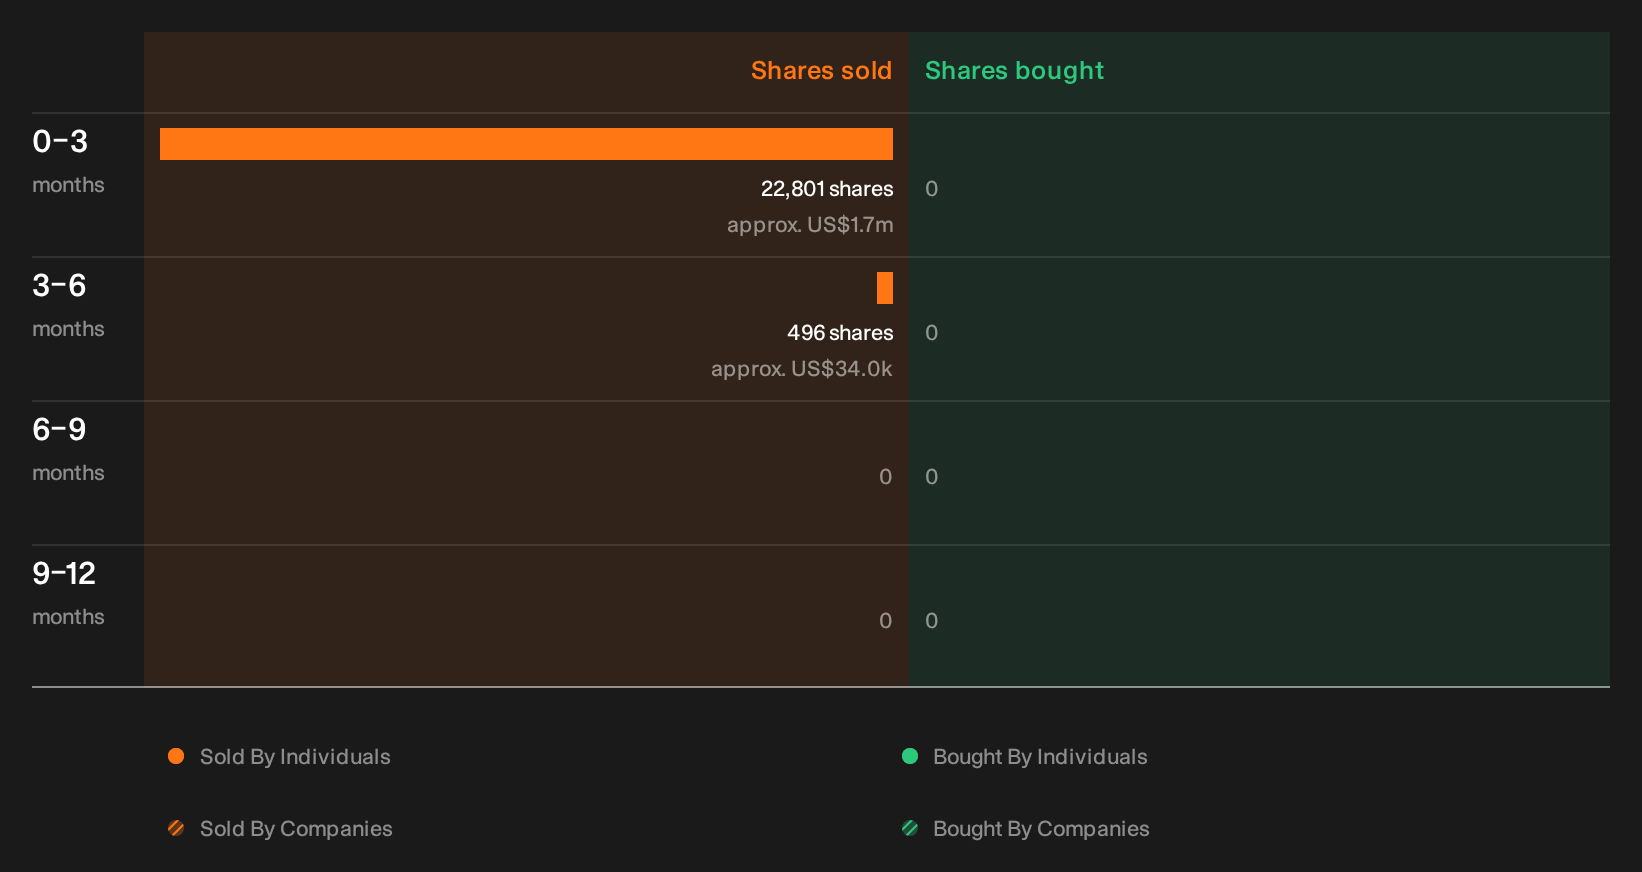
Price and earnings tell you what the market is paying today, but our checks also picked up recent share sales by people on the inside, and the who, how much and why are details worth checking for yourself. See the recent insider selling flagged for Ingevity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com